


TL;DR
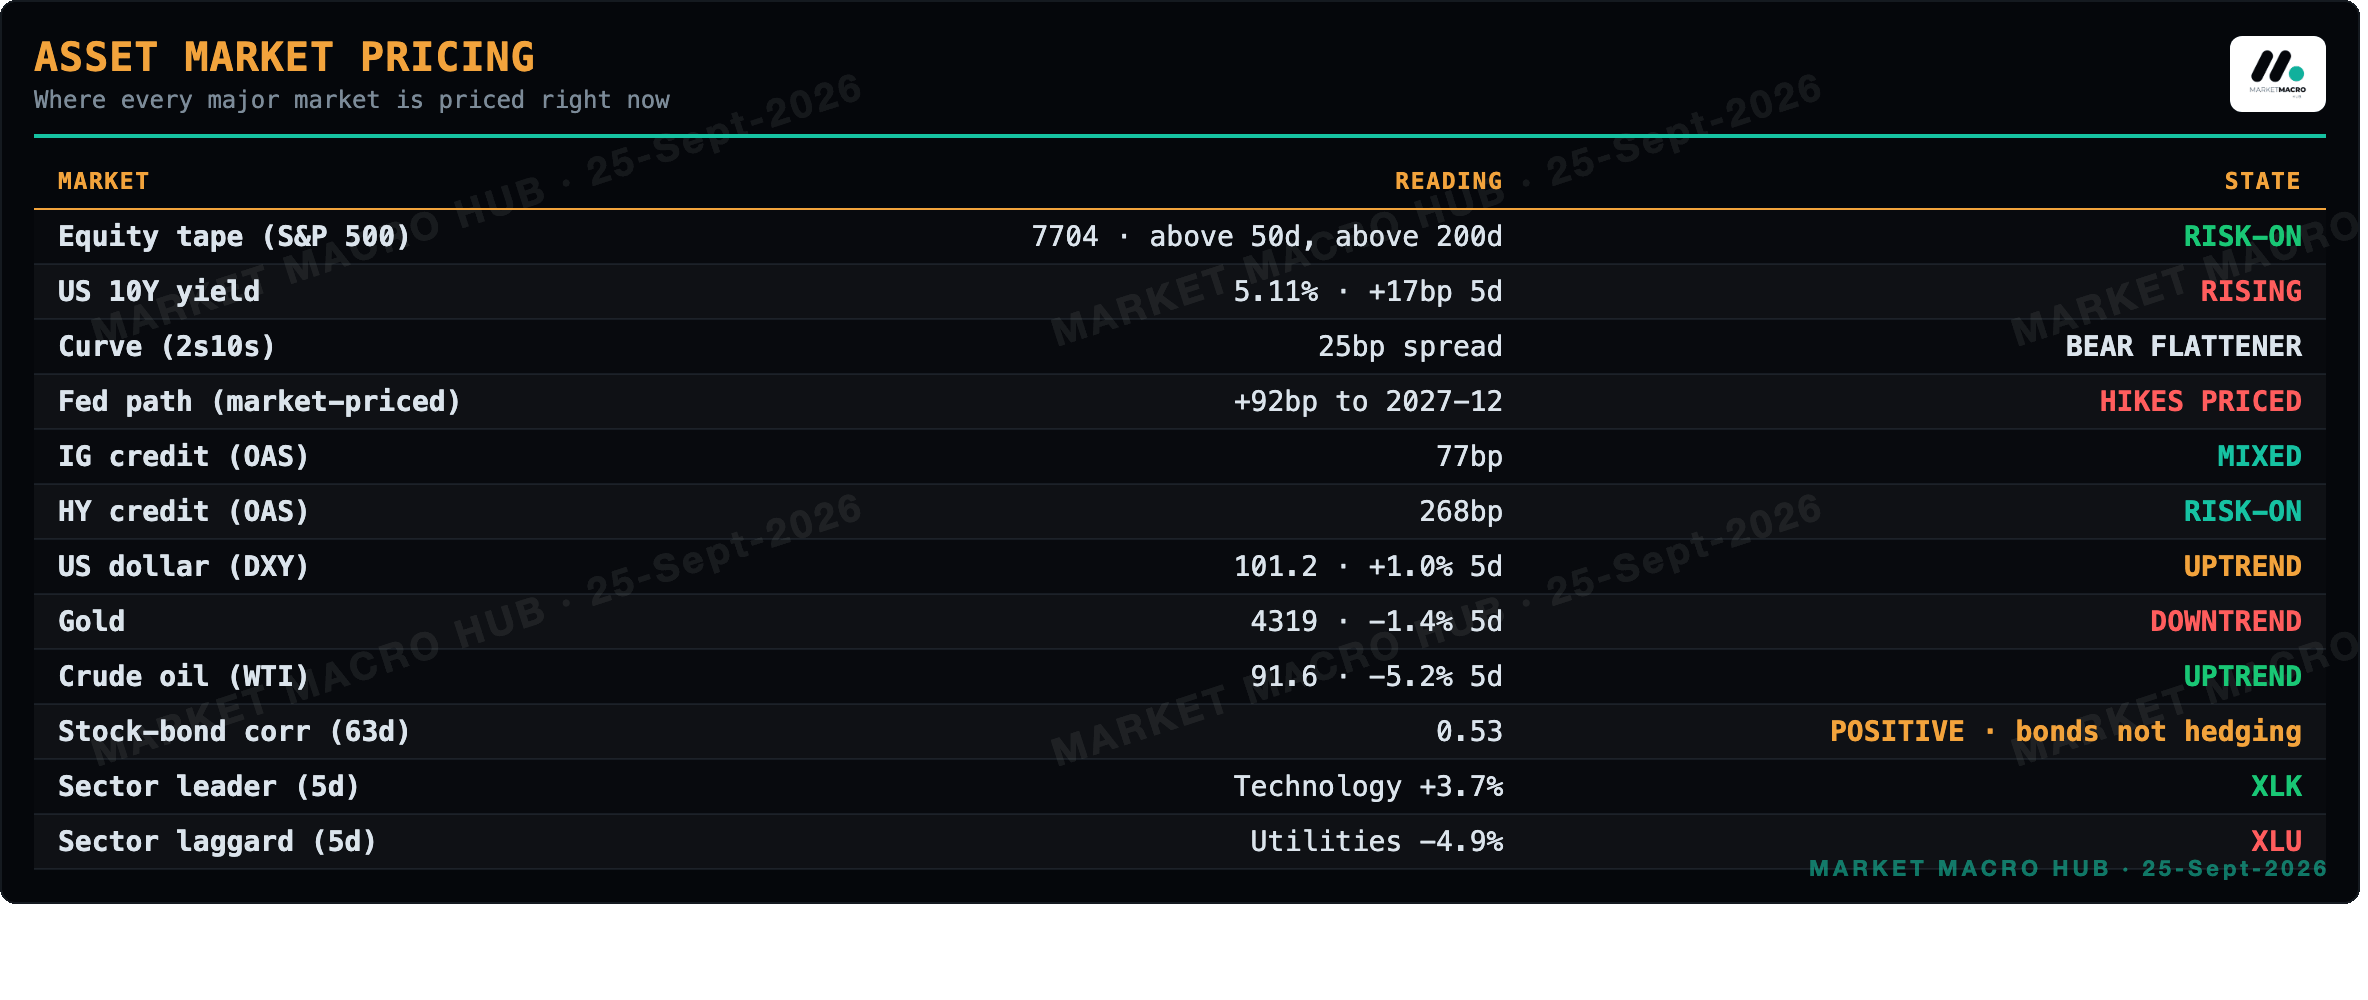
Long the hike story into November at 70%, no cut sits anywhere on the strip.
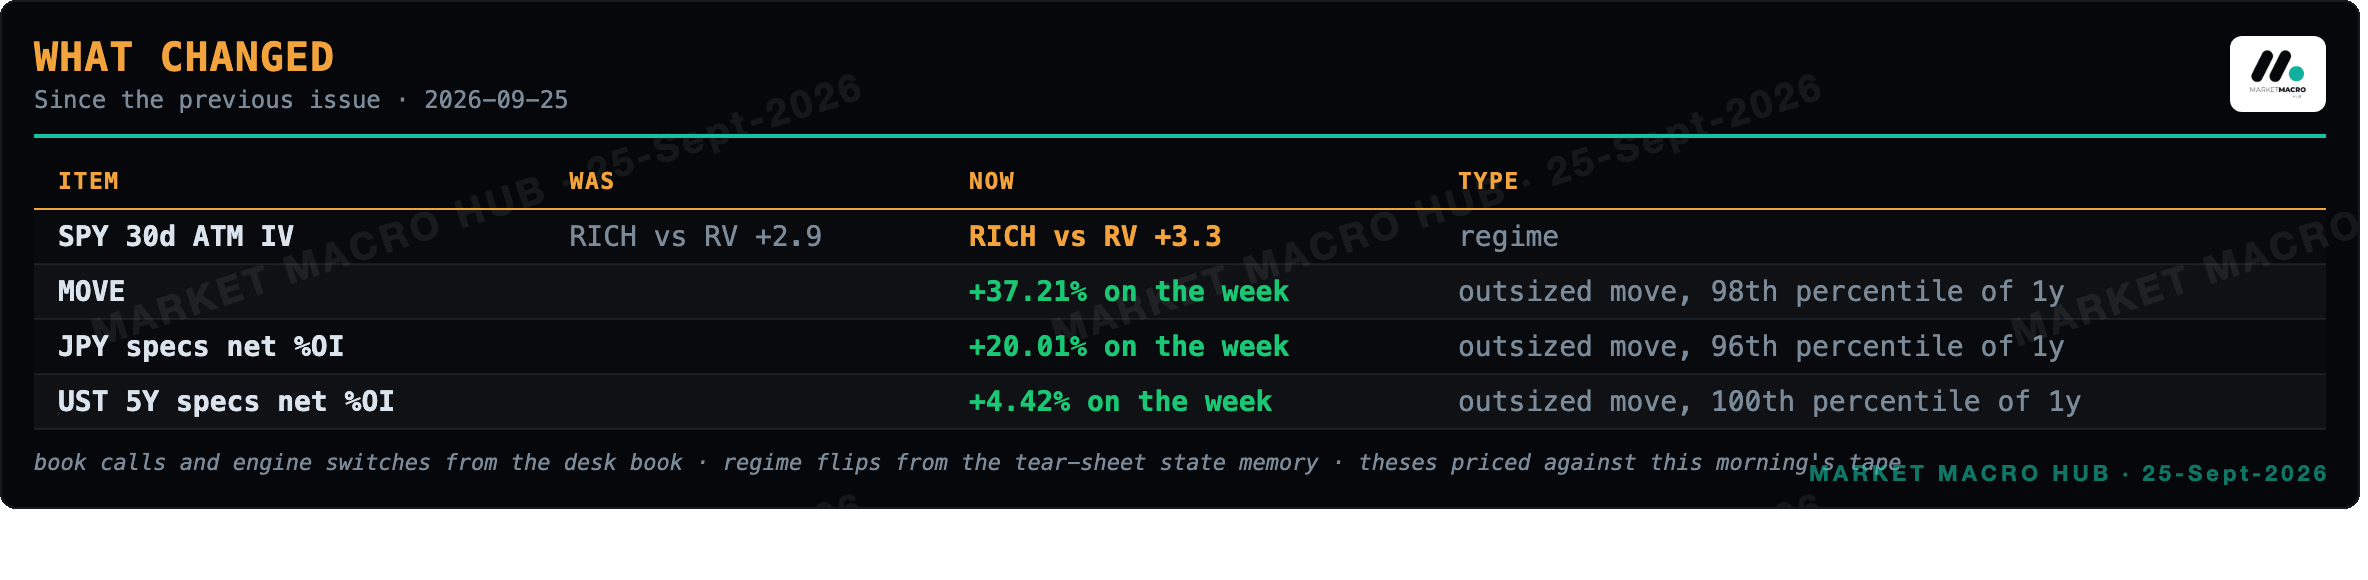
Rate vol is the tail, MOVE up +28.4 on the week while VIX stays calm, watching for the bleed.
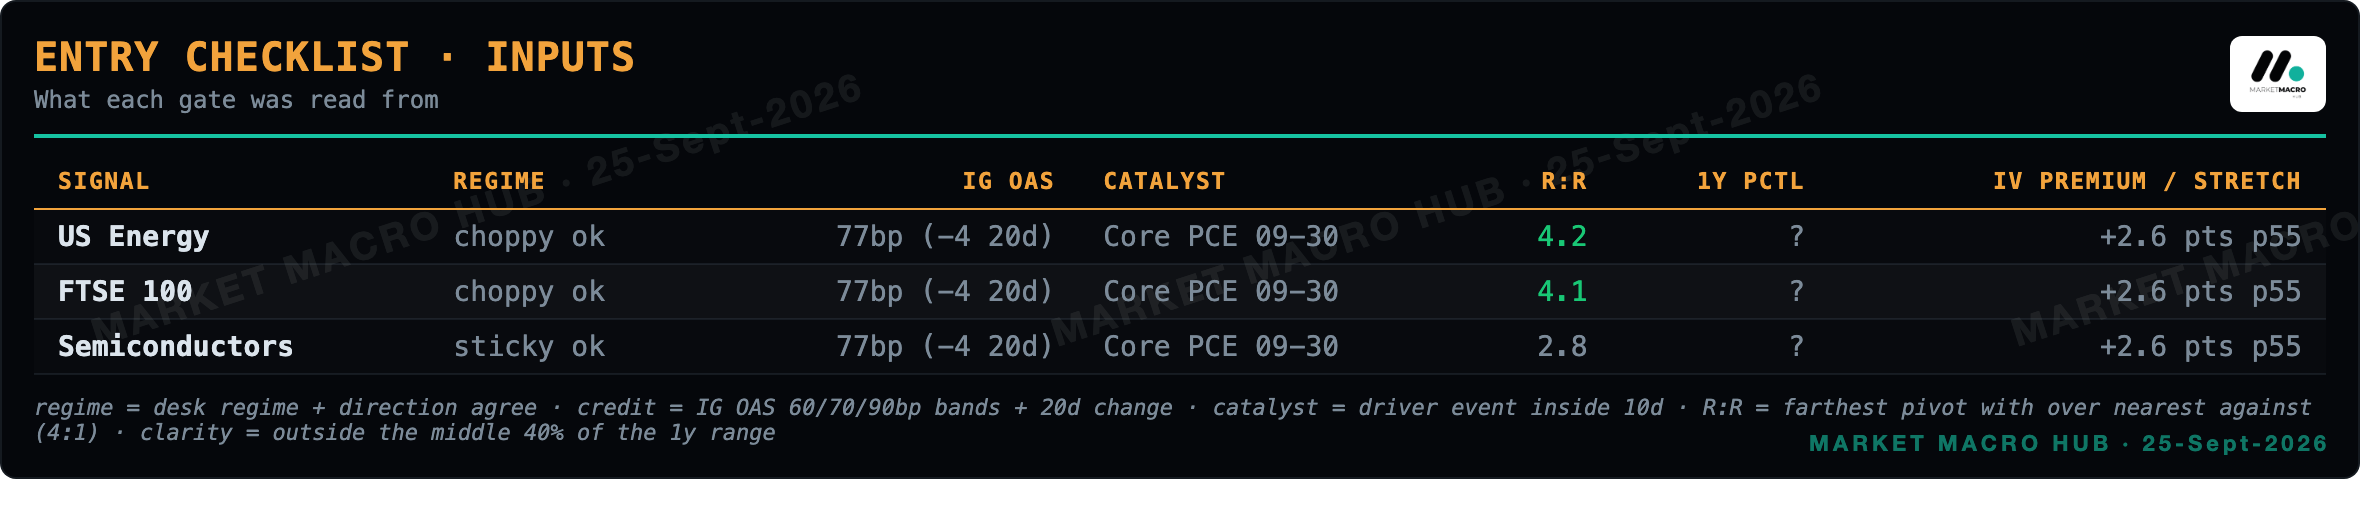
Credit anchors me, IG at 77bp flags no stress, invalidation 90bp.
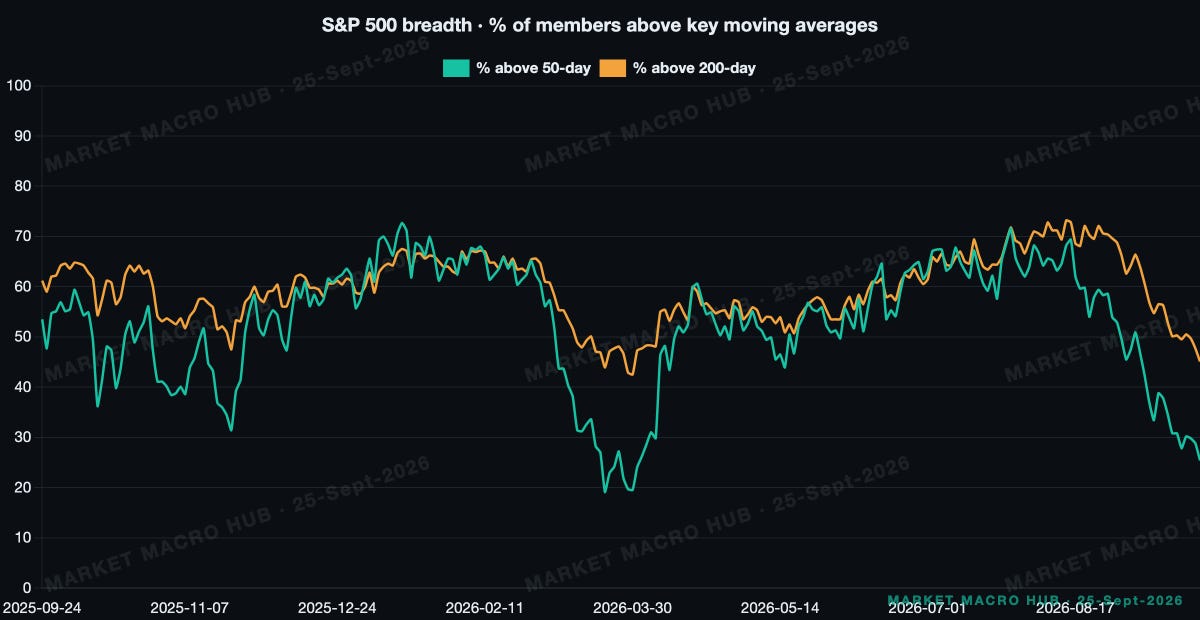
SPX book gated at 76, narrow breadth keeps me off the tape either way.
2s10s at 25bp decides my Fed-path doubt, more steepening says the strip overshot.
Where We Stand
Yesterday I said rate vol was the tail and I was watching whether it bled into equity vol. This morning's tape backs that half up and undercuts the other half. MOVE jumped +9.1pts on the day and is up +28.4 on the week, yet VIX sits at the calm end of its range and dips keep getting bought. So the tail is fatter, but the contagion has NOT come. I'm keeping the SPX book gated at 76, narrow breadth still stops me chasing.
On my oldest live thesis, IG credit anchored since the 21st, nothing has changed. IG holds at 77bp, the tight end of its own range, credit is not corroborating any equity anxiety. Invalidation stays 90bp. The 2s10s steepening thesis is live too and this morning helps it.
Today's Tear Sheets
The full daily pack is attached below · six PDFs generated from the same computed data set as this note:
Macro Regime · regime classifier, growth x inflation quadrant, curve regimes, cross-asset drivers, crisis phase, model state card, breadth, credit, vol term structure, liquidity, stock-bond correlation, housing
Fixed Income · UST complex, term premia, rate risk, auctions, global curves, Fed/ECB/BoE/BoJ implied policy paths, global 2Y and 10Y panels
Equities · index pages, daily attribution, relatives, vol suite, vol cone, gamma, global relatives, Mag7+ quant sheet, options surfaces
FX · majors dashboards, carry, correlations, COT positioning, crosses
Commodities · energy, metals, agriculture, COT crowding, term structure
Crypto · BTC ladders, ETH, macro correlations, ETF flow proxy

What Changed
What the Tape Is Arguing About
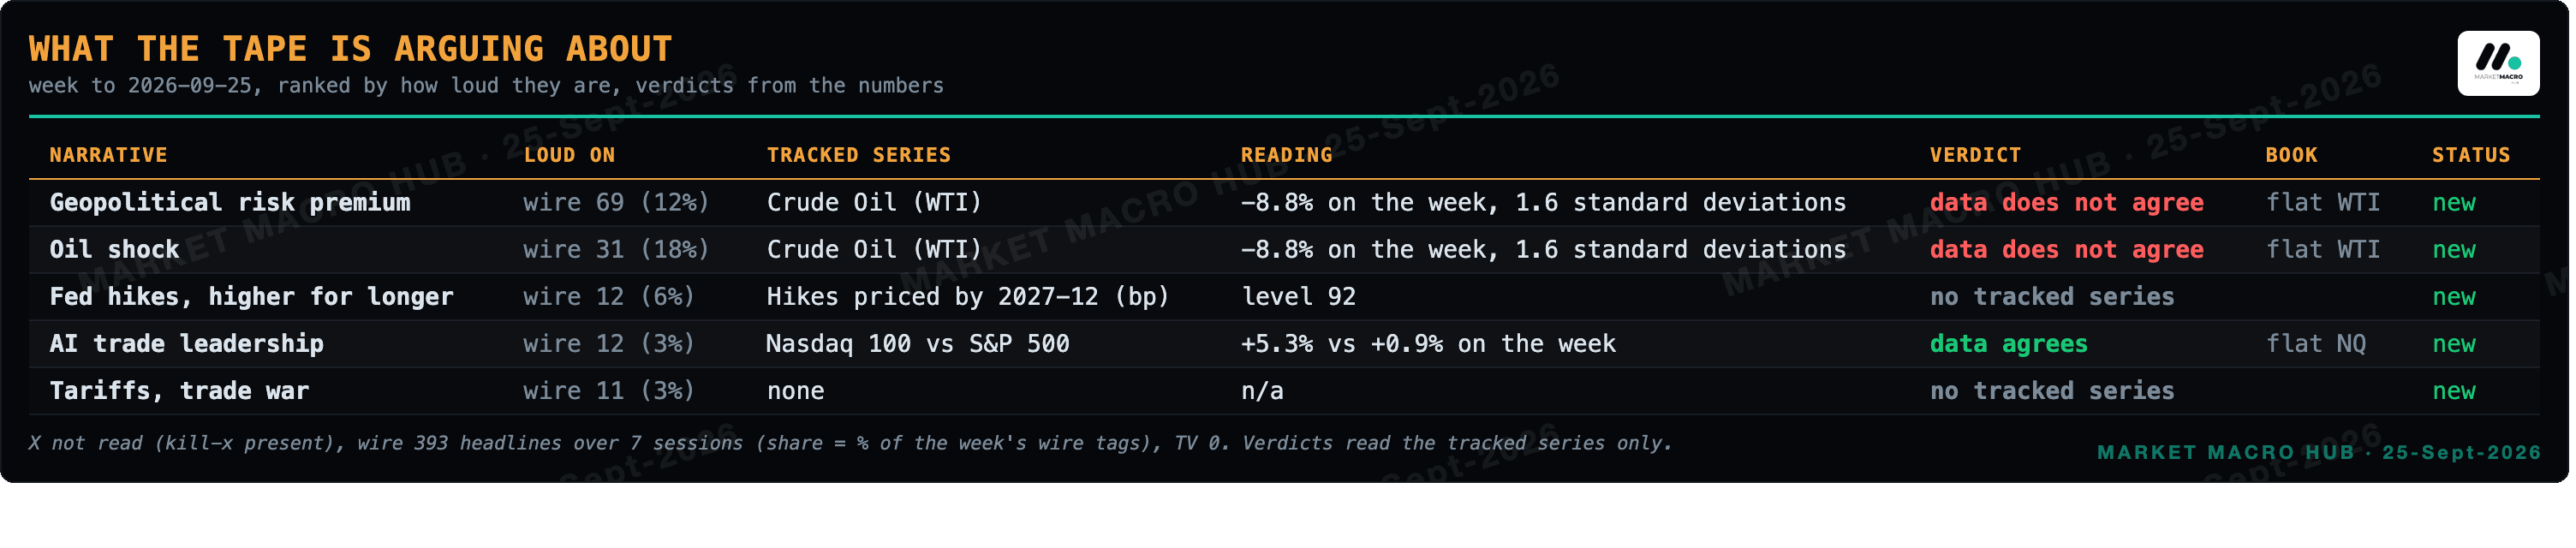
Geopolitical risk premium: data does not agree (Crude Oil (WTI) -8.8% on the week, 1.6 standard deviations).
Oil shock: data does not agree (Crude Oil (WTI) -8.8% on the week, 1.6 standard deviations).
Fed hikes, higher for longer: no tracked series.
AI trade leadership: data agrees (Nasdaq 100 +4.4% relative on the week).
Tariffs, trade war: no tracked series.
Asset Market Pricing
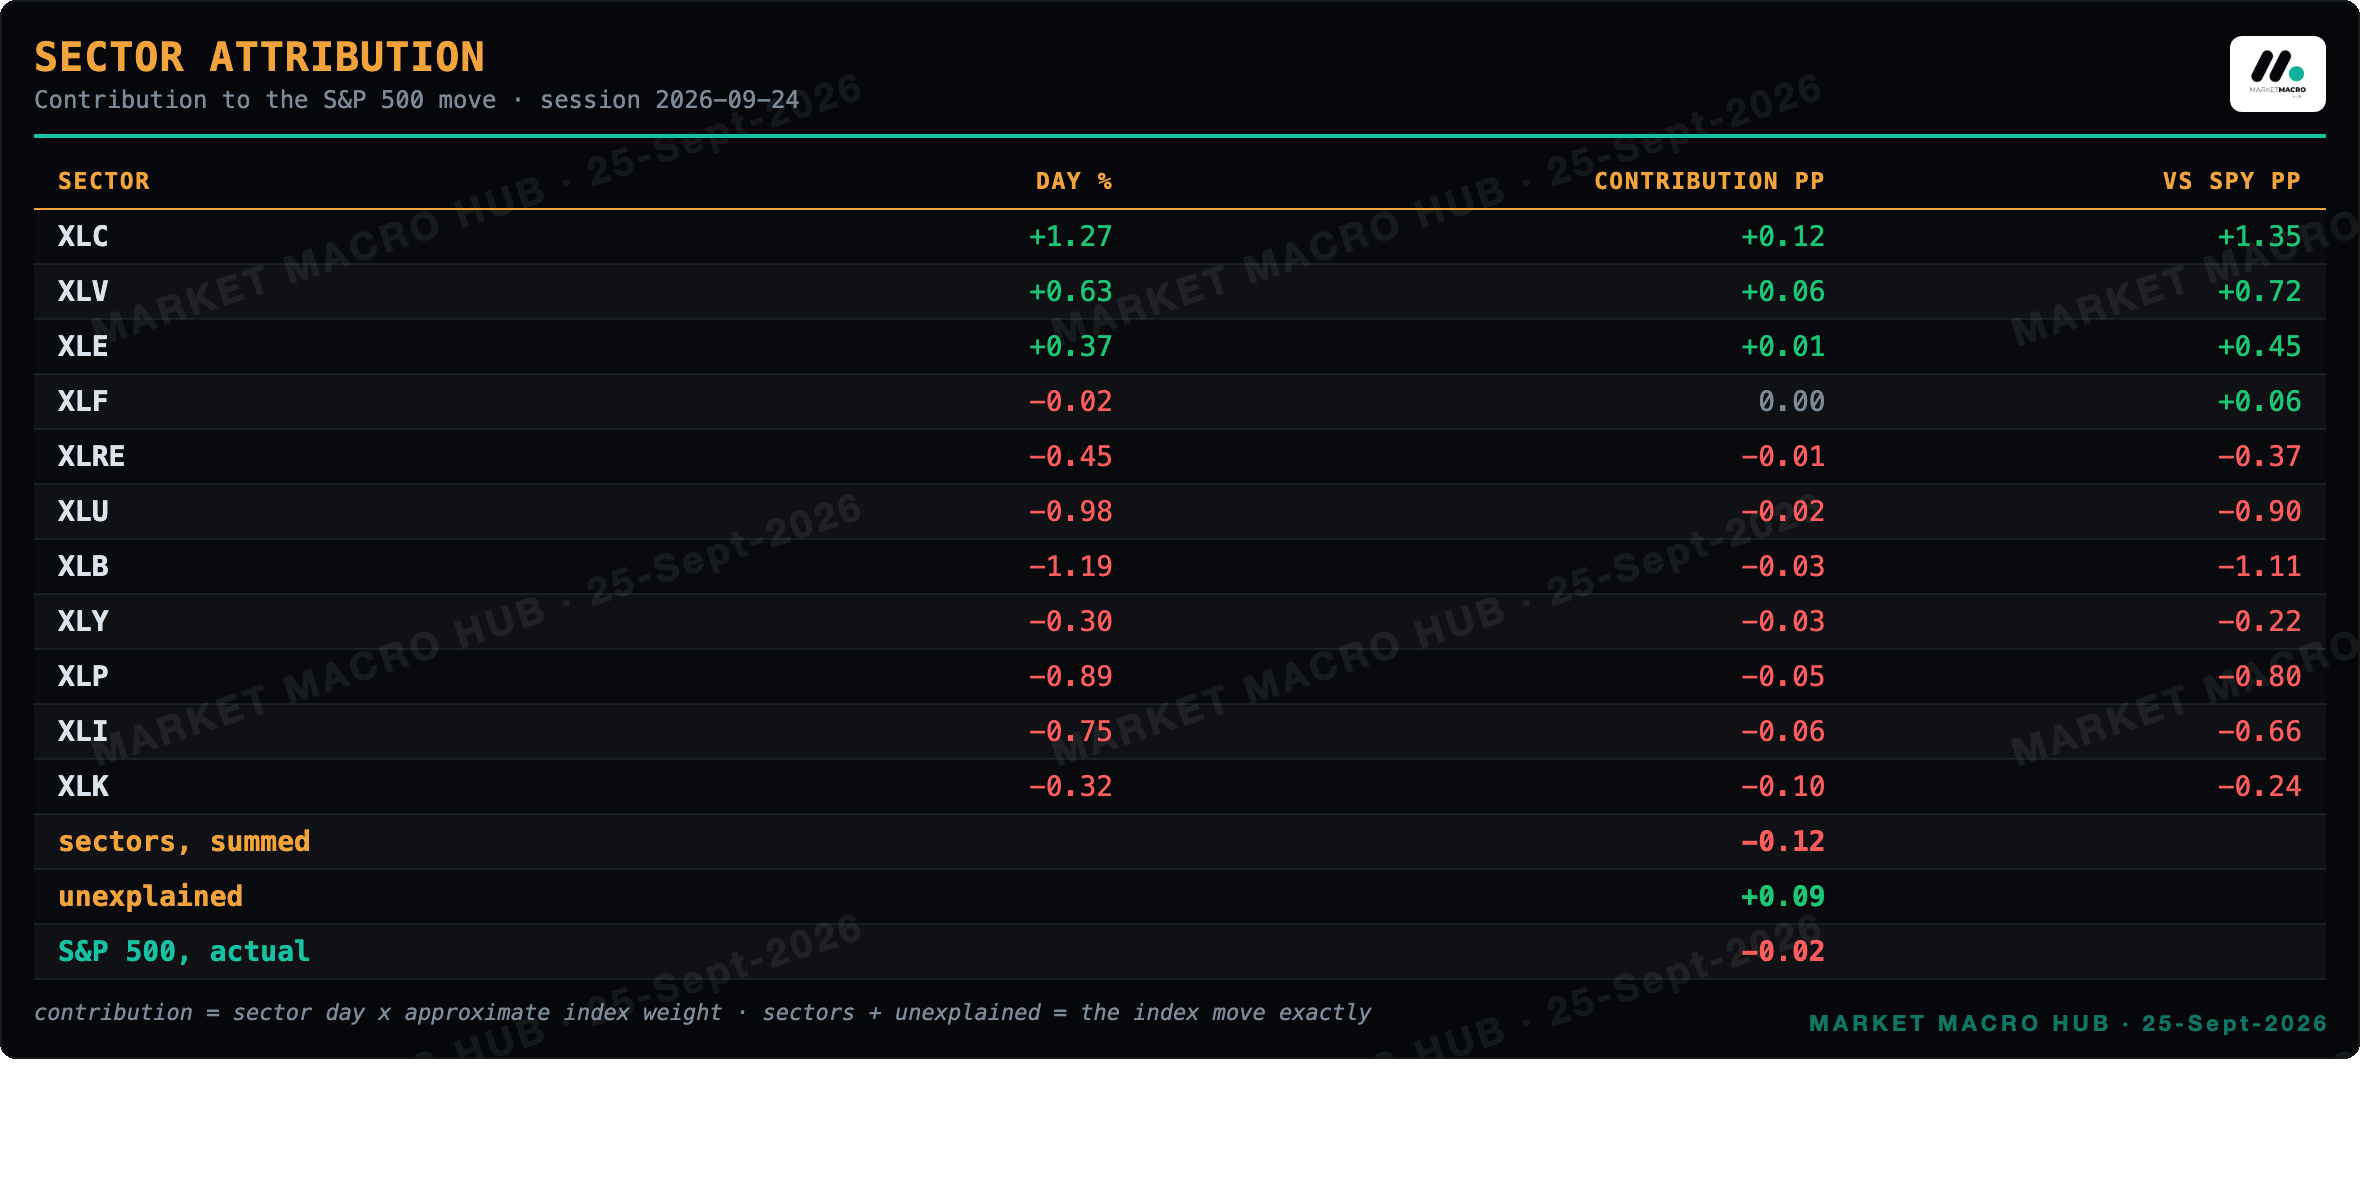
Sector Attribution
Session 2026-09-24. Sectors plus the unexplained remainder sum to the index move.
Attribution
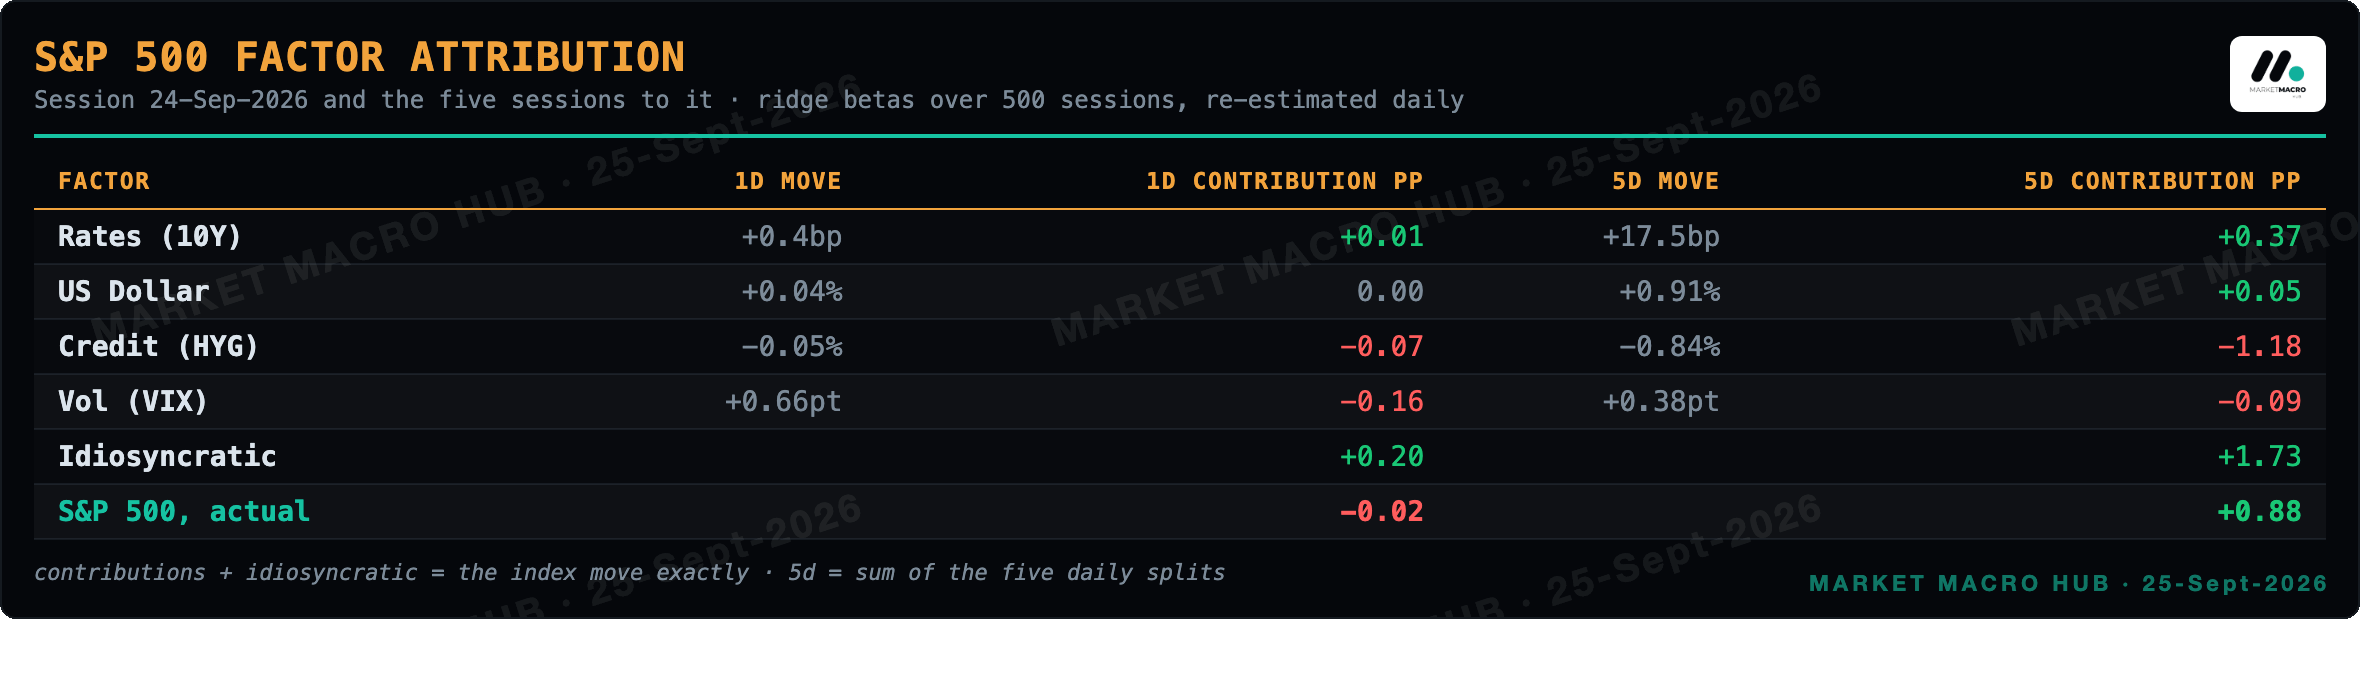
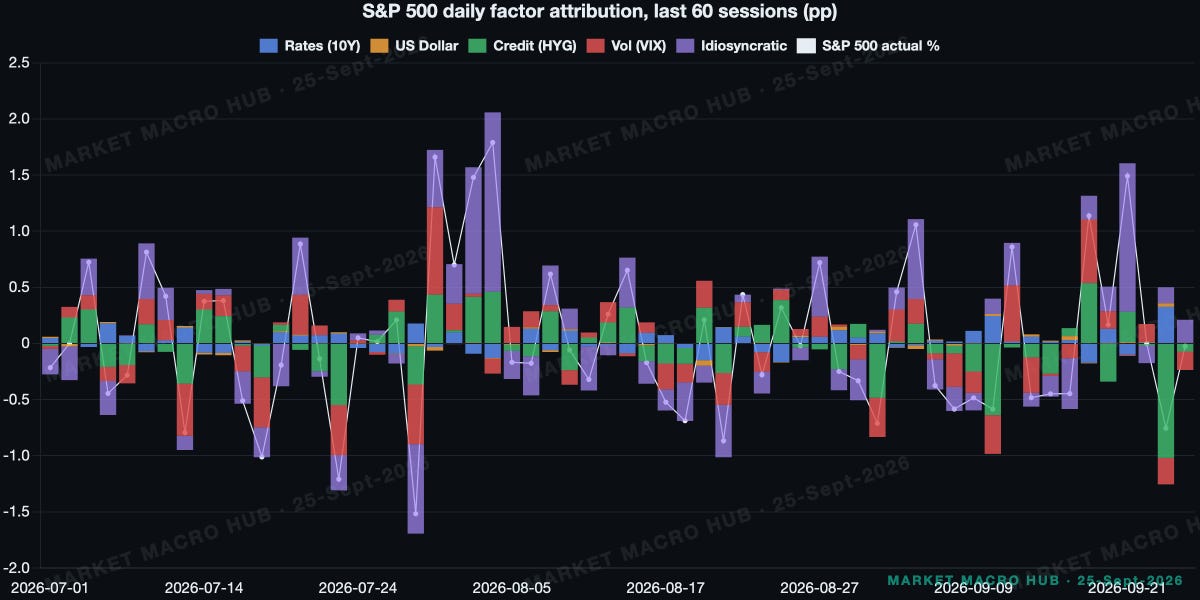
The S&P 500 closed -0.02% on 24-Sep-2026 and the largest driver was the idiosyncratic remainder at +0.20pp; over the five sessions to that close the index summed to +0.88% with the idiosyncratic remainder the largest driver at +1.73pp.
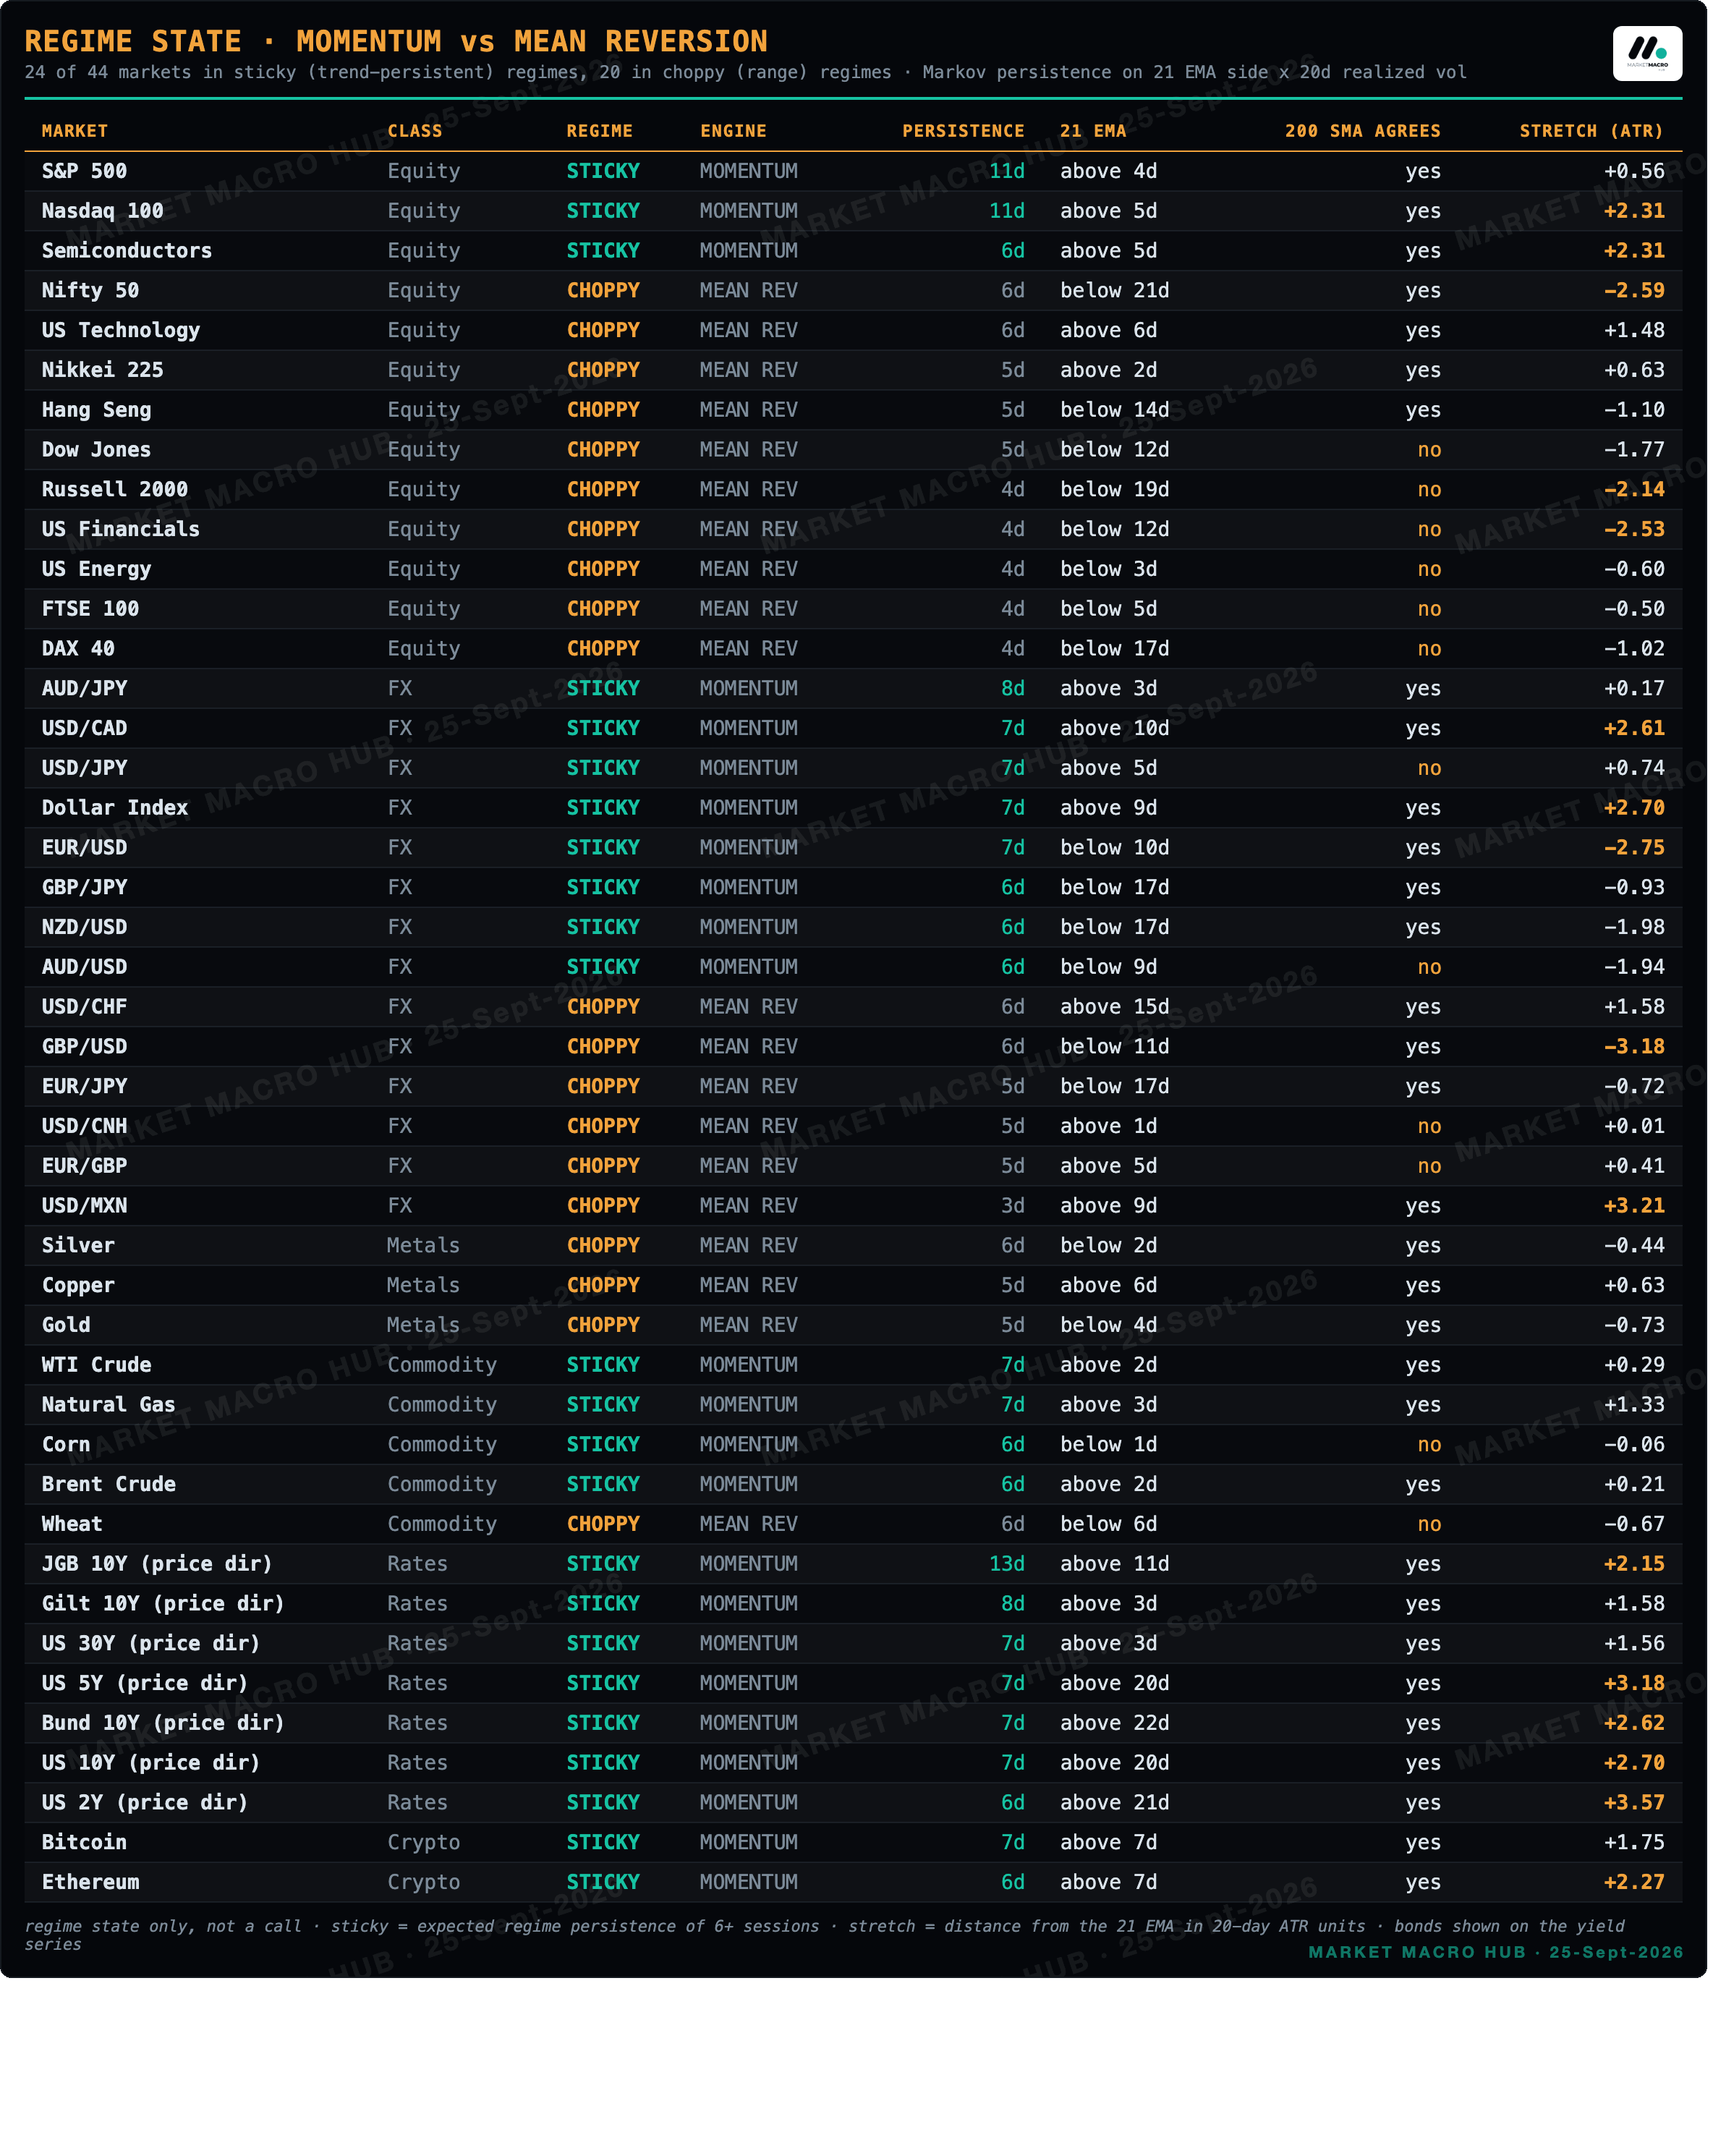
Regime State · Momentum vs Mean Reversion
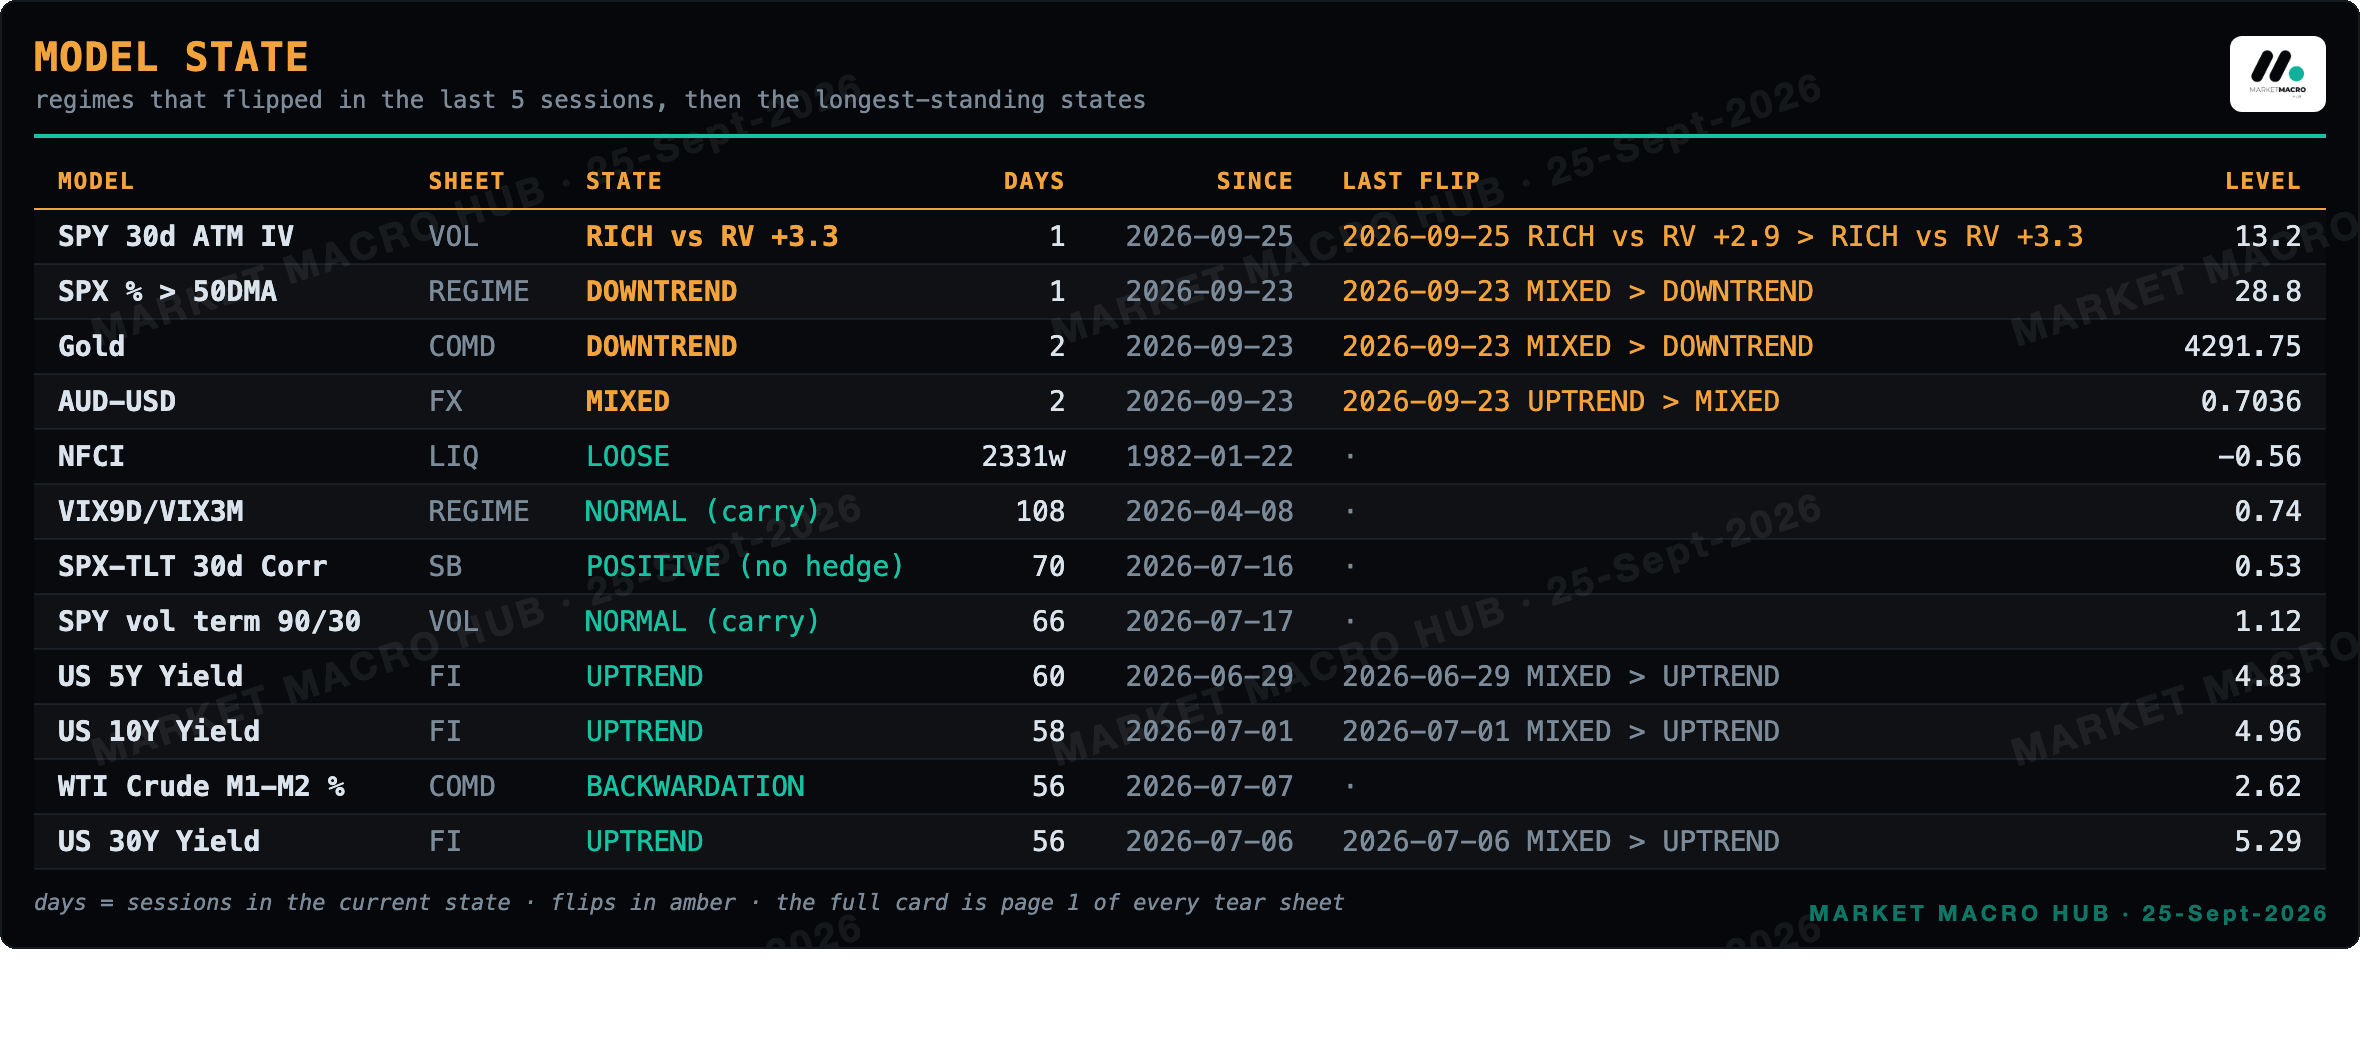
Model State
4 model states flipped inside the last five sessions: SPY 30d ATM IV to RICH vs RV +3.3, SPX % > 50DMA to DOWNTREND, Gold to DOWNTREND, AUD-USD to MIXED.
Measured Books · E1 to E5
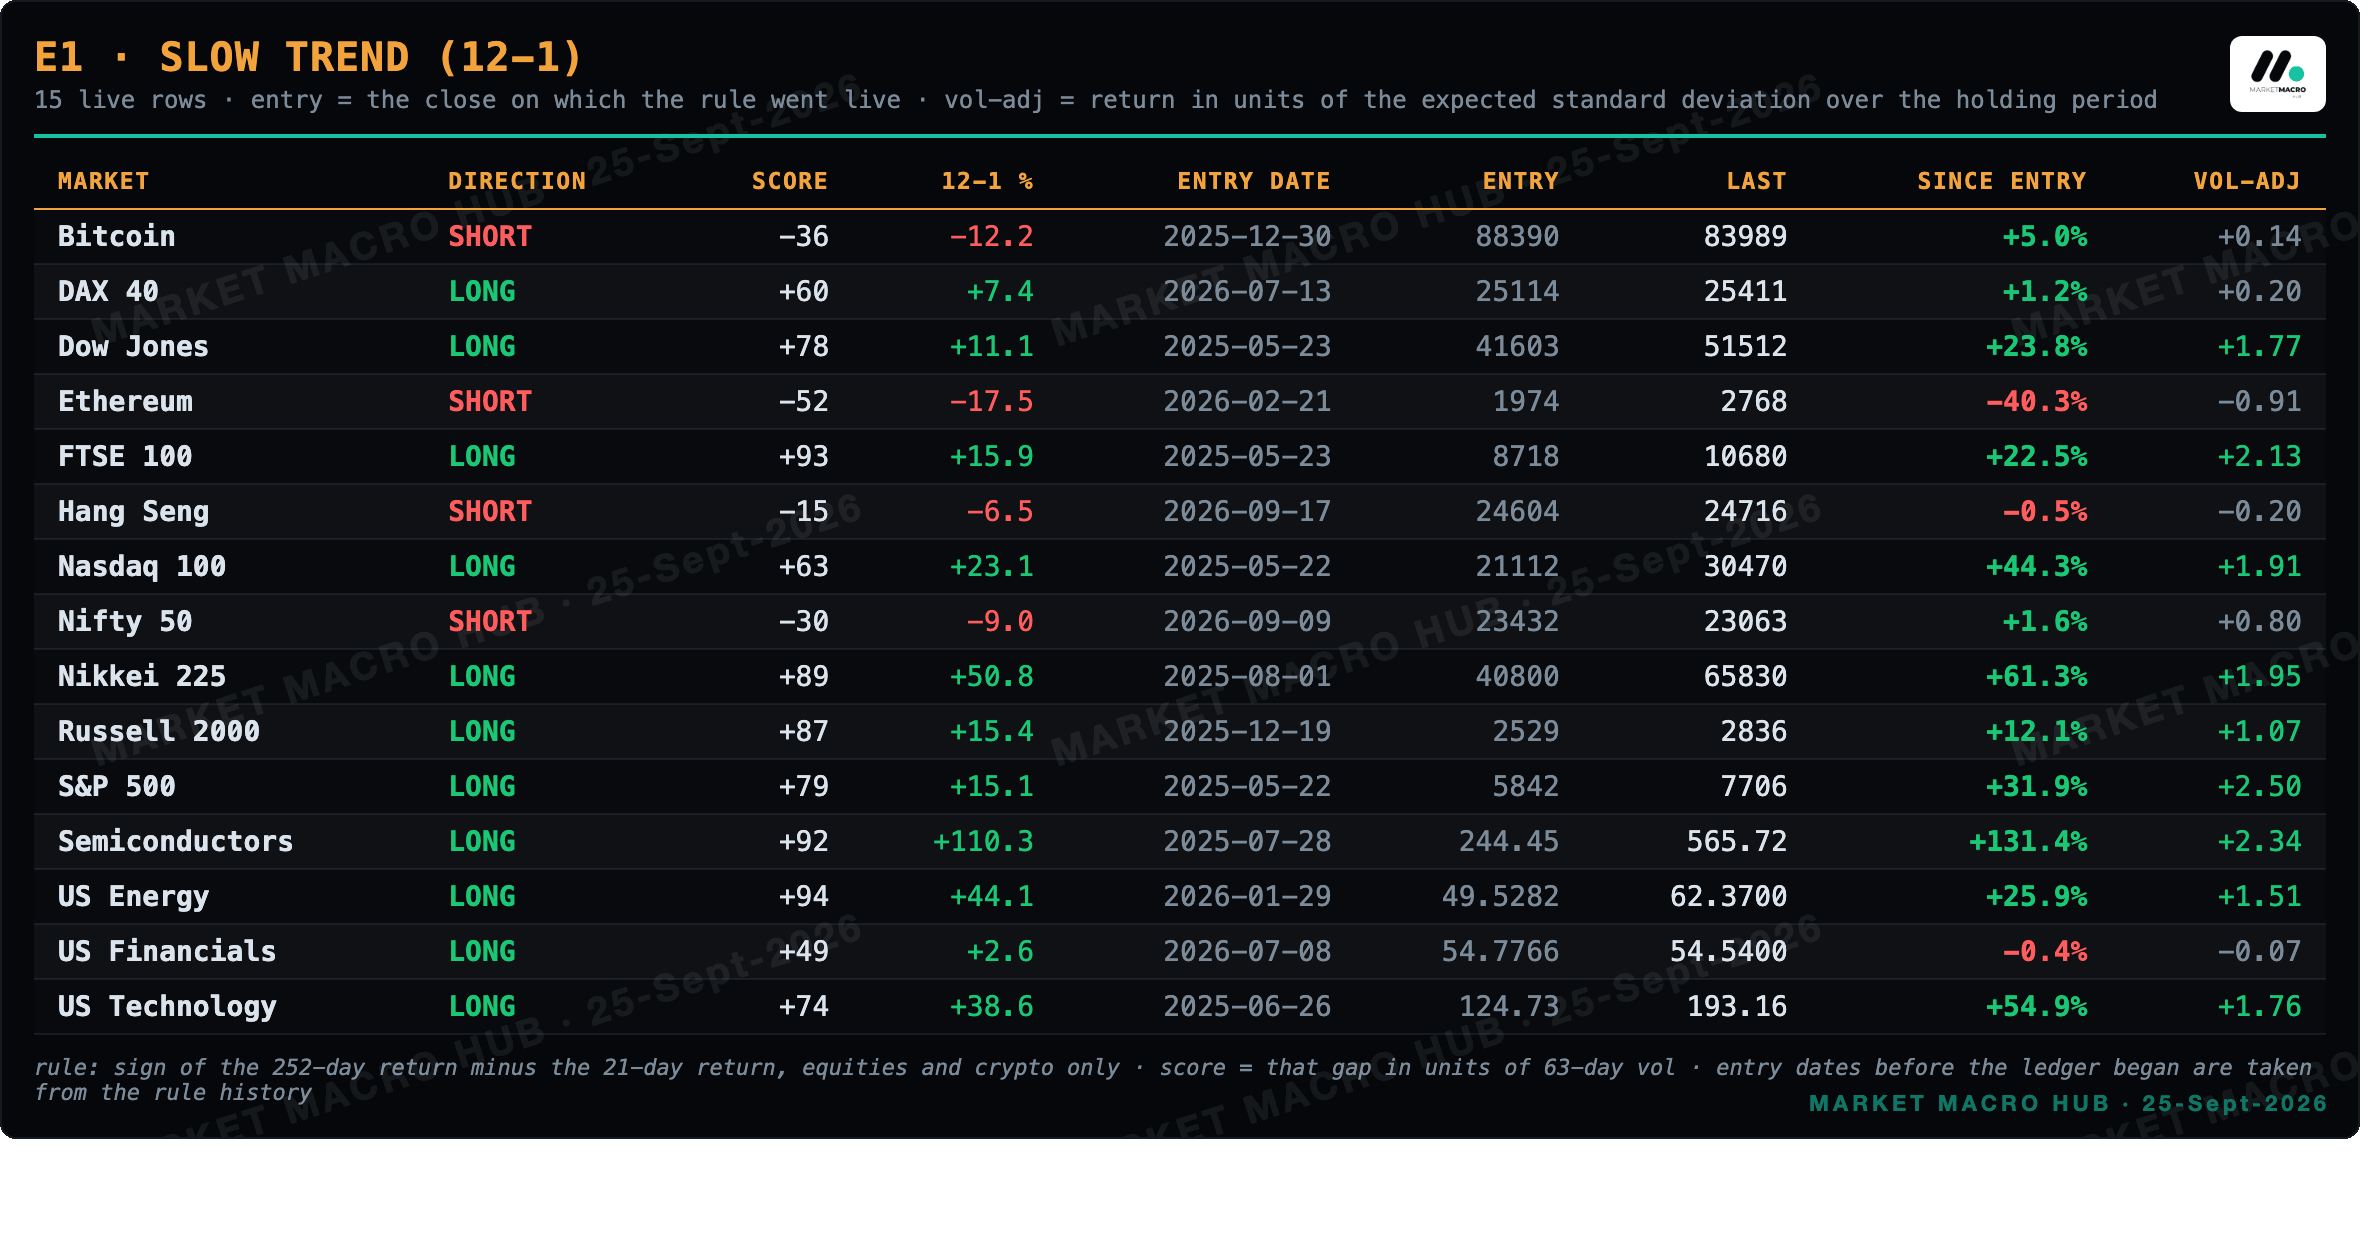
E1 since entry: 15 live rows, 12 positive, average +25.0%, median +1.51 vol-adjusted.
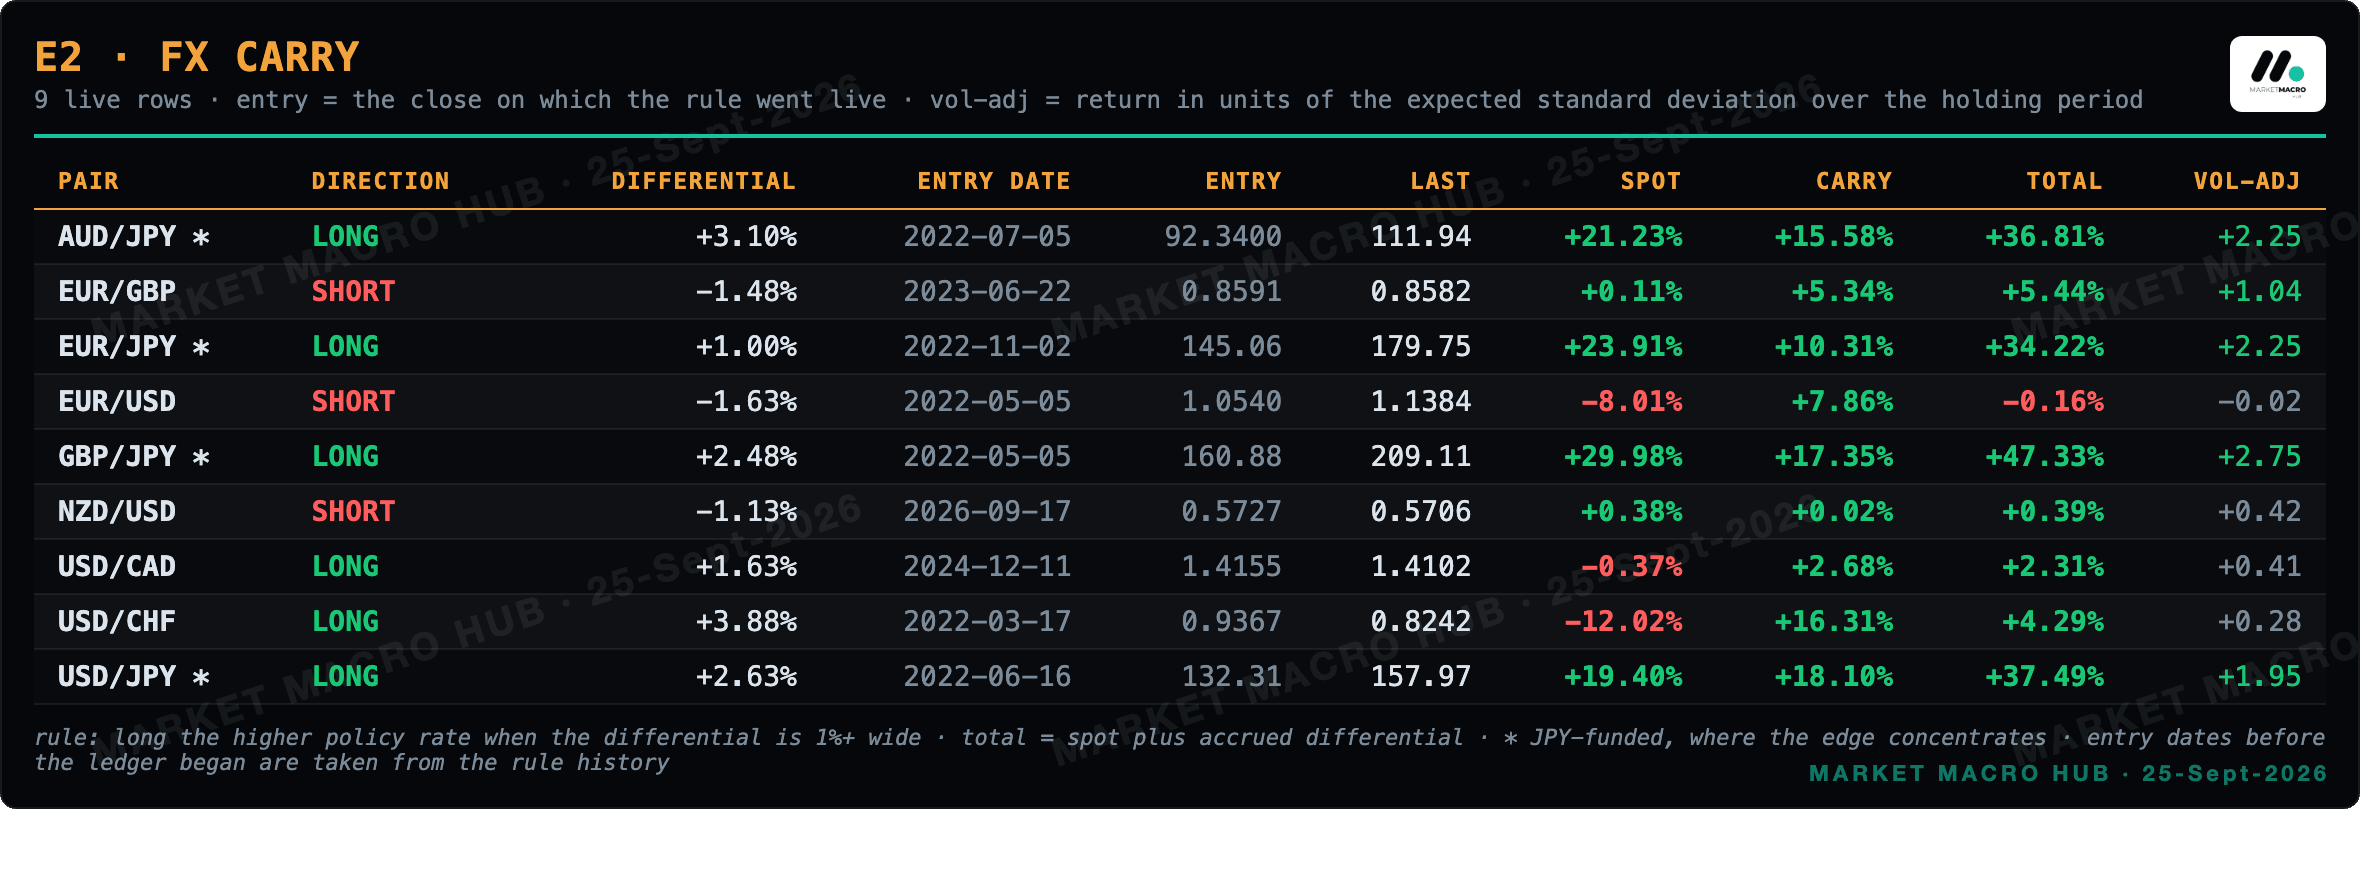
E2 since entry: 9 live rows, 8 positive, average +18.7%, median +1.04 vol-adjusted.
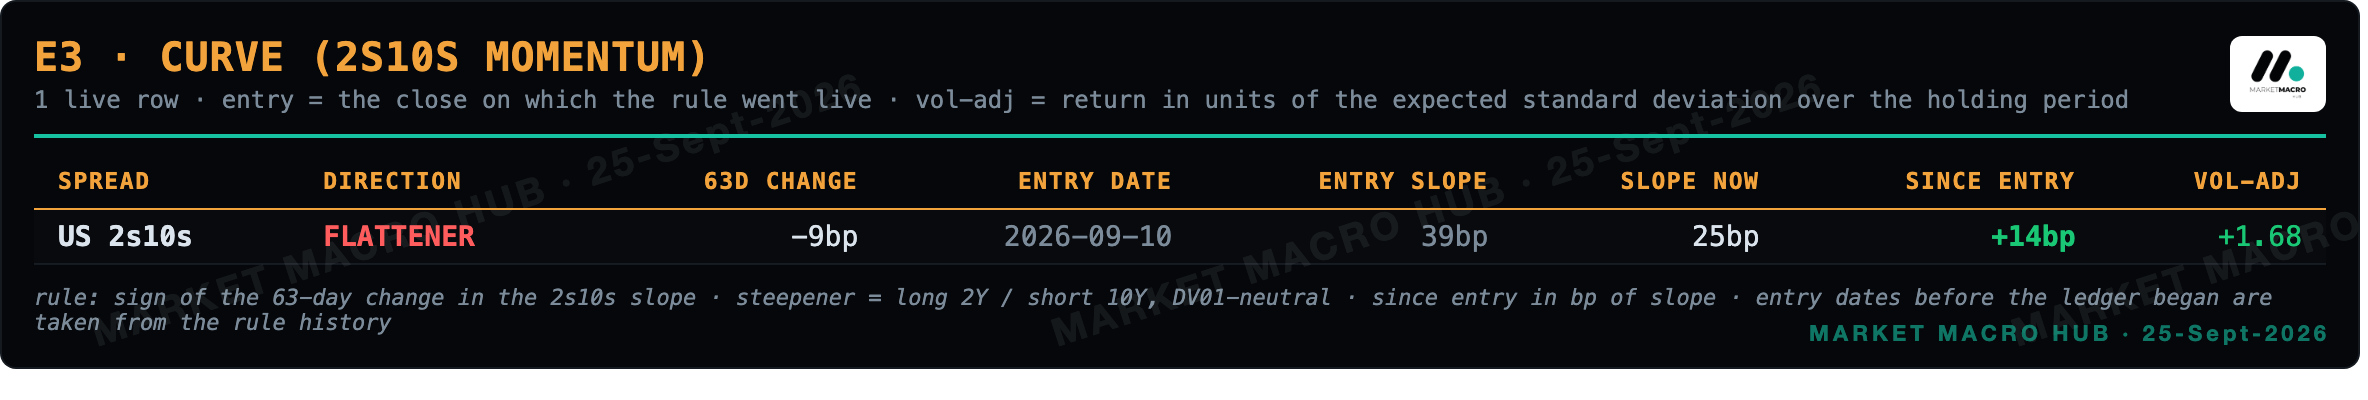
E3 since entry: SHORT US 2s10s from 2026-09-10, +14bp over 8 sessions (+1.68 vol-adjusted).
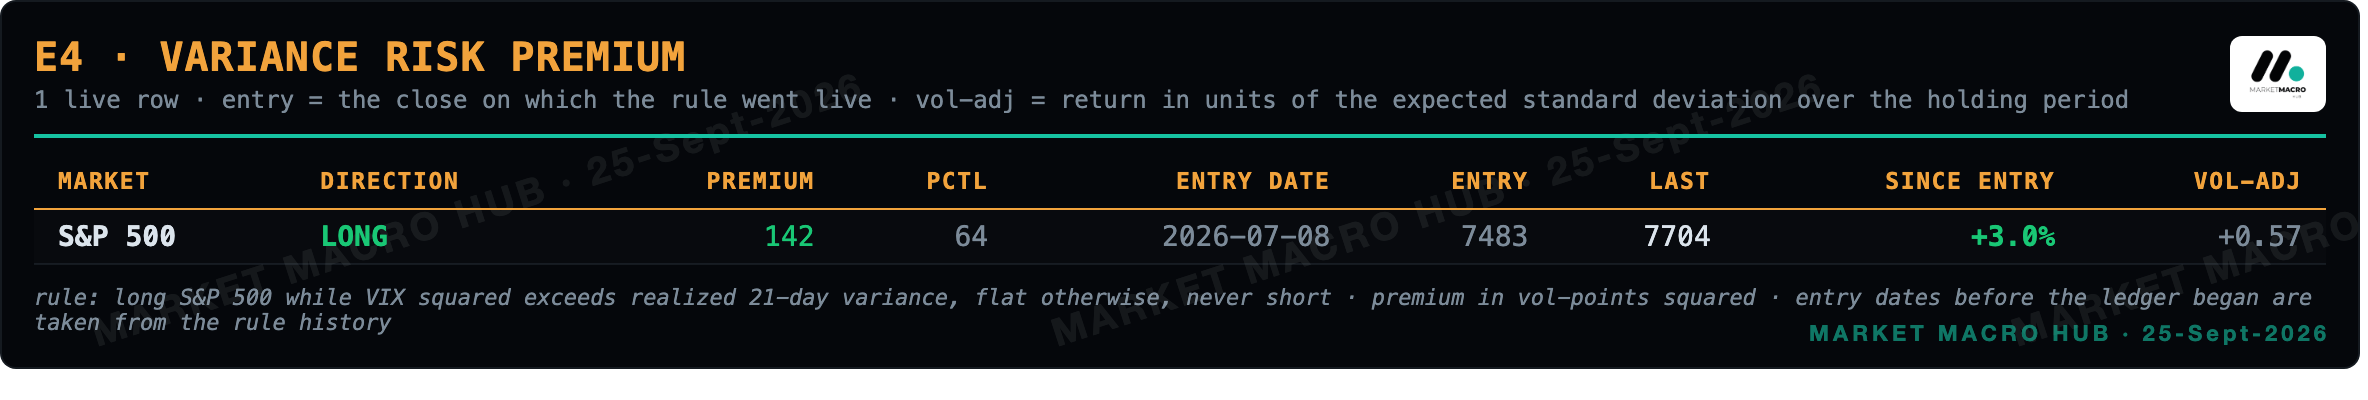
E4 since entry: LONG S&P 500 from 2026-07-08, +3.0% over 55 sessions (+0.57 vol-adjusted).
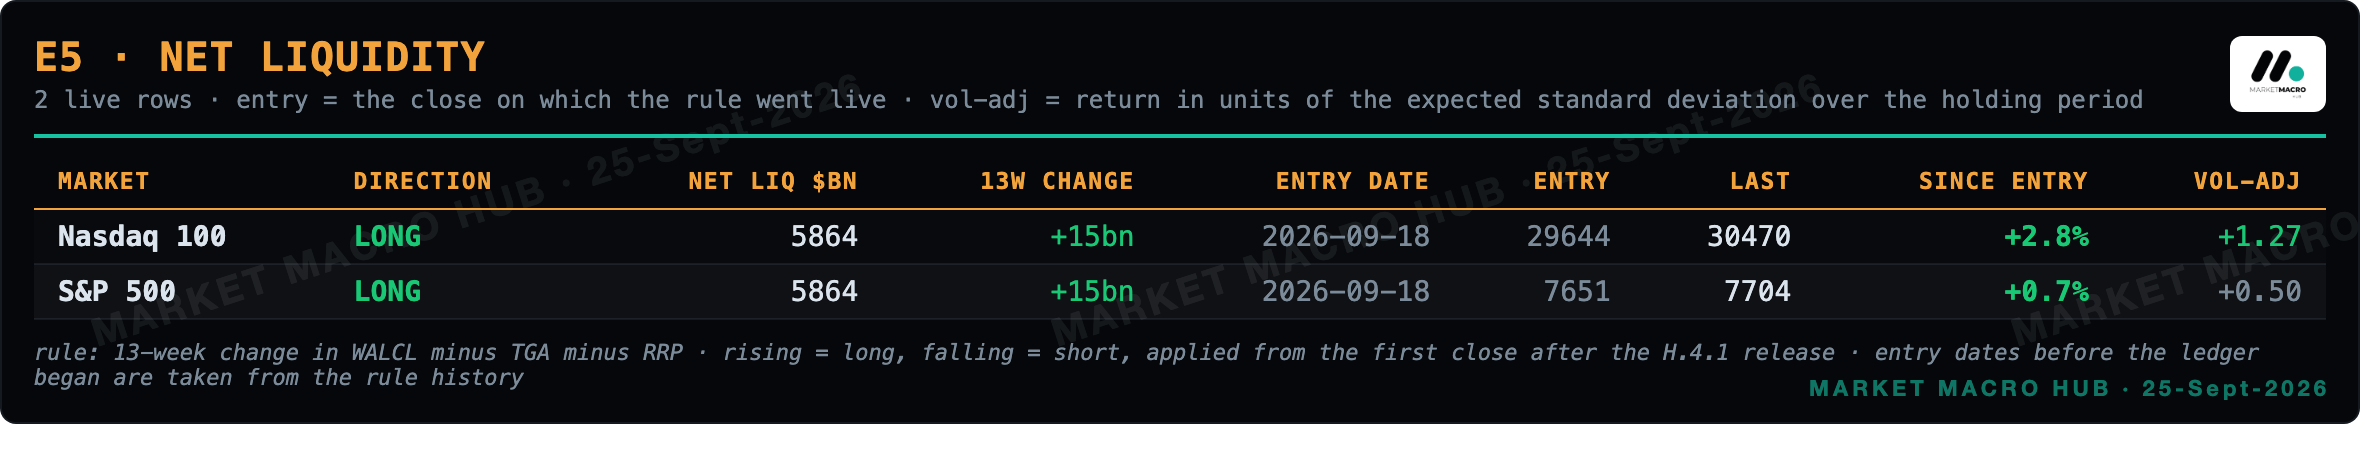
E5 since entry: 2 live rows, 2 positive, average +1.7%, median +1.27 vol-adjusted.
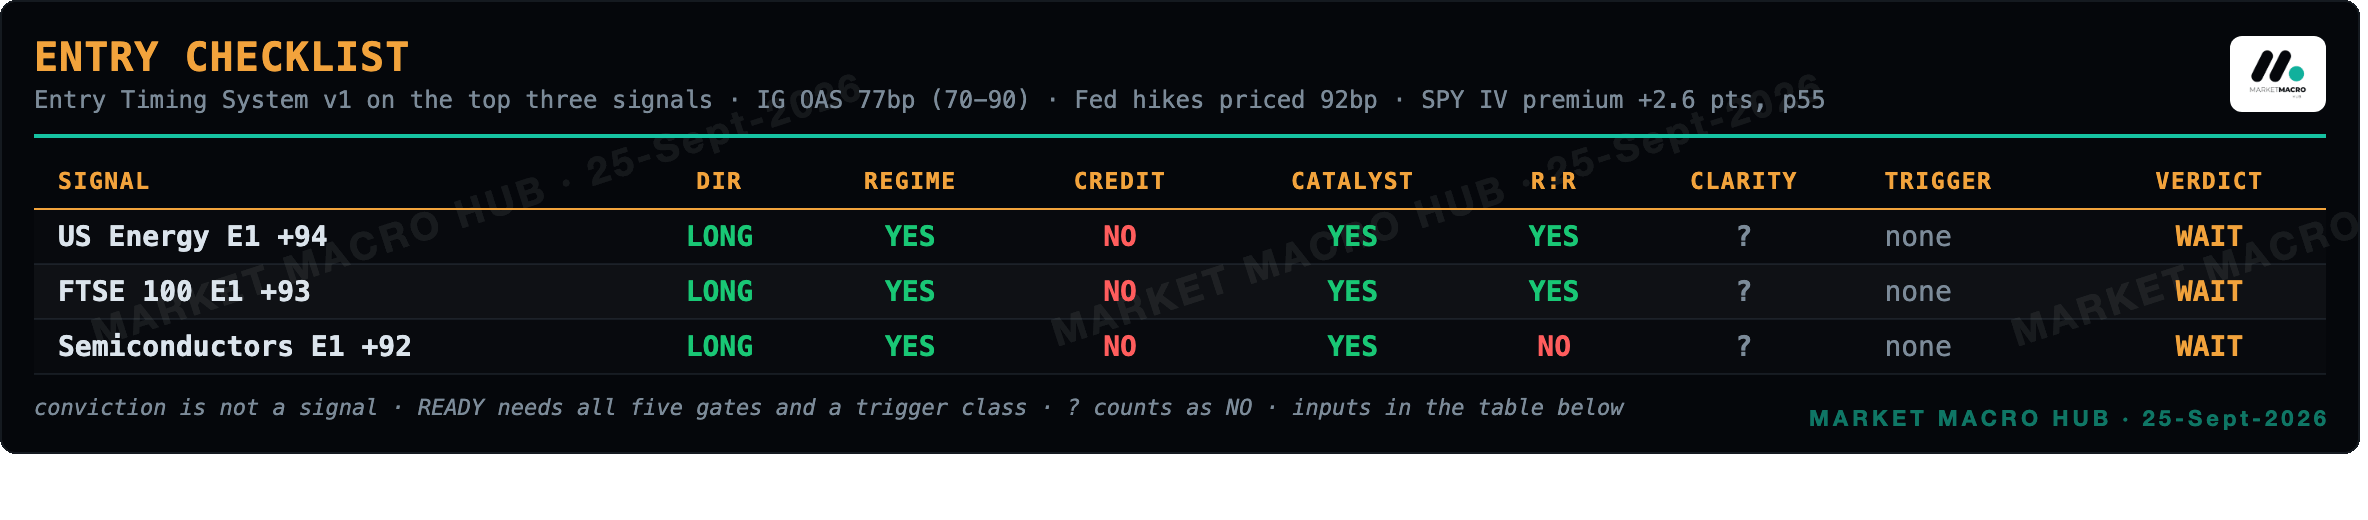
Entry Checklist
Sector Snapshot & Breadth
Stock-Bond Correlation
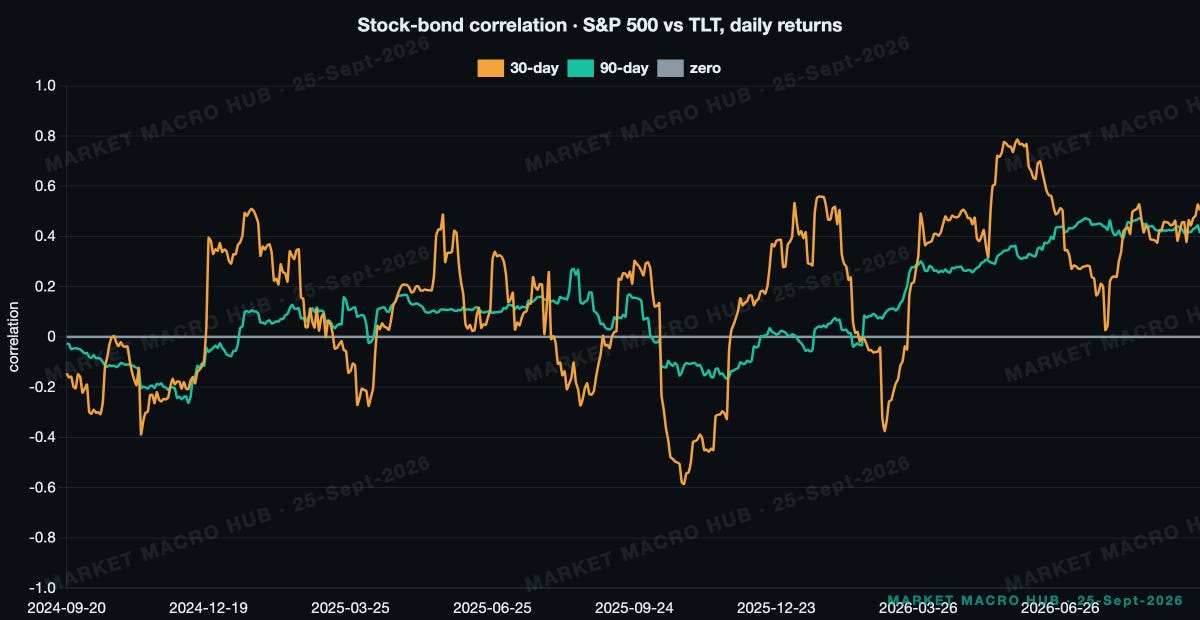
S&P 500 vs TLT, daily returns: 30-day 0.50, 90-day 0.41, positive, so bonds are not hedging equity risk.
Scenarios for the Week
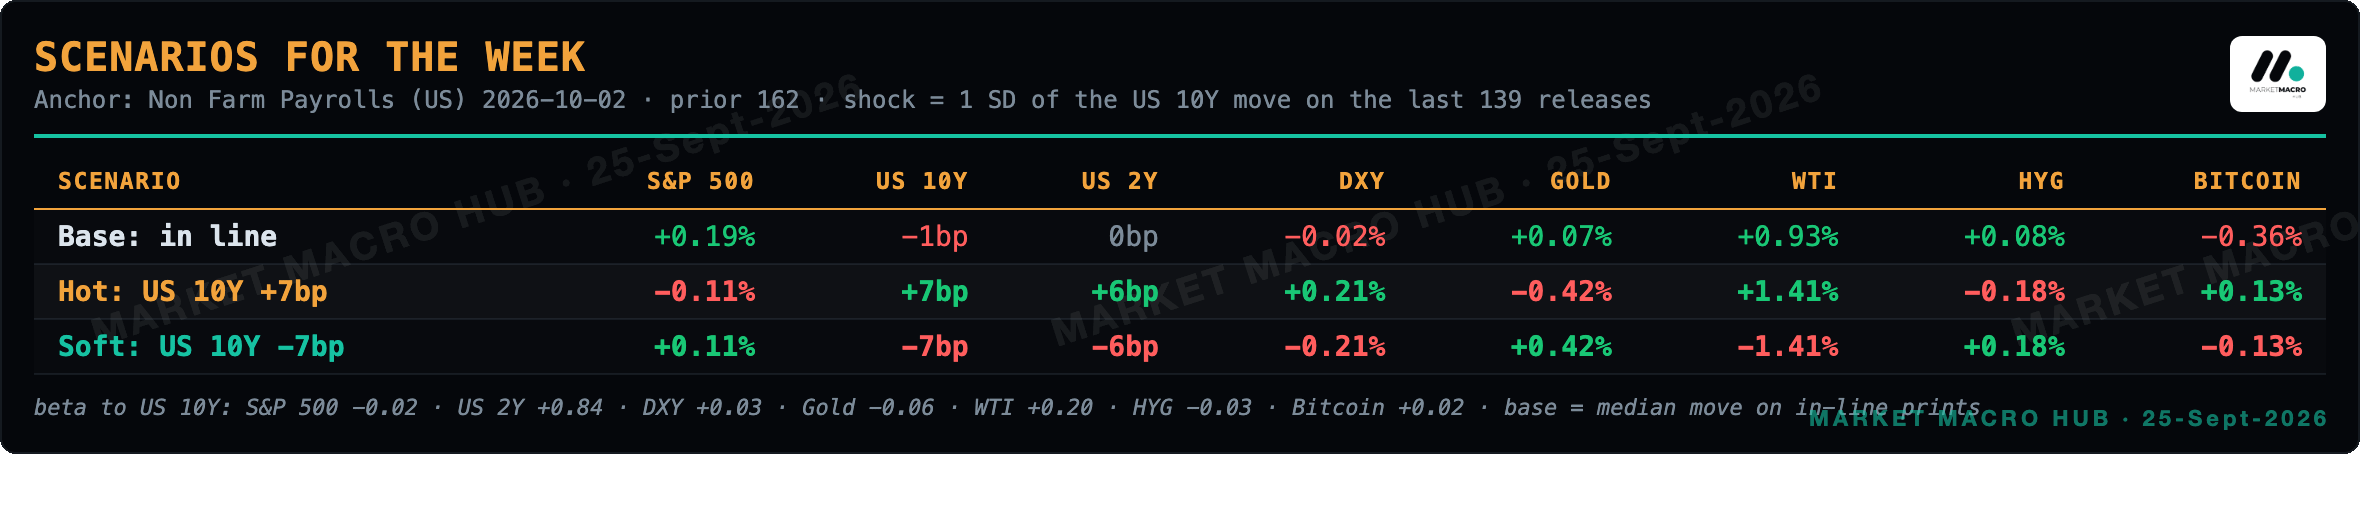
Expected moves are conditional means from 2-year betas to the anchor times a 1-standard-deviation event-day shock, not forecasts.
Release Playbook
Main Developments in Macro
US 10YR YIELD RISES TO HIGHEST SINCE 2007 NEAR 5.2% AS BOND ROUT DEEPENS
MONEY MARKETS NOW FULLY PRICE THREE FED HIKES OVER THE NEXT YEAR
US, IRAN REPORTEDLY DISCUSSED PHASED DEAL TO REOPEN STRAIT OF HORMUZ (REUTERS)
WTI AND BRENT SLIDE AS HORMUZ HEADLINES EASE SUPPLY FEARS
NIKKEI ABOVE 66,000, JAPAN 30YR YIELD HIGHEST SINCE 1999 DEBUT
DXY PAUSES AFTER FOUR STRAIGHT DAYS OF GAINS
BANXICO HOLDS AT 6.5%, UNANIMOUS
The bond rout is the whole story. The 10yr push came on rising oil, a weak auction, an underwhelming buyback and hawkish Fed speak, with three hikes now fully priced. Against that, the data leans soft in patches. New Home Sales came in at 0.684, above the 0.62 consensus, but Industrial Production printed 0% against a 0.3% consensus. Growth looks steady, so the strip is pricing inflation defence more than boom.
Cross-Asset Read
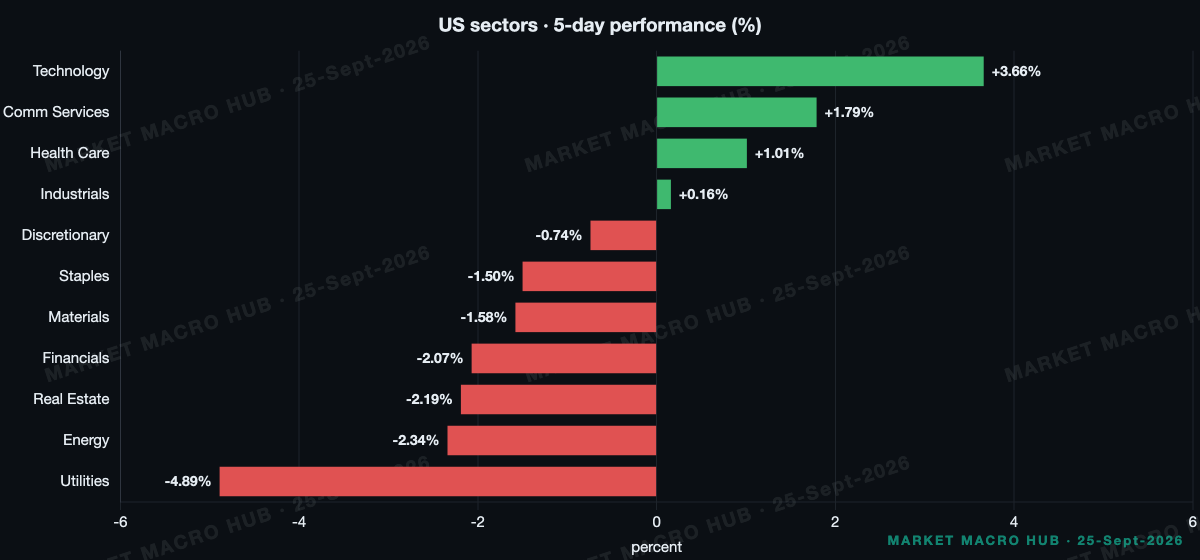
The tape yesterday was flat and choppy. Communication Services led with a +0.12pp contribution while tech dragged at -0.10pp, a wash of an index day where the sector split explained none of the move.
Two correlation shifts matter. Gold versus DXY has moved to -0.71 from -0.45, so gold is tracking the dollar more tightly than it was, which weakens gold as a dollar hedge here. SPX versus Bitcoin has jumped to 0.45 from 0.09, so Bitcoin is no longer the diversifier it was last month.
Credit stays my anchor. IG at 77bp sits at the tight end of its range against a 89bp mean, and HY at 268bp is priced as if default risk had been abolished. No stress signal there.
Rates & Fed Pricing
No cut is anywhere on this strip, so the question is purely how far the hikes go. November is the first month with a hike at least half-priced, around 70% odds, and December carries a hike at near 100%. The strip peaks in December 2027 at 4.8%, +91.5bp cumulative over the current 3.88% effective.
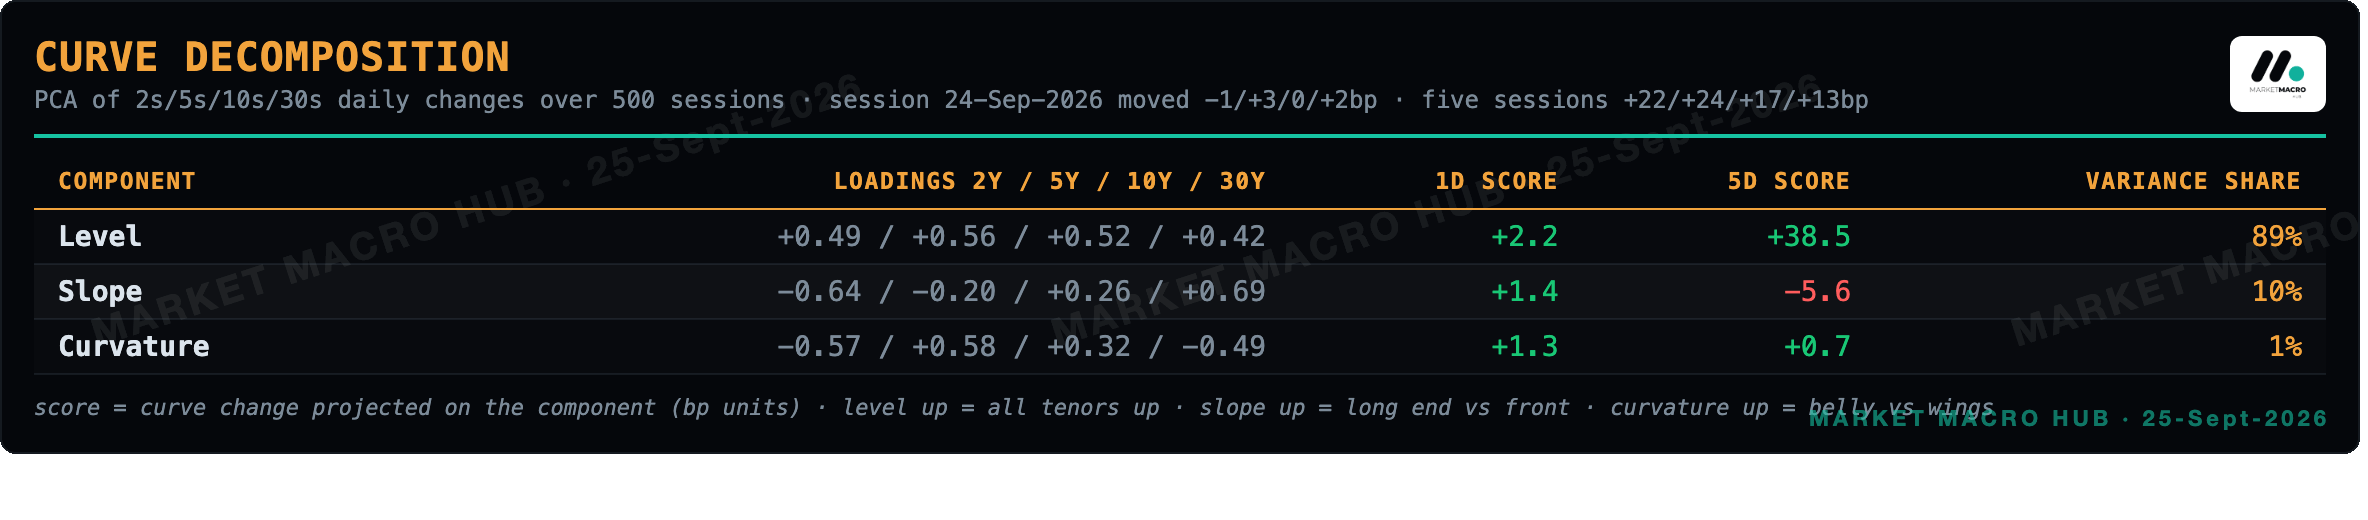
The repricing this week is the real move. Terminal came +116bp on the week, driven by oil, the auction and hawkish speak. I said it before and I'll say it again, I can't see three hikes being realised. The 2s10s is my tell. It steepened +5bp on the day to 25bp, which is the long-end doubting the front-end has this right. Sustained steepening changes my mind that the strip has overshot.
The Week Ahead
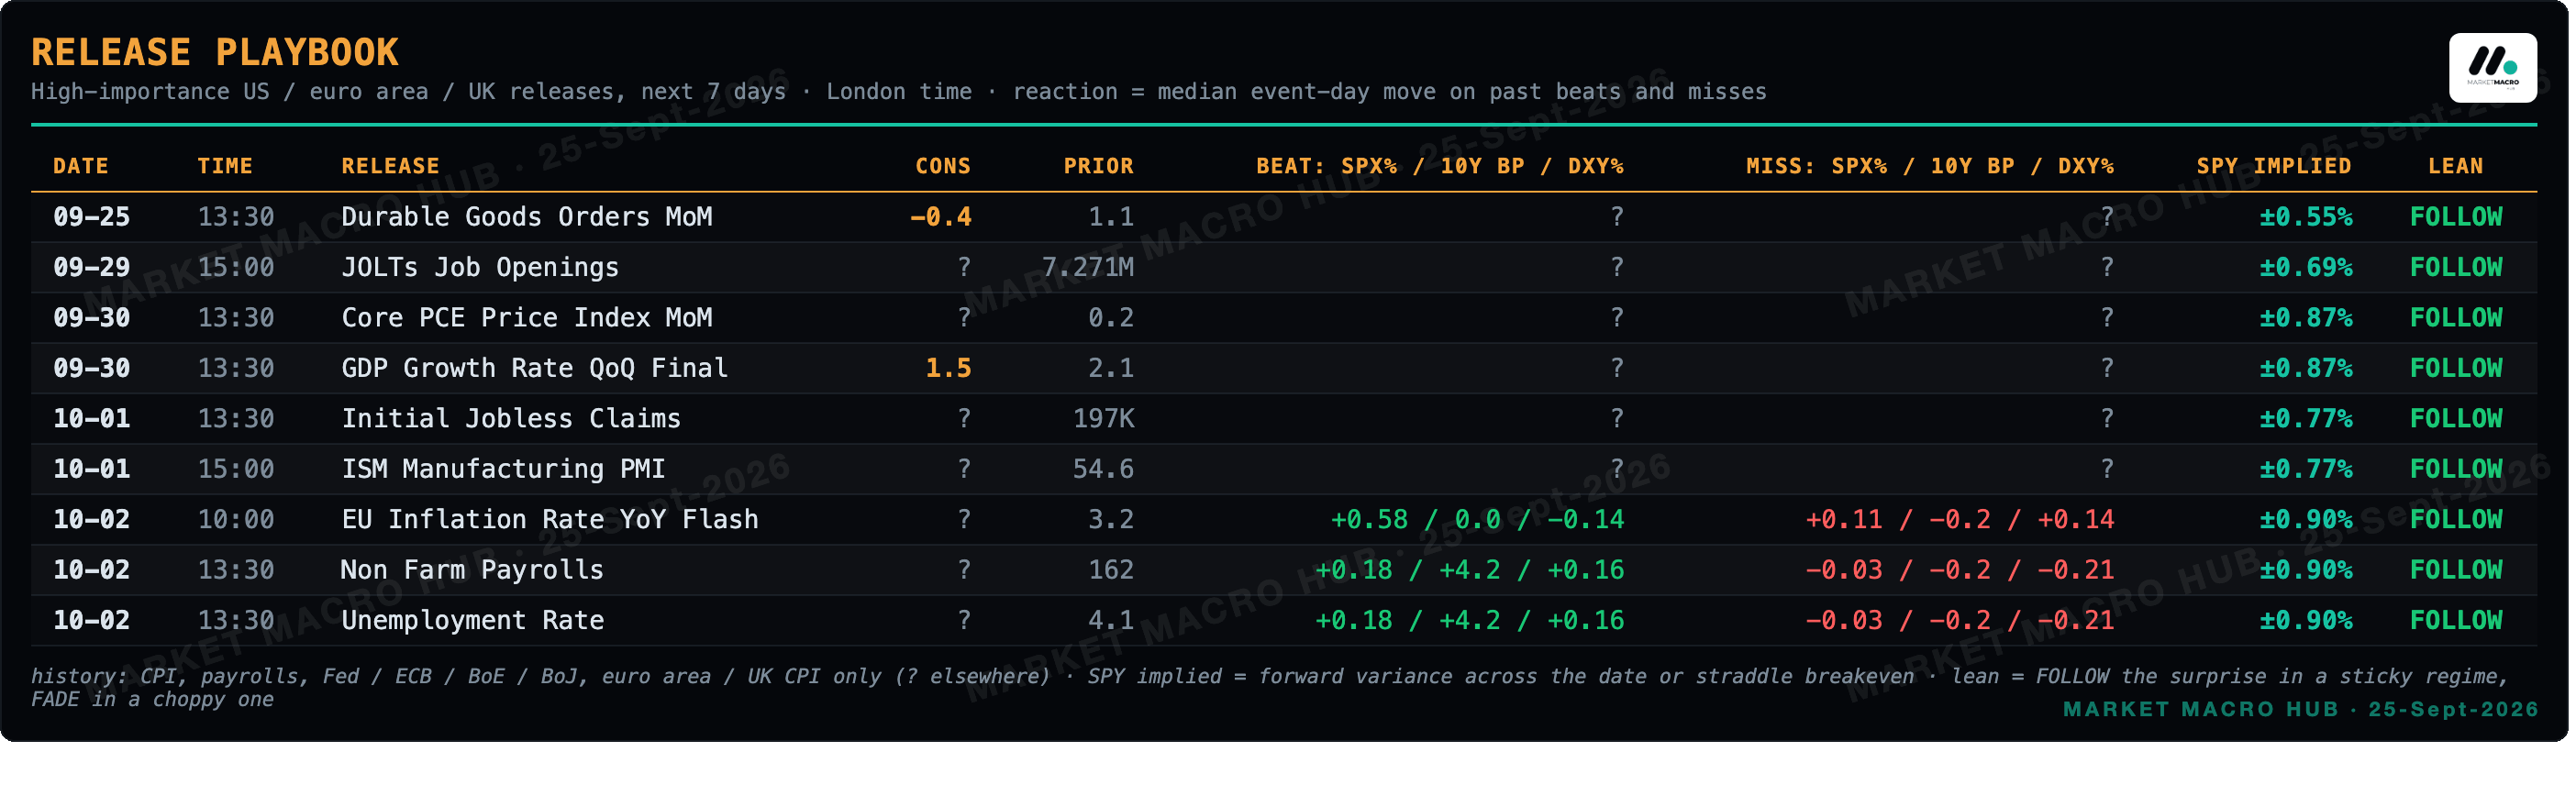
Friday, Durable Goods Orders and the ex-transport read, a soft print would help my case the strip has overshot.
Friday, Michigan Consumer Sentiment Final, watching for confirmation the consumer is fading.
Friday, Fed Williams, Hammack and Schmid speak, the hawkish tone is what has driven terminal this week.
Monday, Dallas Fed Manufacturing, low stakes for my read.
Tuesday, Case-Shiller, CB Consumer Confidence and JOLTs, the labour print is the one that could move my hike view.
Tradeable Levels
Pivots off the last completed session (2026-09-24). Levels marked * sit within 0.6 x ATR14 of the close.
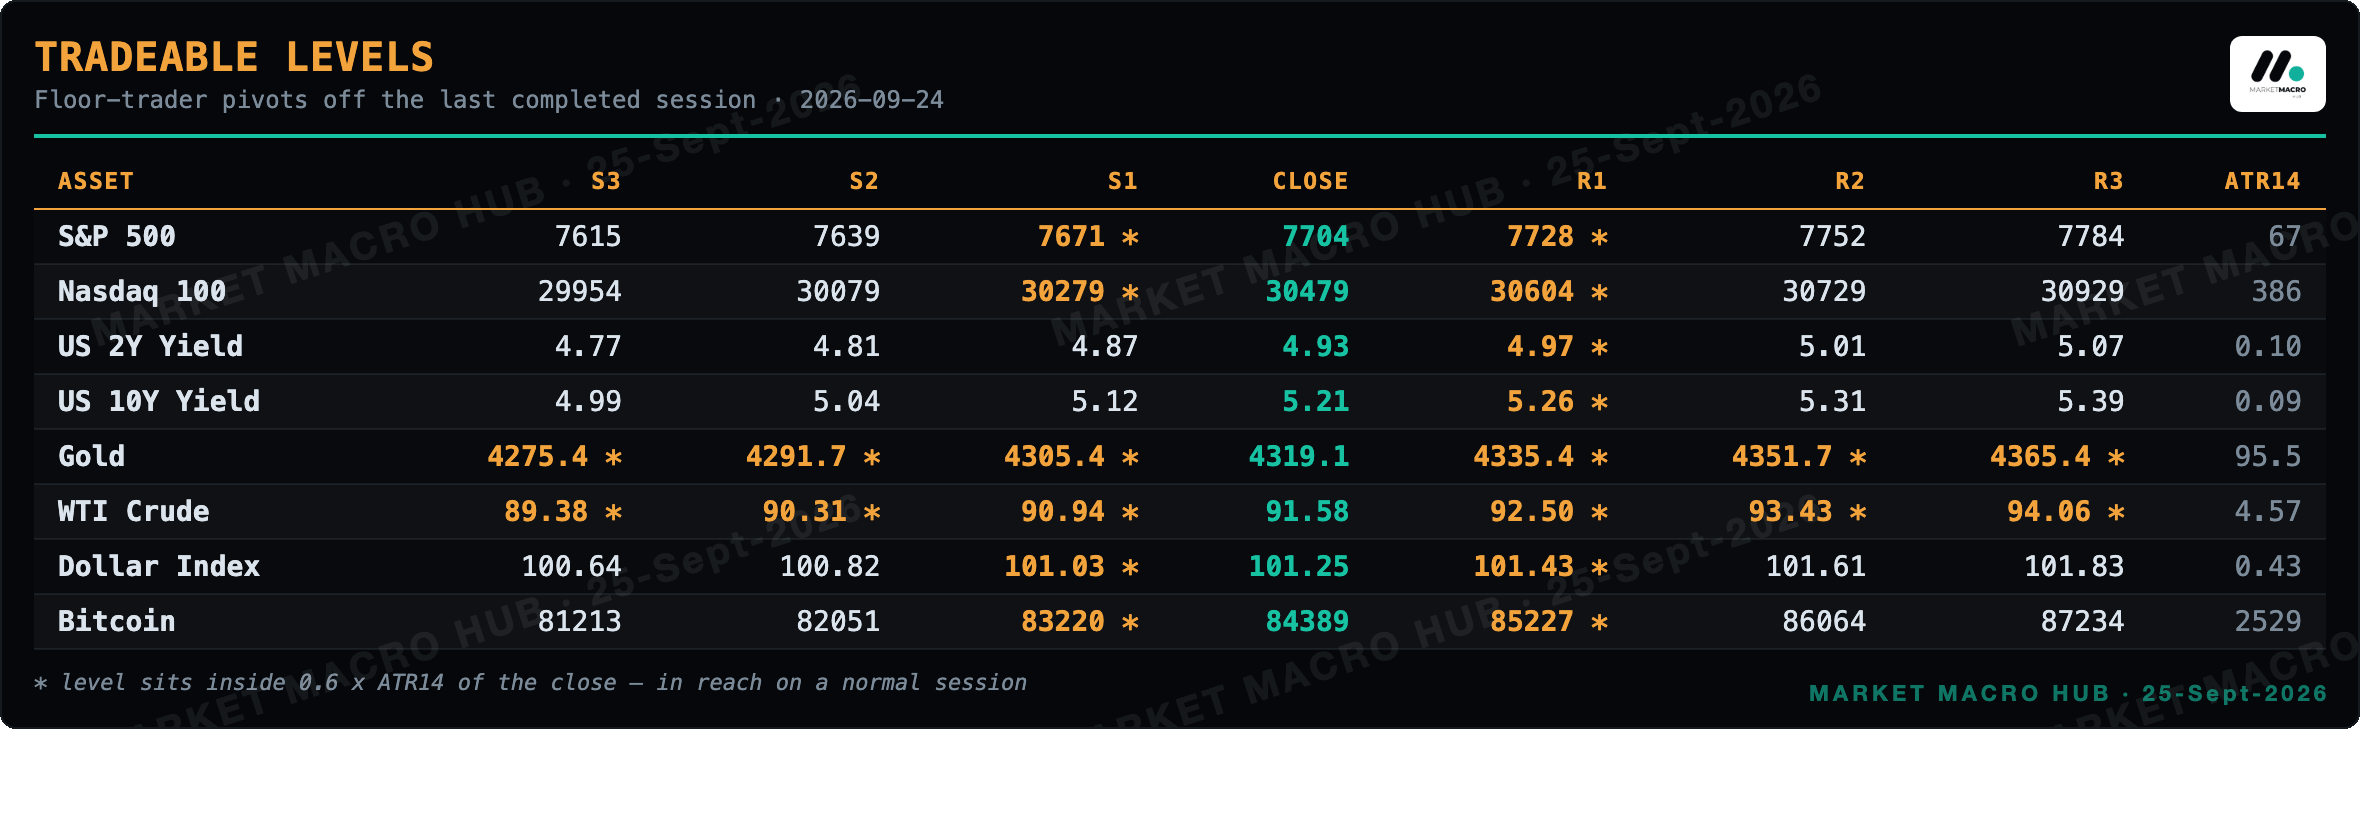
Gold, WTI Crude priced off a session whose range was under a third of normal travel, so those boards are compressed and nearly every level sits in reach. Weekend crypto and half-day holiday sessions do this; treat the levels as loose rather than precise.
Vol Screen · Rich and Cheap Implied Vol
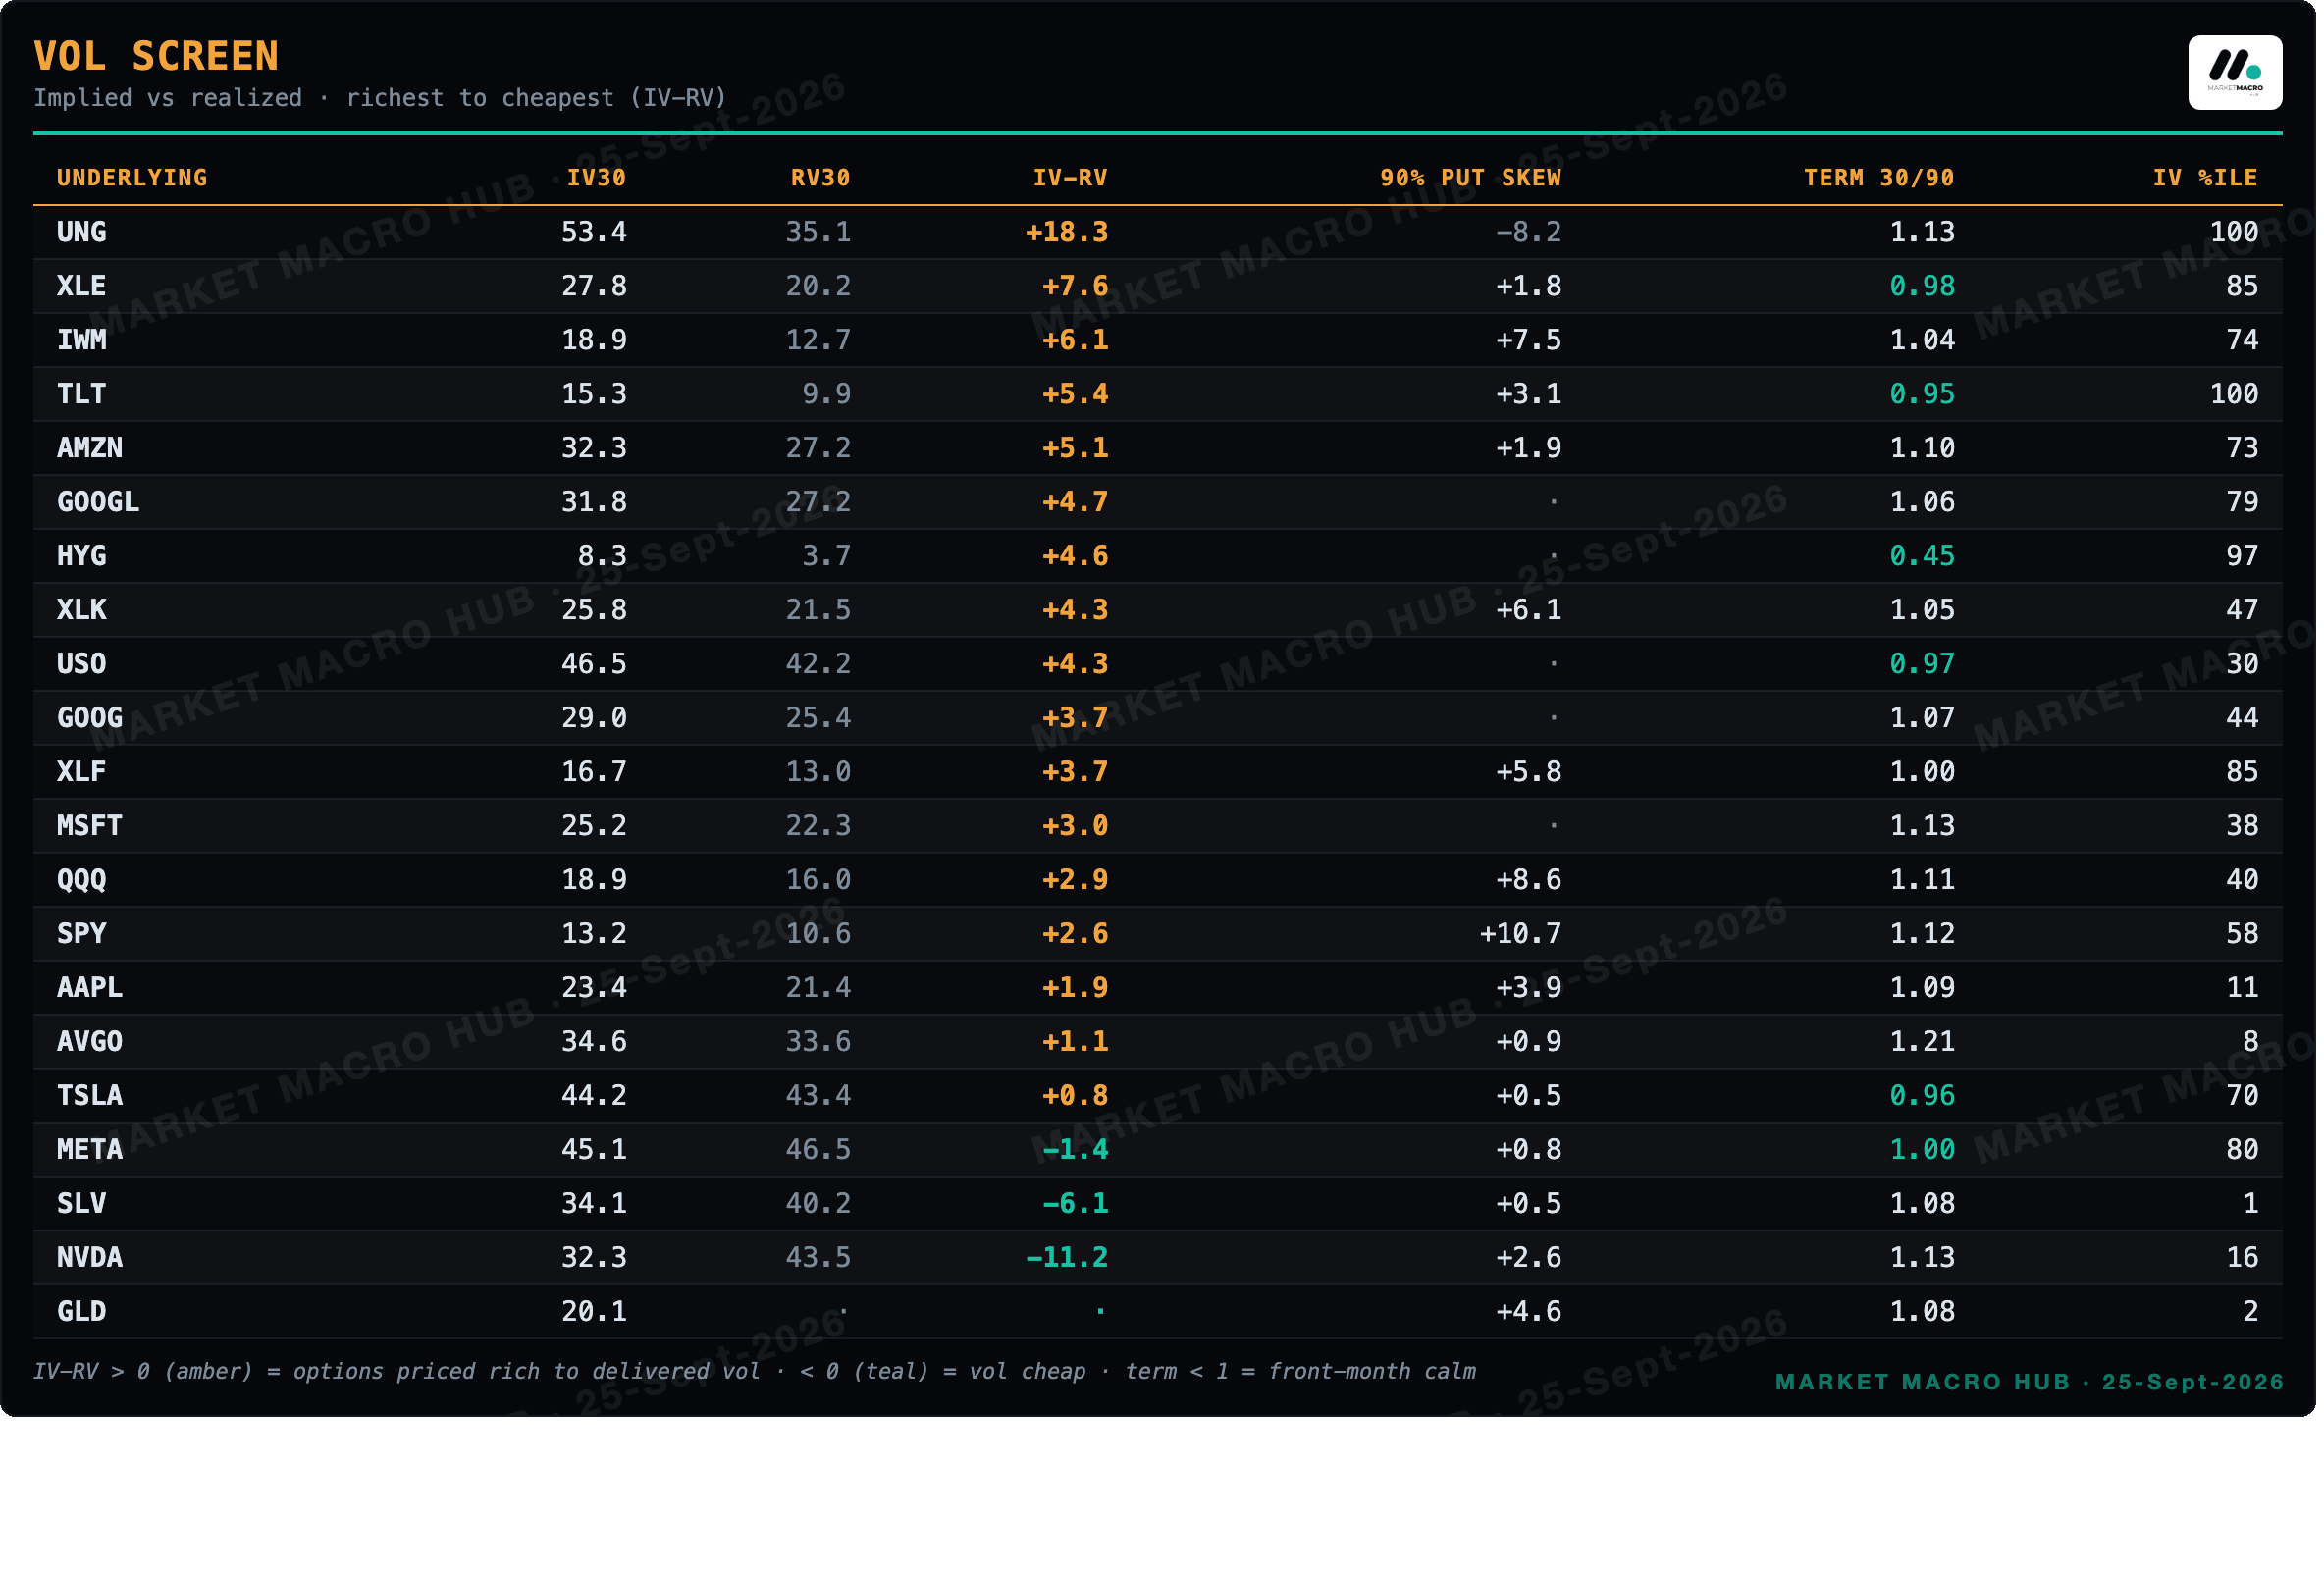
Positive IV-RV = options priced rich to what the tape is delivering (UNG and XLE richest today); negative = vol going cheap (NVDA and SLV). Percentiles are each name's own archive history.
Positioning
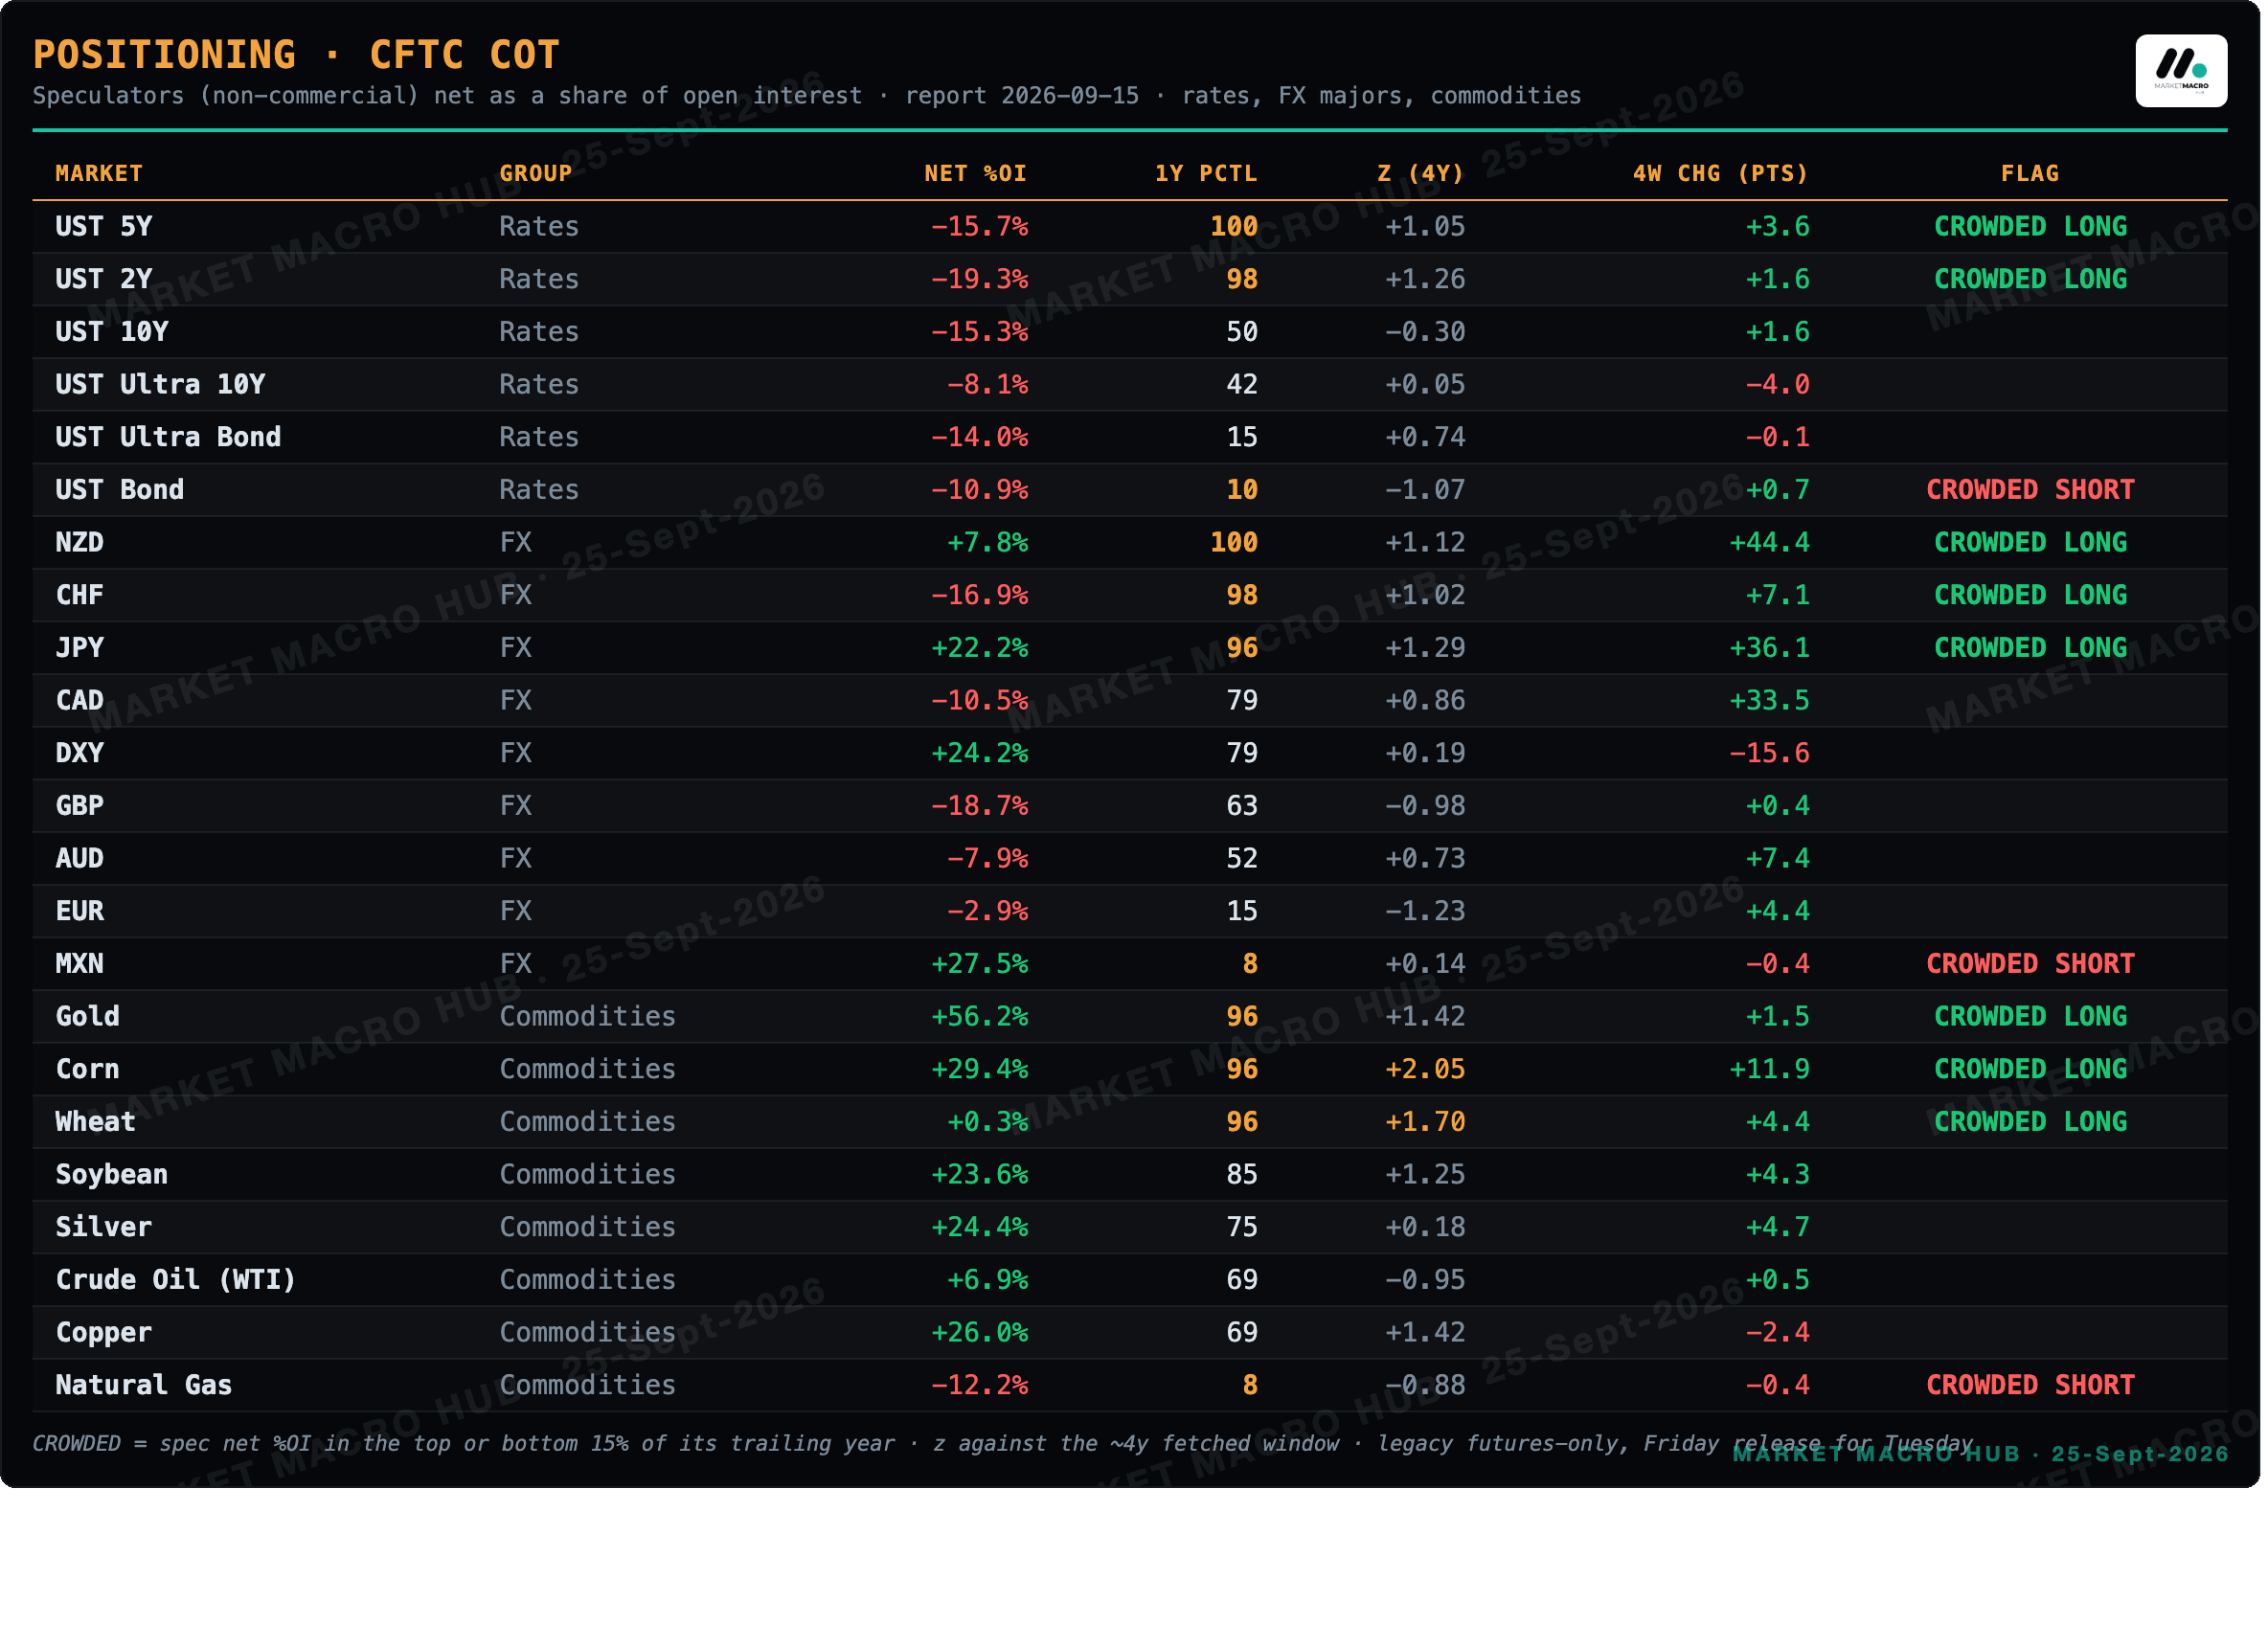
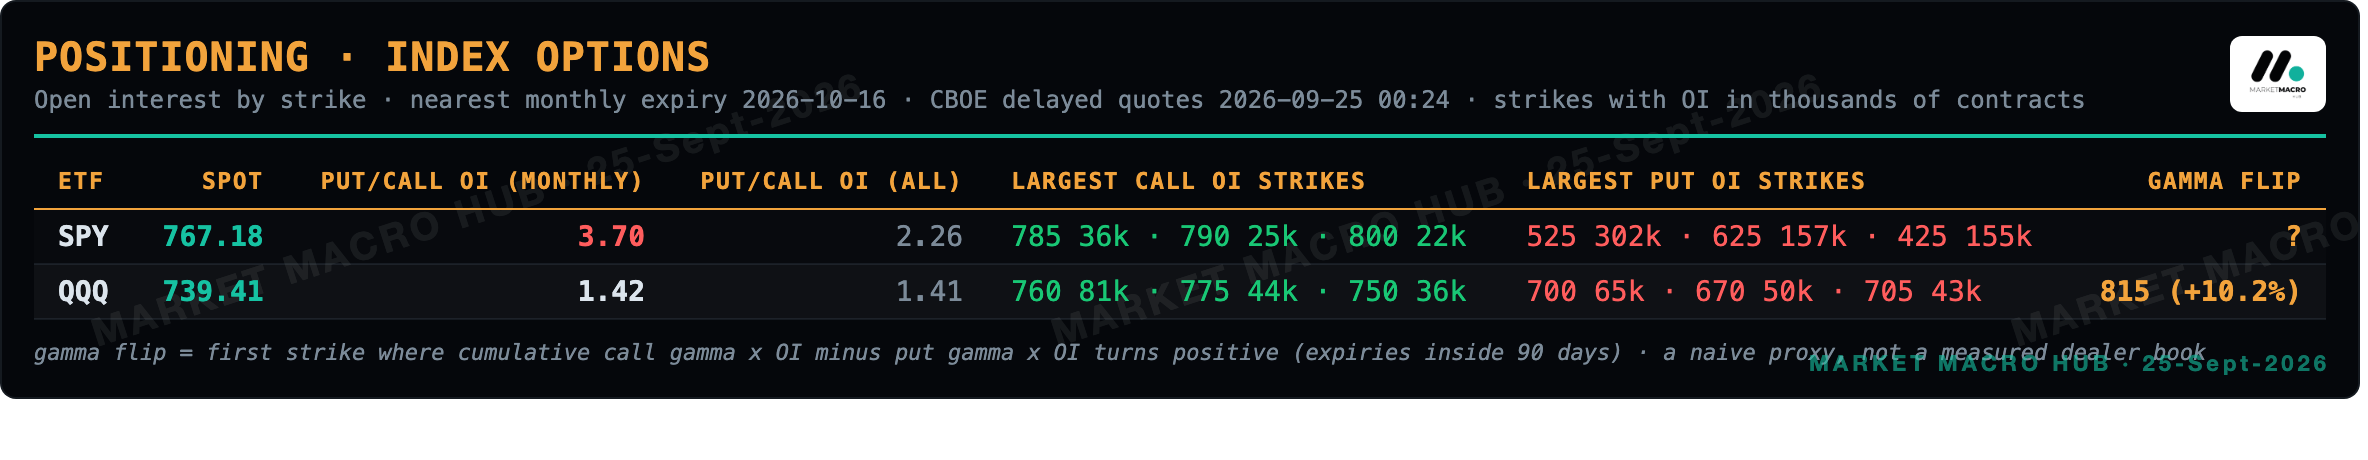
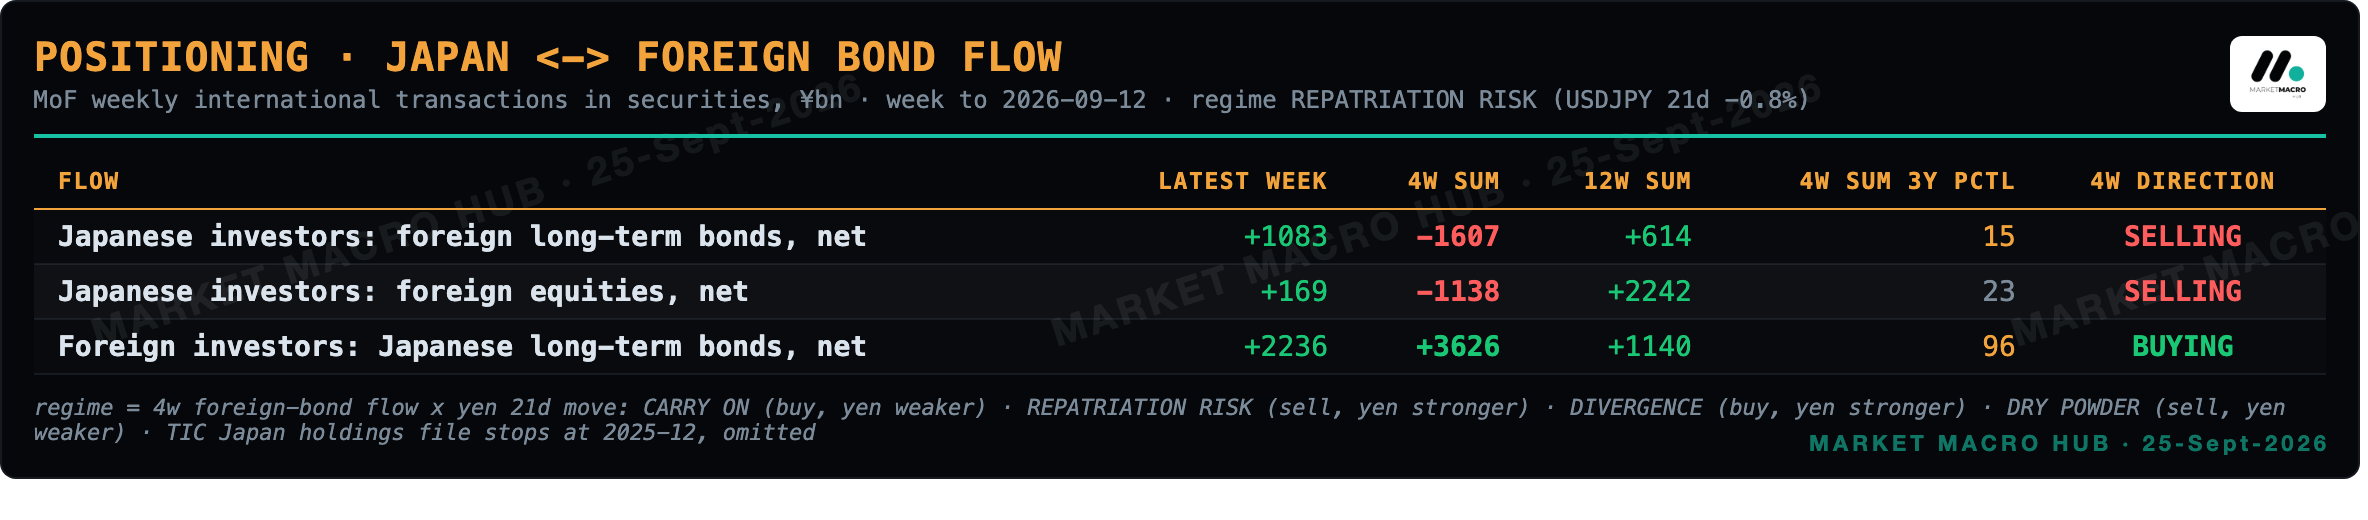
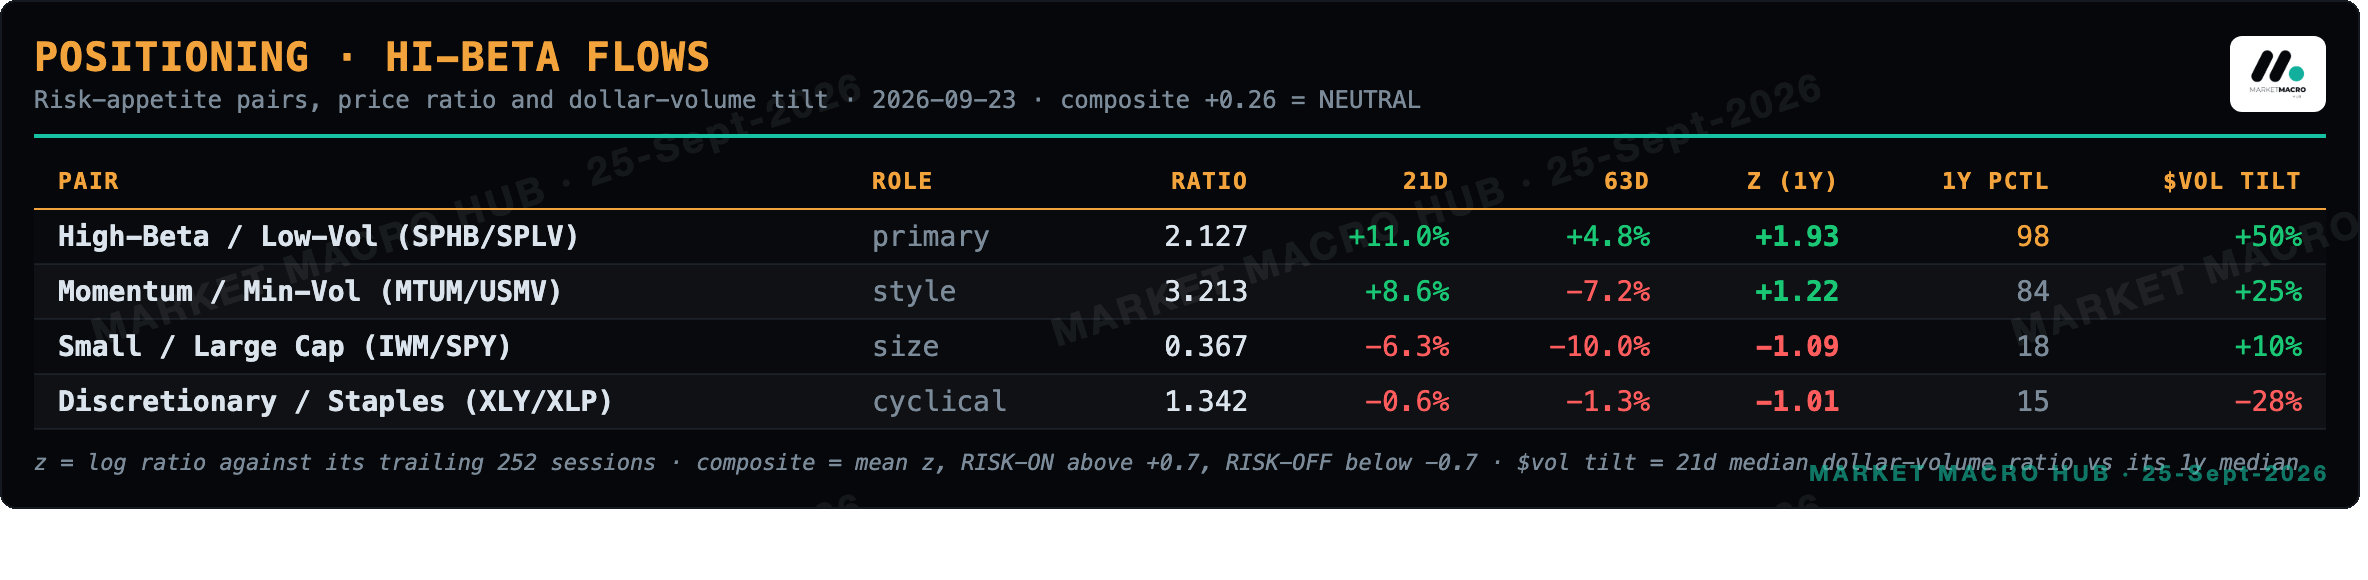
Positioning Book · Friday COT
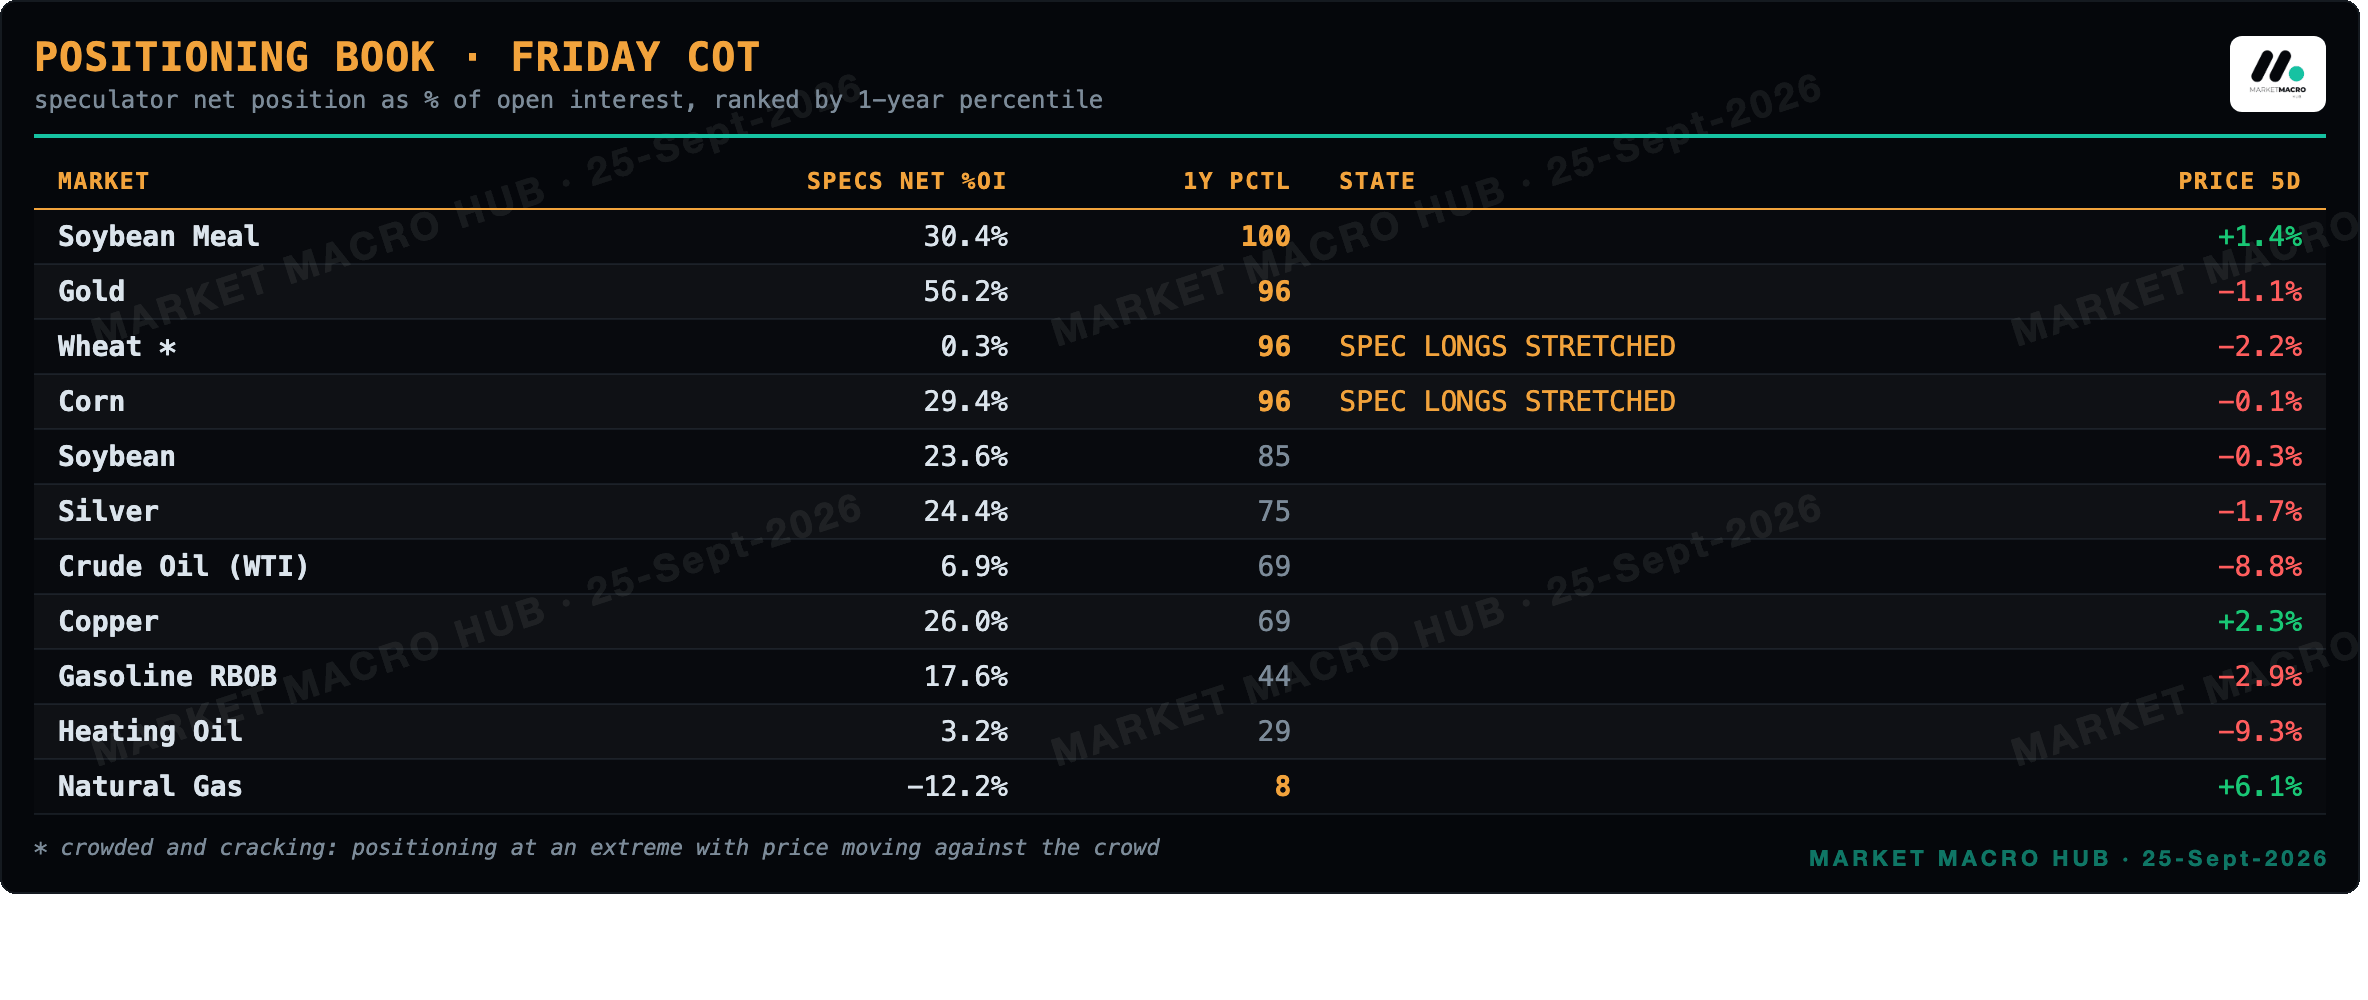
Crowded and cracking: Wheat · positioning at an extreme with price moving against the crowd is where squeezes start.
Disclaimer
The information in this publication is provided for informational and educational purposes only and is believed to be reliable, but its accuracy and completeness are not guaranteed. Nothing herein constitutes investment advice, an offer, or a solicitation to buy or sell any security, derivative, digital asset, or other financial instrument, nor a recommendation suited to any specific reader. All figures are drawn from the day's computed data set at the time of generation and may be delayed, revised, or superseded. Markets involve risk, including the possible loss of principal; past performance and historical relationships do not guarantee future results. Readers should conduct their own research and consult a qualified financial adviser before making any investment decision. The author may hold positions in instruments discussed. This publication is licensed for the personal use of the subscriber only: redistribution, reproduction, or resale in any form is prohibited. © 2026 MARKET MACRO HUB. All rights reserved.