

Before we get into the report, just a reminder that we are switching to paid on October 1st. Until then, we are running a 25% discount on subscriptions so grab it while you can as prices will rise in a few days!
From when we switch to paid, there will be many new models shared in the daily systematic reports, as well as more in depth detail about sizing and HOW I’m managing all trades.
ANNOUNCEMENT: The Next Chapter

For the past 24 months, Market Macro Hub has been a FREE research platform. We’ve continuously reinvested in the platform (and continue to do so) to improve our models, data and the quality of the output we deliver every day to every one of you all (3,000+ and counting!).
I’ve been very open about my positions, how I’m adding to them, and mainly how I’m managing both equities and oil through this volatile period of time.
For anyone in the substack chat you will see that there were some trades I shared recently:
ES long, massively onside
Oil short, onside
ZT short, most gains realised
Russell long, hit breakeven
Eurostoxx long, floating in some drawdown
ES short, all gains realised

Now I am not disregaridng the FX side of things, but ultimately differentials are driivng the dollar so aggresisvely that it’s becoming hard to step in and get short. I do not want to be long the dollar, I think at best we’ll see EURUSD range, I also think the aggressive sell off in that pair is beginning to hit an extreme but it’s not a time I want to get long.
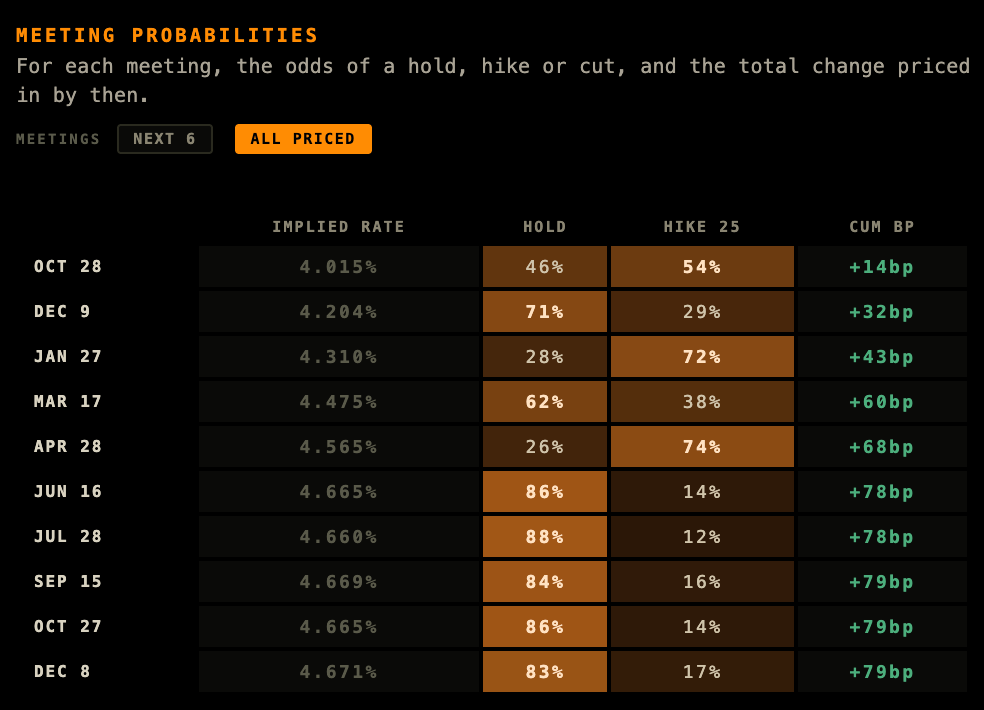
This is the forward curve for the Fed that’s been priced:
And this is the forward curve priced for the ECB:
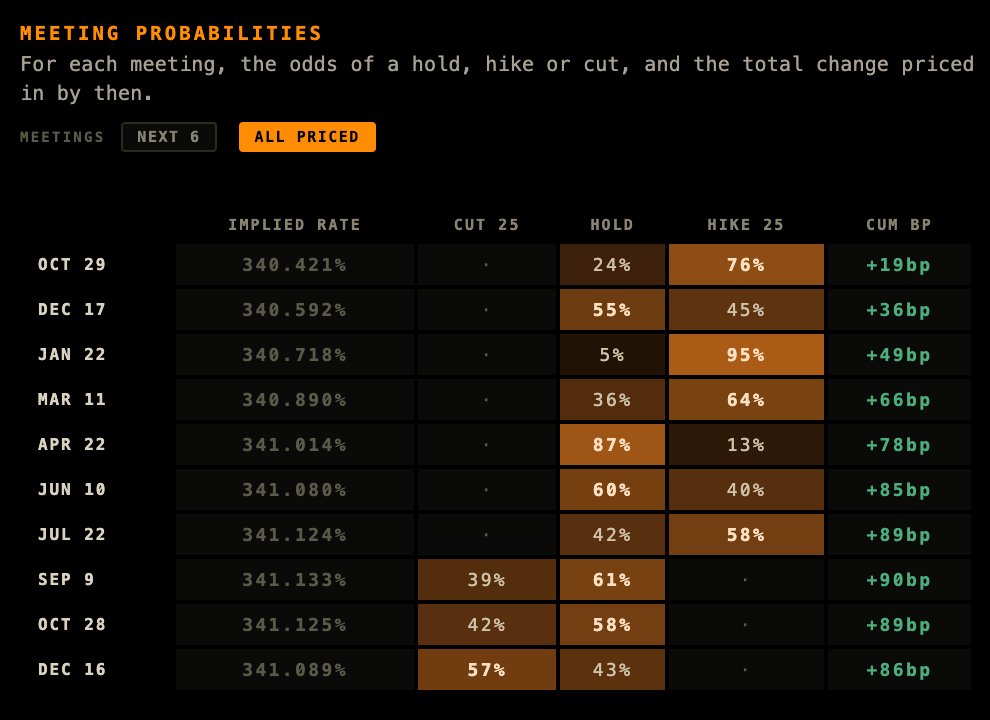
Remember that the Eurozone are a net importer of energy so they are DIRECTLY impacted more than the US are when oil rises, which is why I laid out wanting to get long the Eurostoxx because it’s likely that as oil unwinds, eurostoxx & the Dax will probably outperform the S&P unless there are MORE factors driving the S&P, like bonds beginning to bid, which is then when I’d expect US equities to outperform.
Now before getting long EURUSD I want to see ZT bid with momentum and close higher on consecutive days during the week while outperforming German bunds. It’s critical that we get outperformnace in ZT here because if not then the strongest catalyst (differentials) do not support the idea. I’m not in the game of catching lows, but I do think EURUSD is set to bottom at least on a short-term basis here.
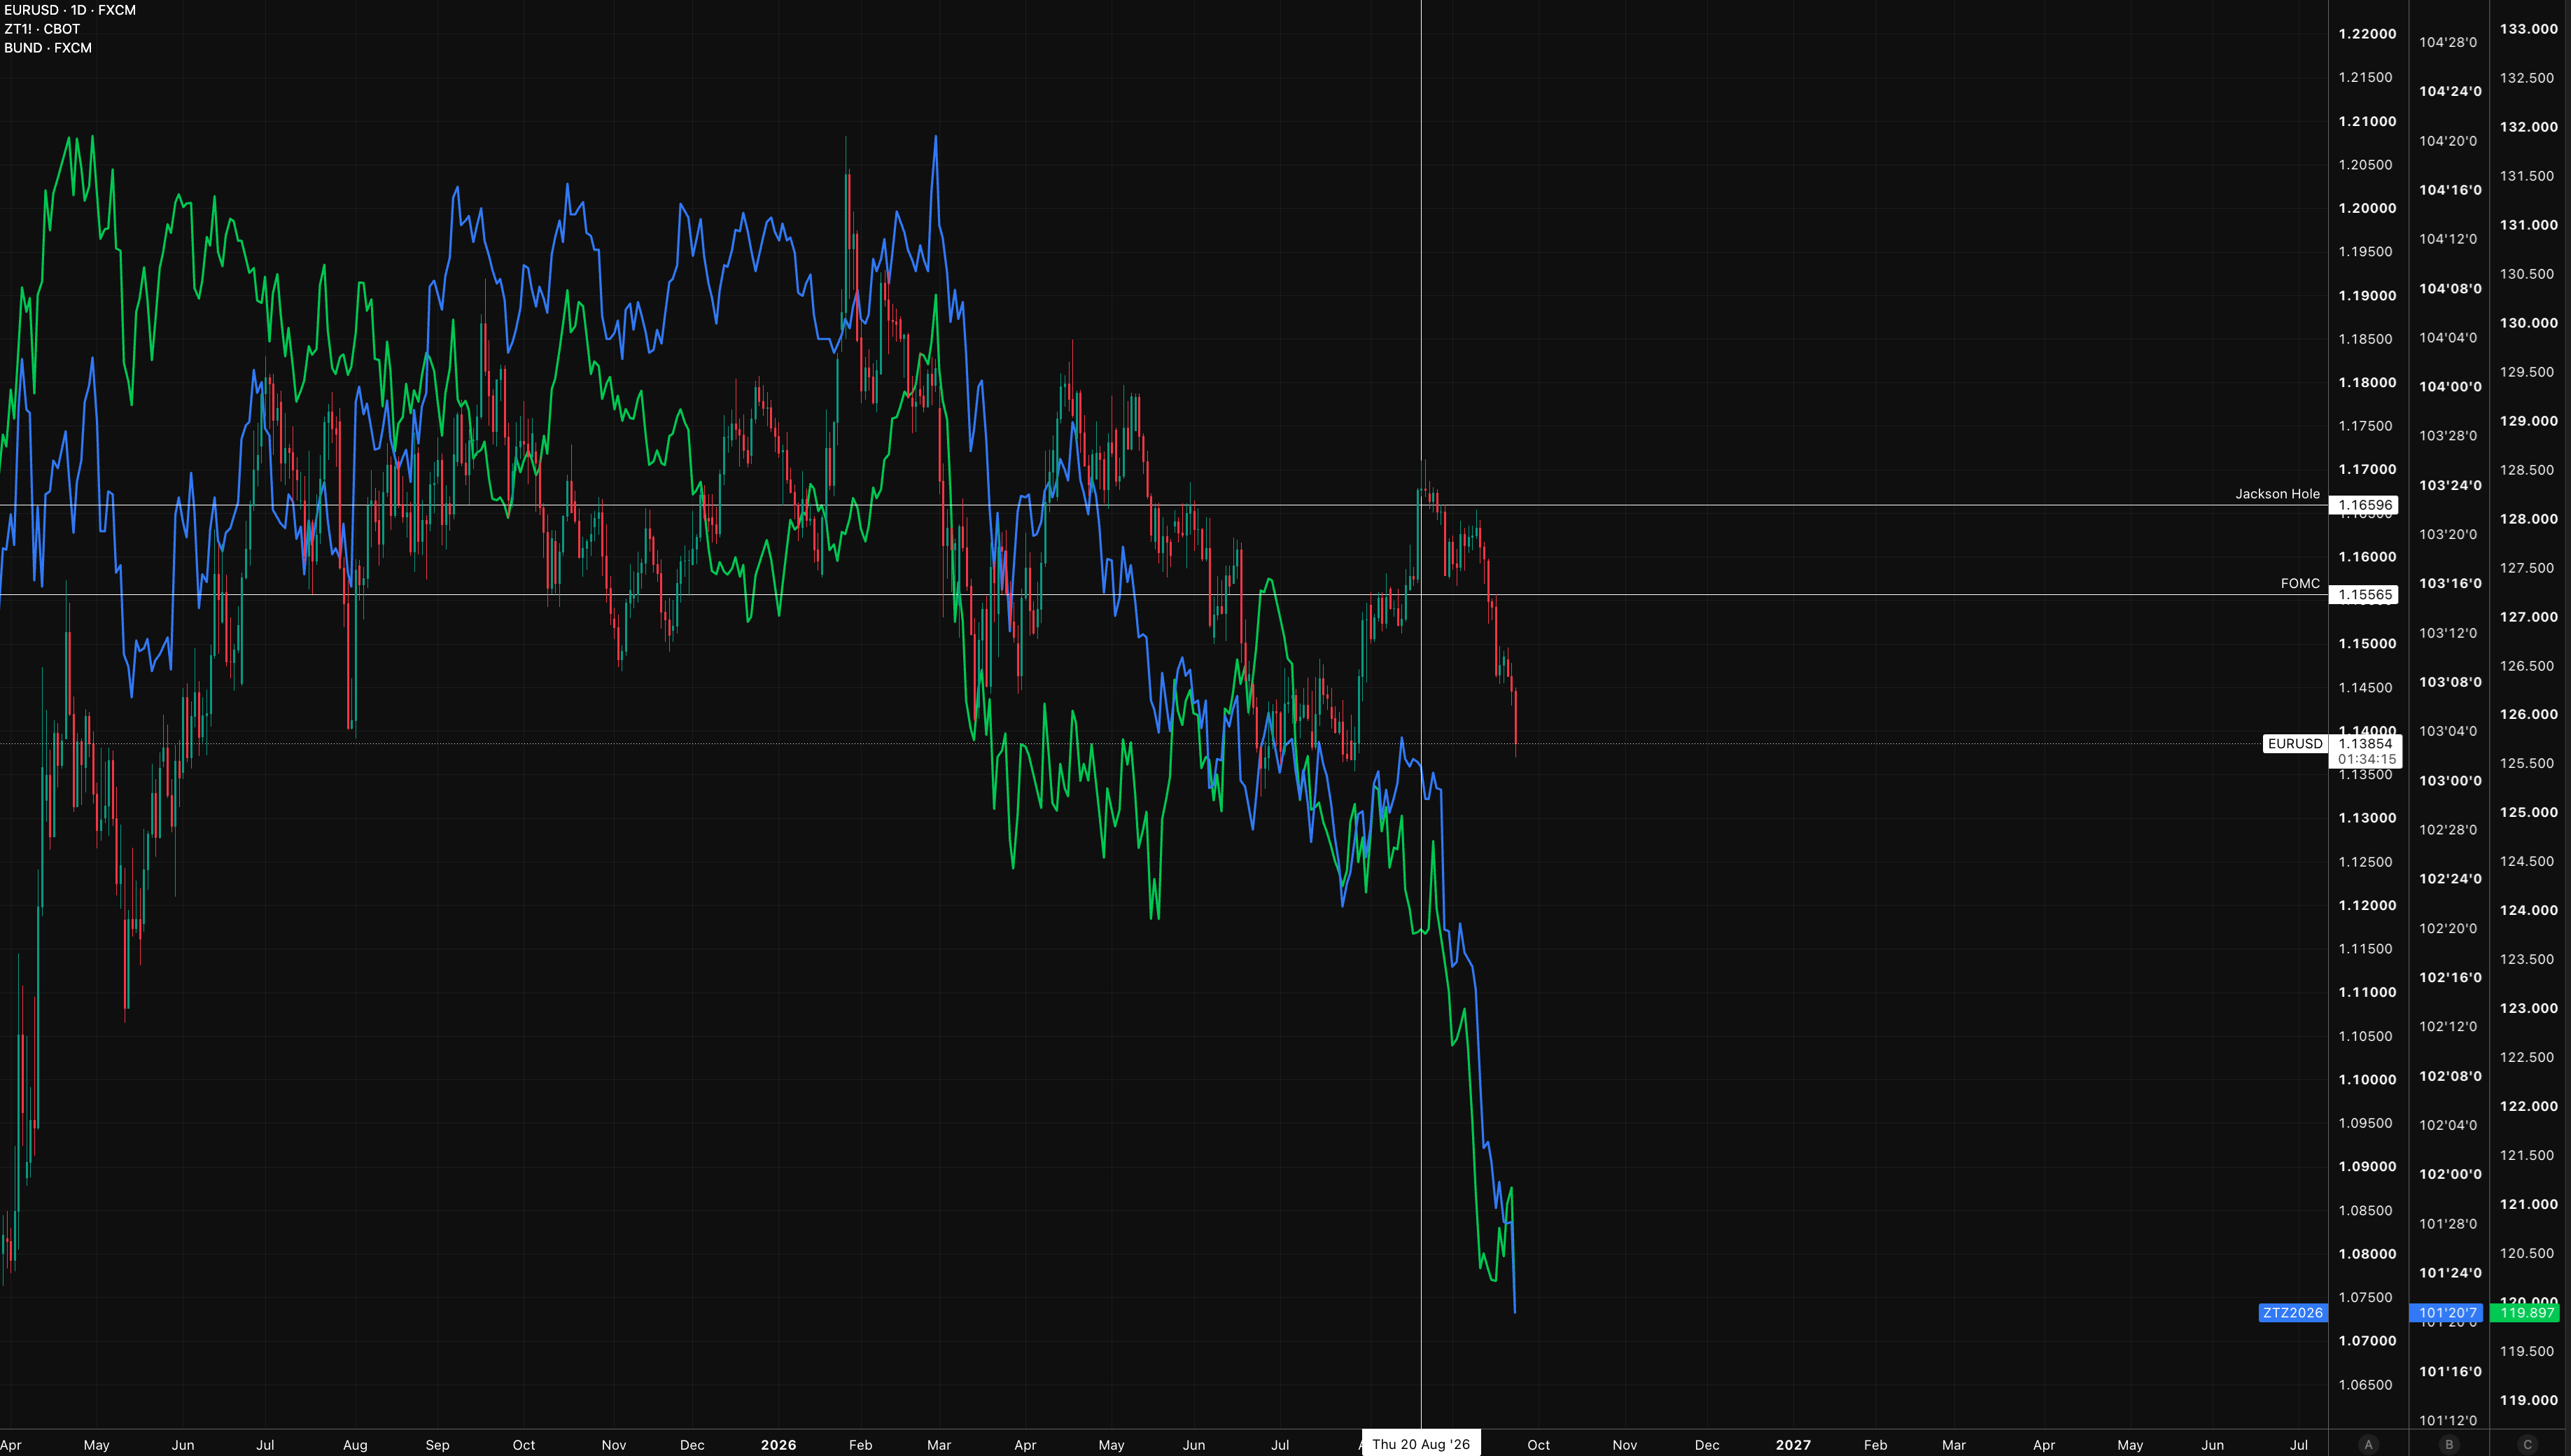
It’s also important to note that there is still a strong likelihood that the Fed remains less restrictive than the ECB and create a range in EURUSD, based on what we’ve seen over the recent weeks. And not to forget that even as we have NQ outoperforming massively, we have the 10y yield rising just as aggressively, and the russell underperforming the most which shows that the russell will likely not move as strongly as ES & NQ when oil sells off, but when yields begin to drop then russell will have outperofrmnace.
So all views im creating on the russell are predomianntly based around my views on bonds. Of course, I consider bonds and fx when getting long ES & NQ, but the driving factor now is oil and growth, wheras russell is tied so heavily to movements in the 10y.
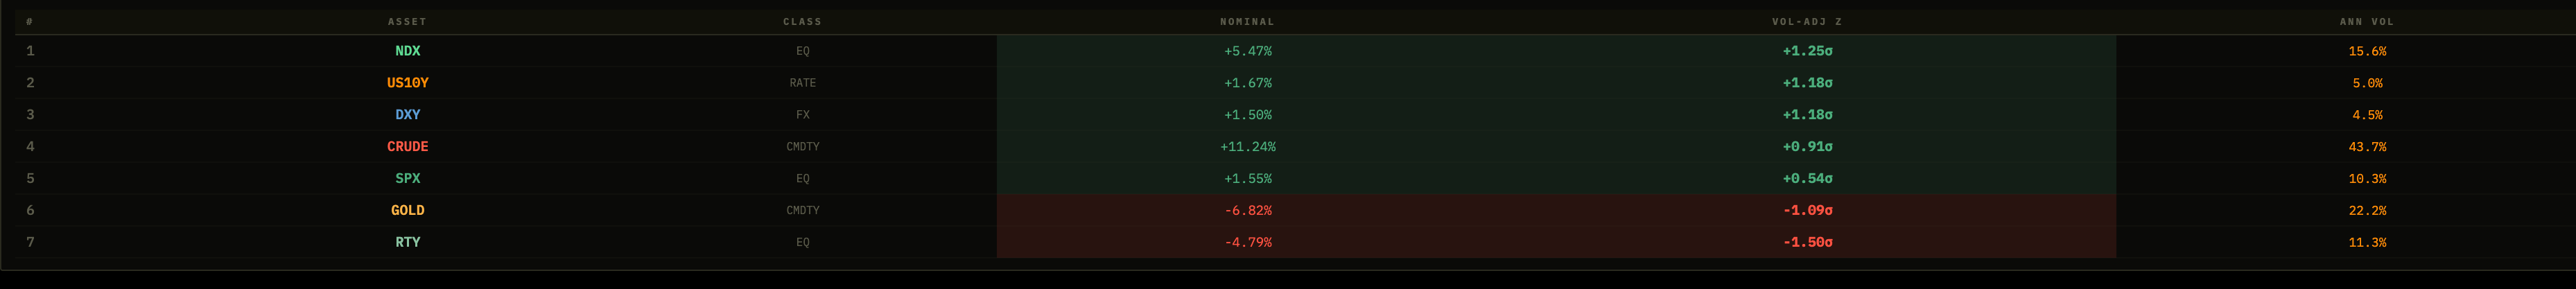
It’s also very hard for gold to make a bottom anytime soon for as long as the forward curve is this restrictive with the dollar is bidding too. However, I am not bearish on gold and it would make little sense to get short here considering that I think it is unlikley that the Fed delivers 4 hikes (meaning there’s an extreme that could cause a top in real rates). But we’re not theer yet and I’m not trying to get ahead of the real rates curve, I want to see the forward curve reprice as the Fed maintain their stance on inflation which would be the catalyst to set a top in real rates.
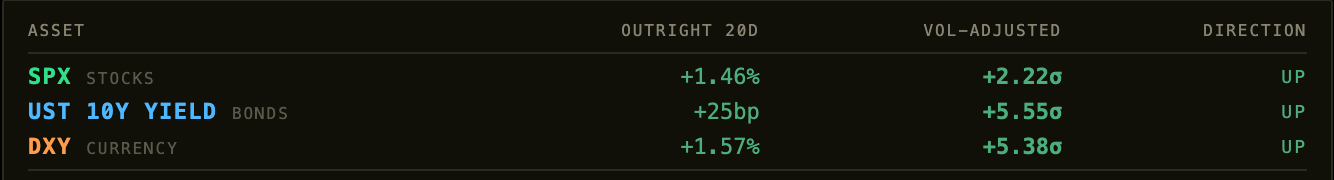
Over the last 20d we’ve also seen equities, rates & the dollar bid which is evidence that regardless of how many inflationary poressures exist from oil and governemnt spending, growth is mitigating these risks. But if we know that most of this growth has come form capex and AI, then we know that a turn in events in either of those themes is going to be the catalyst that could send equities into a prolonged drawdown.
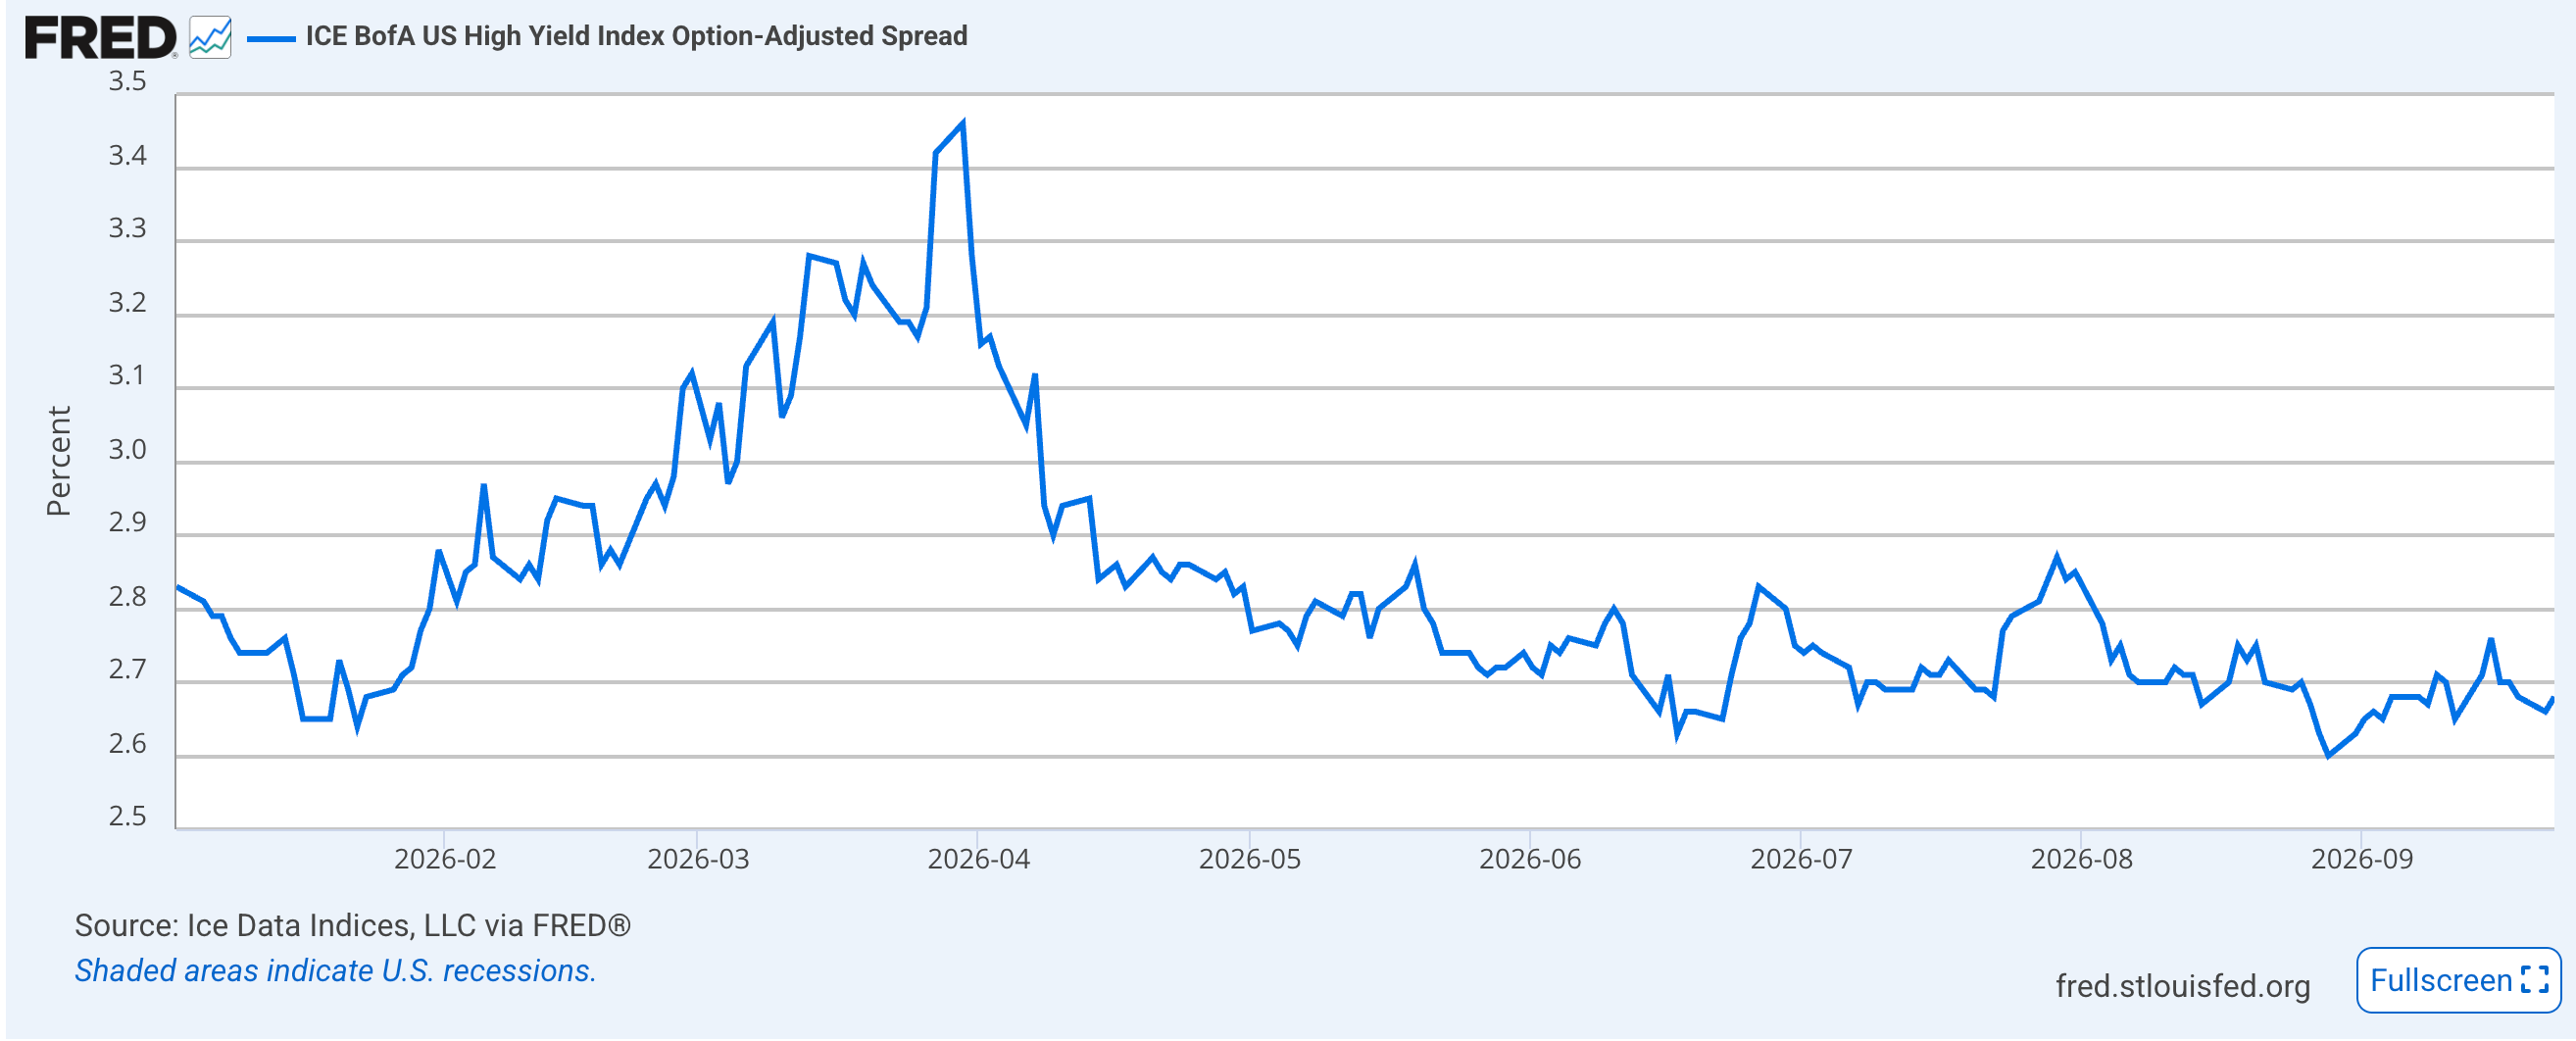
Notice also how even with bonds falling into a huge drawdown, credit spreads are at cycle lows, this can ONLY be because growth is so strong that it’s mitigating these factors.
Bear in mind that if inflationary pressures decline, which is a possibility through 1) how the Fed manage the short-end and 2) oil prices dropping aggresisvely, then growth dominates the theme again (unless the restrictiveness form the Fed is outsized and slows growth), and then we are HIGHLY likely to see another leg higher. I’d much rather keep getting long here as this is my base case scenario. The tail-risks to equities are bonds selling off this aggressively, which I am monitoring. It’s also key to understand that there is a specific yield that exists where growth can no longer mitigate the effects, and that’ll cause a sharp repricing in equities and ultimately could cause a longer drawdown given all the positioning and leverage that would be unwound.
To make it clear, I want to get short the dollar at some point in the next 2 months. Yes this time period is pretty broad but I’m not putting on a trade right now so it’s not important to figure a timeframe. That could be next week or it could be in 6 weeks, the timing for getting short the dollar COMPLETELY depends on how equities, bonds and oil peroform because all of these will be the inputs to reprice the forward ciurve.
If equities began trading aggresisvely lower on the forward curve repricing, there’s a strong chance that those hikes wouldn’t be realised in my view because I think the Fed would rather deal with a higher level of inflation for longer rather than send equities into a drawdown and crush growth, espeically when they understand how much capex and leverage exists, it could cause some type of capitulation like April 2025 and then they’d lose the battle against inflation anyway because they wouldn’t be able to hike where they need to.
The carry trade is also still shaky with AUDJPY, MXNJPY and USDJPY still off of highs, the movements in USDJPY is USD driven and there isn’t persistent strength in the carry trade. If there is a real unwind in the carry trade (a possibility given the dynamics in Japan), then that’s another time where equtiies could be sent into a drawdown. For now, there is not enough risk exisiting in the carry trade for me to want to be neutral or short equities, the edge is titled to the upside.
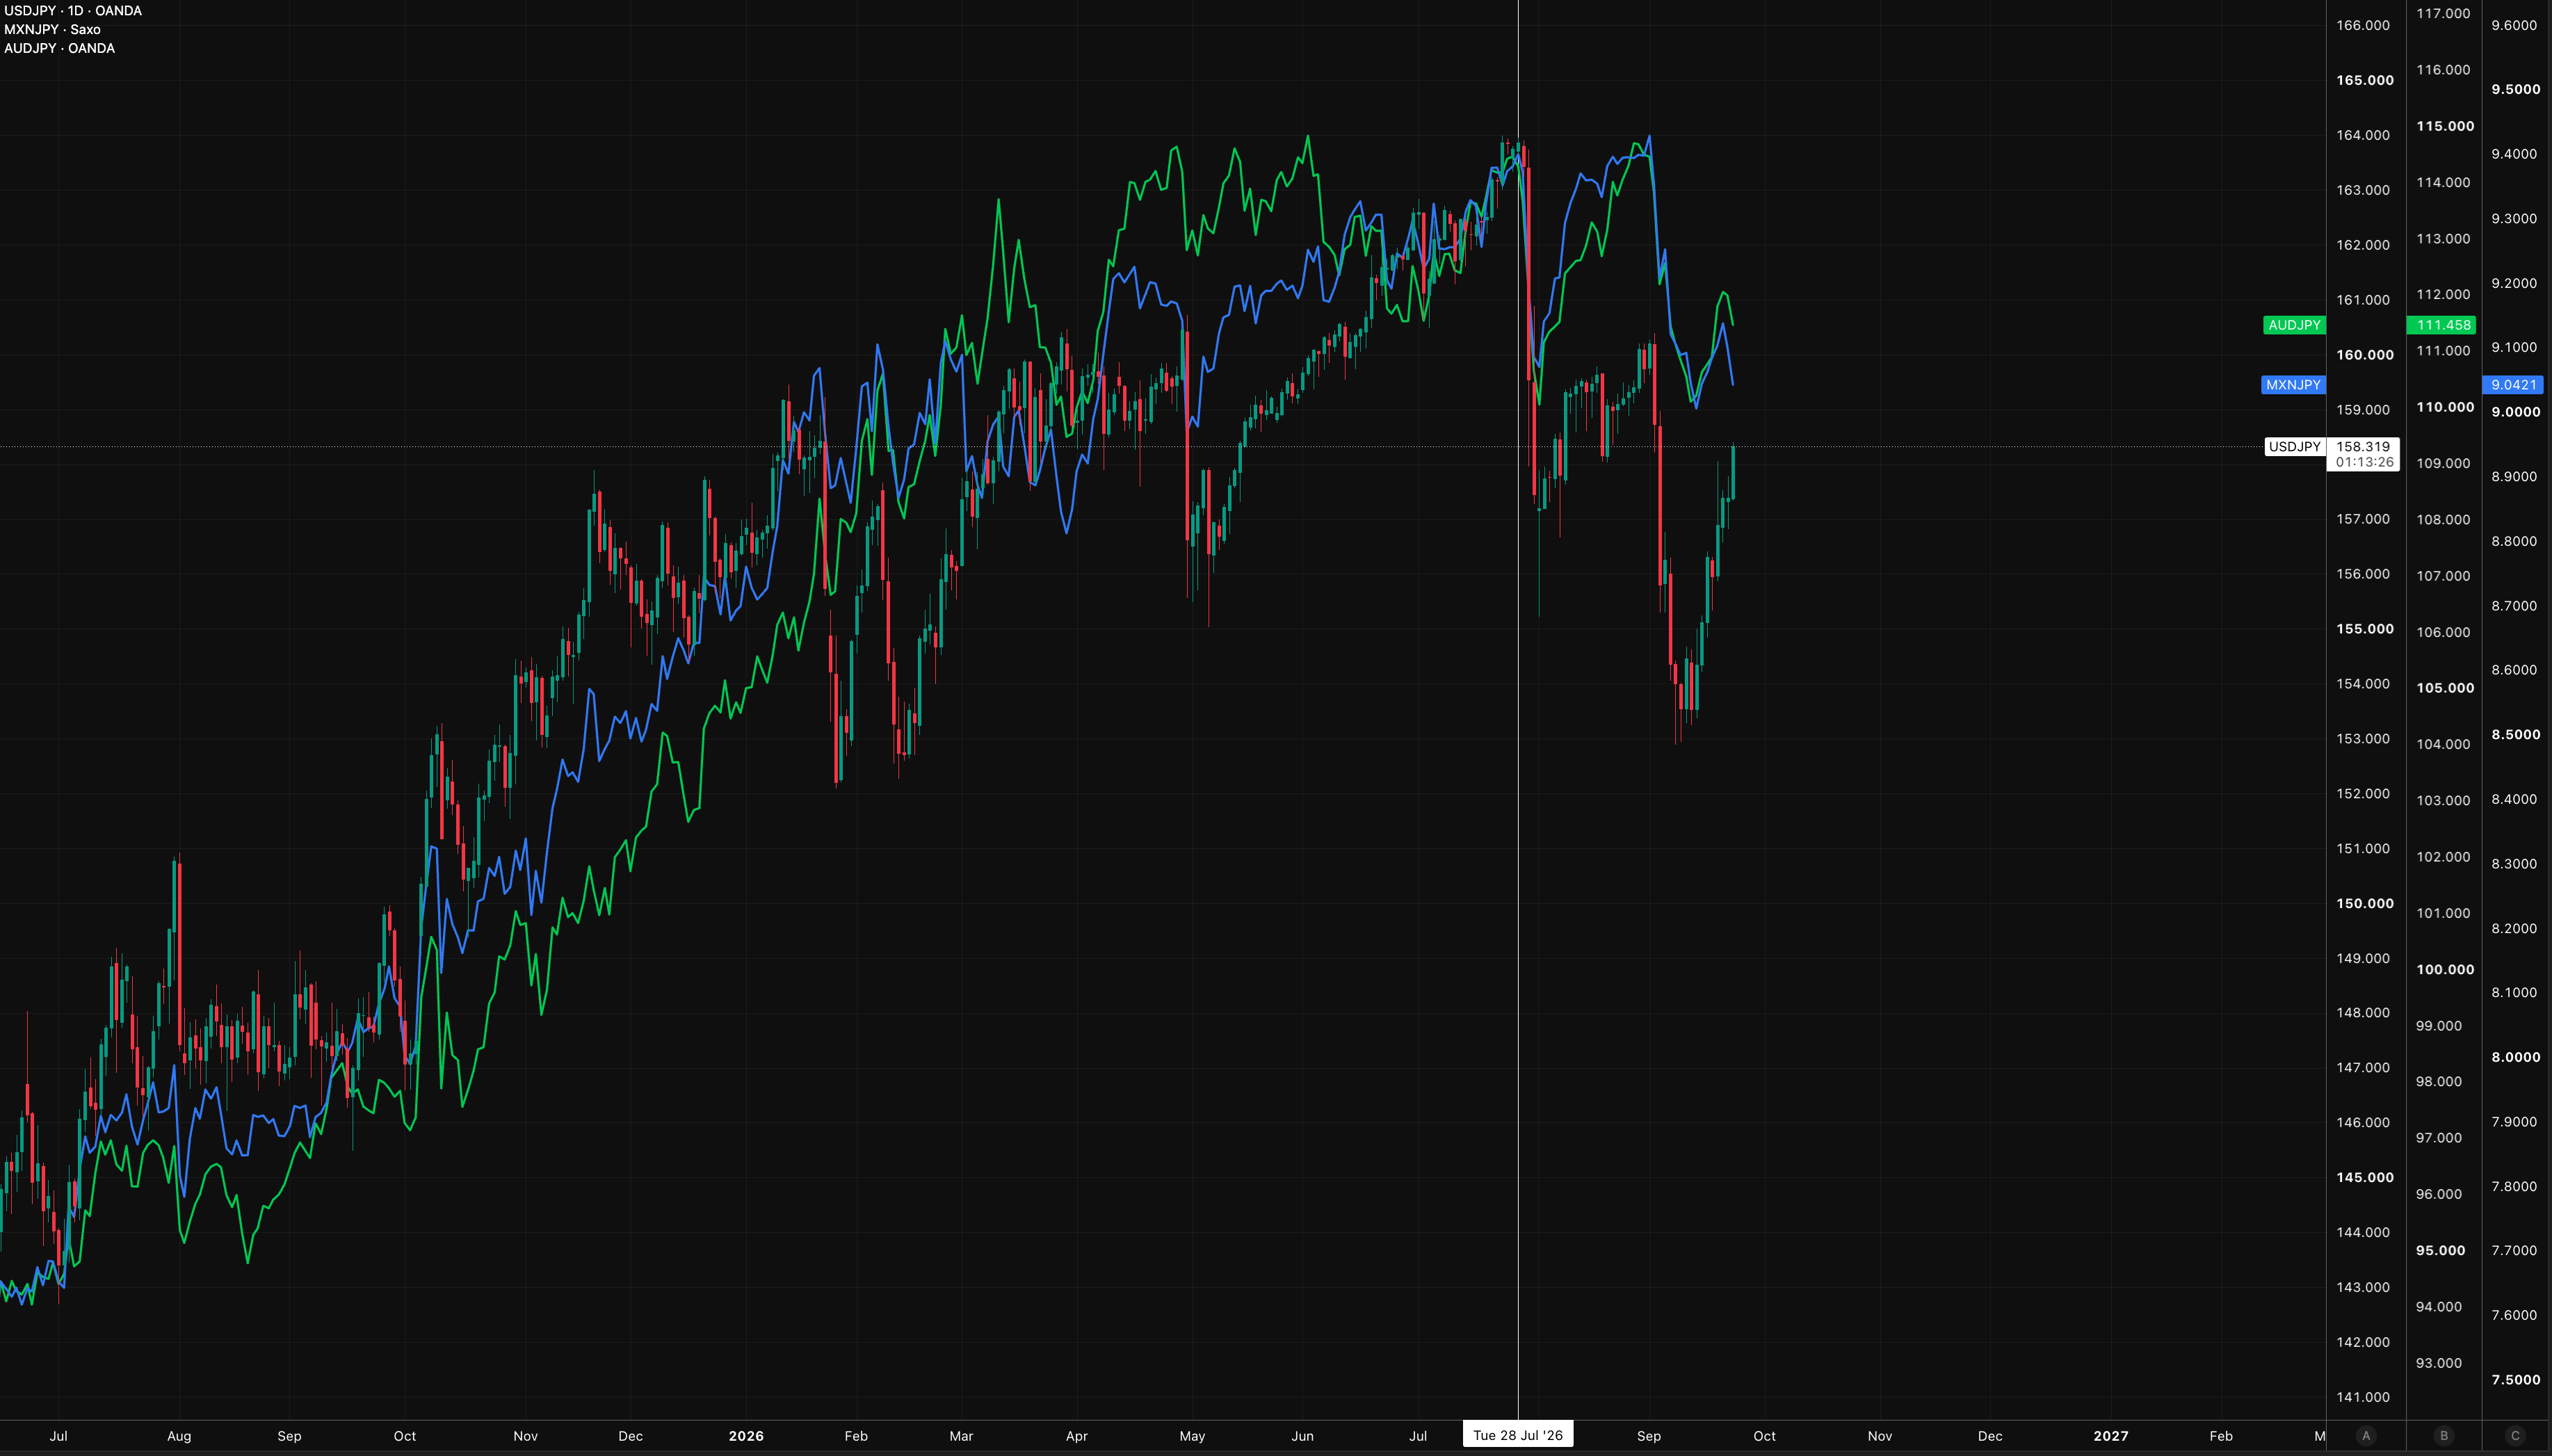
If the carry trade does unwind and it caused selling in both equities and bonds, I’d likely even get long EURUSD as we could have a type of April 2025 moment where everyone flees the US, this is NOT my base case but is a scenario I’m planning for.
For now, my posiitons are as laid out at the beginning of the report and I will update you guys on any new trades I take, which is likley.
Thanks
Alfie
Disclaimer
The information in this publication is provided for informational and educational purposes only and is believed to be reliable, but its accuracy and completeness are not guaranteed. Nothing herein constitutes investment advice, an offer, or a solicitation to buy or sell any security, derivative, digital asset, or other financial instrument, nor a recommendation suited to any specific reader. All figures are drawn from the day’s computed data set at the time of generation and may be delayed, revised, or superseded. Markets involve risk, including the possible loss of principal; past performance and historical relationships do not guarantee future results. Readers should conduct their own research and consult a qualified financial adviser before making any investment decision. The author may hold positions in instruments discussed. This publication is licensed for the personal use of the subscriber only: redistribution, reproduction, or resale in any form is prohibited. © 2026 MARKET MACRO HUB. All rights reserved.
great read mate, keep these fx updates coming! <3