


TL;DR
Long the hike story, November at 72% is the first half-priced move and no cut sits on the strip.
Short three fully-priced hikes as stretched, my tell is 2s10s steepening to 31bp; bear flattening changes that.
Oil is the engine, WTI +1.8% on the Hormuz standoff is dragging the whole terminal higher.
Credit is my anchor, IG at 81bp signals no stress, invalidation stays 90bp.
Rate vol tail stays live, MOVE at 101.8 hasn't leaked into a contained VIX at 16.1.
Where We Stand
Yesterday I said I'm long the hike story, November at 72% is the first half-priced move and no cut sits anywhere on the strip. This morning's tape confirms it: the front end is bid and the terminal keeps grinding higher. The oldest live view, IG credit staying bid below its 90bp mean, is INTACT, spreads sit at 81bp this morning and my invalidation at 90 is nowhere near. But my newest thesis is the one under pressure. I said three more hikes look stretched with 2s10s steepening, and the curve did steepen another +5bp to 31bp, so the read holds, the long end is repricing growth and inflation faster than it is doubting the short-end path. The GBP washout flag and the gold weekly move flag are both still live.
Today's Tear Sheets
The full daily pack is attached below · six PDFs generated from the same computed data set as this note:
Macro Regime · regime classifier, growth x inflation quadrant, curve regimes, cross-asset drivers, crisis phase, model state card, breadth, credit, vol term structure, liquidity, stock-bond correlation, housing
Fixed Income · UST complex, term premia, rate risk, auctions, global curves, Fed/ECB/BoE/BoJ implied policy paths, global 2Y and 10Y panels
Equities · index pages, daily attribution, relatives, vol suite, vol cone, gamma, global relatives, Mag7+ quant sheet, options surfaces
FX · majors dashboards, carry, correlations, COT positioning, crosses
Commodities · energy, metals, agriculture, COT crowding, term structure
Crypto · BTC ladders, ETH, macro correlations, ETF flow proxy

Machine-readable pack (CSV + JSON): https://drive.google.com/drive/folders/1fSemQdPNqjy9fbUrGbCE-HJZOvJXc4X1
What Changed
What the Tape Is Arguing About
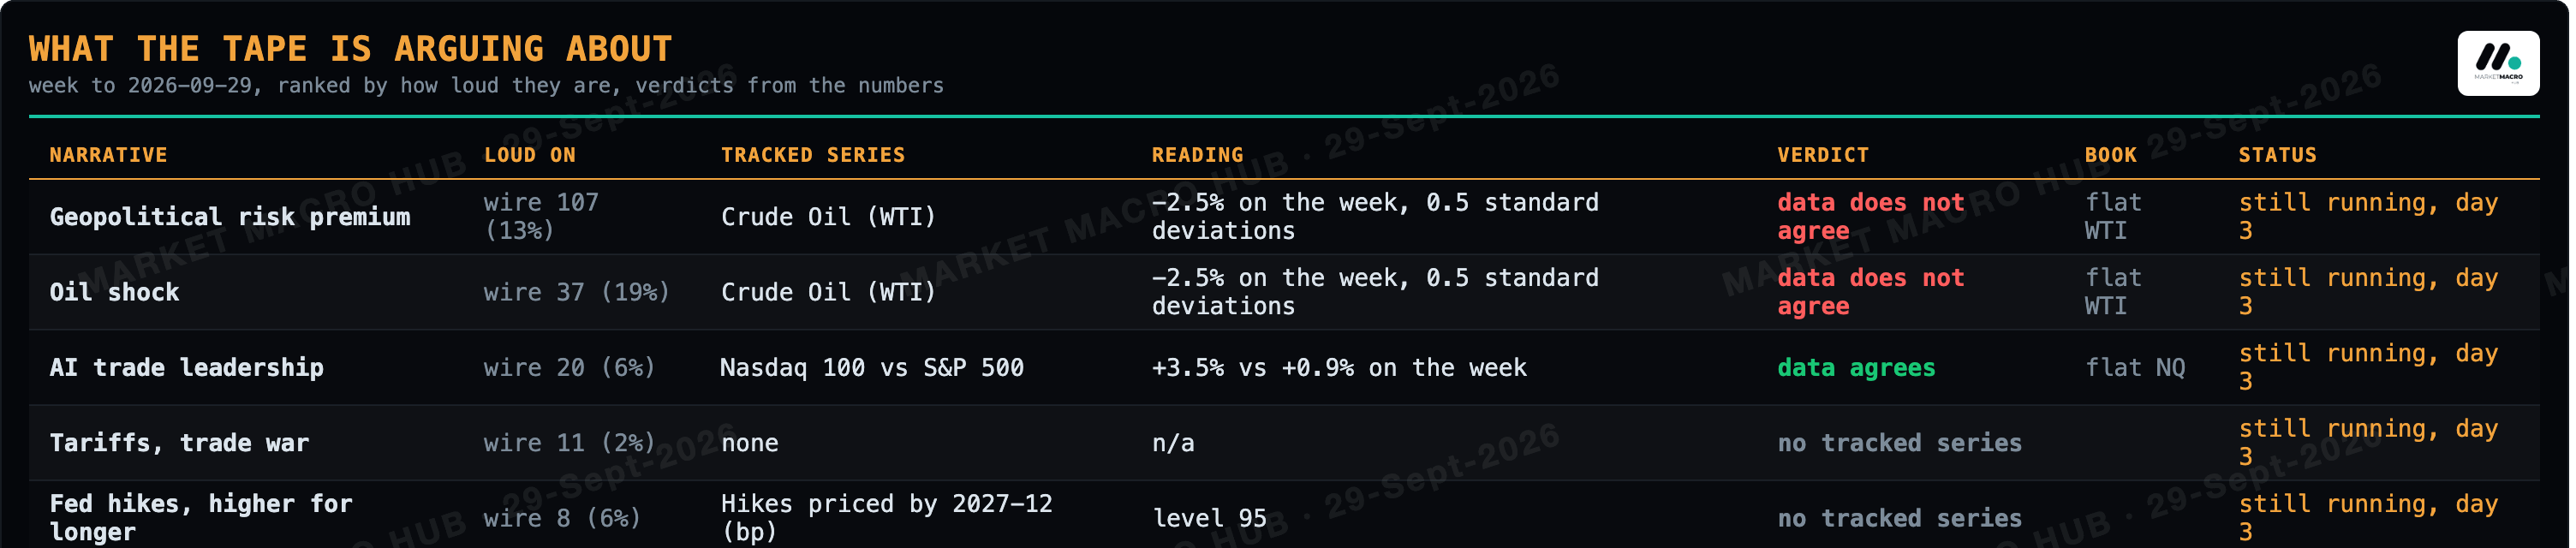
Geopolitical risk premium: data does not agree (Crude Oil (WTI) -2.5% on the week, 0.5 standard deviations).
Oil shock: data does not agree (Crude Oil (WTI) -2.5% on the week, 0.5 standard deviations).
AI trade leadership: data agrees (Nasdaq 100 +2.6% relative on the week).
Tariffs, trade war: no tracked series.
Fed hikes, higher for longer: no tracked series.
Asset Market Pricing
Sector Attribution
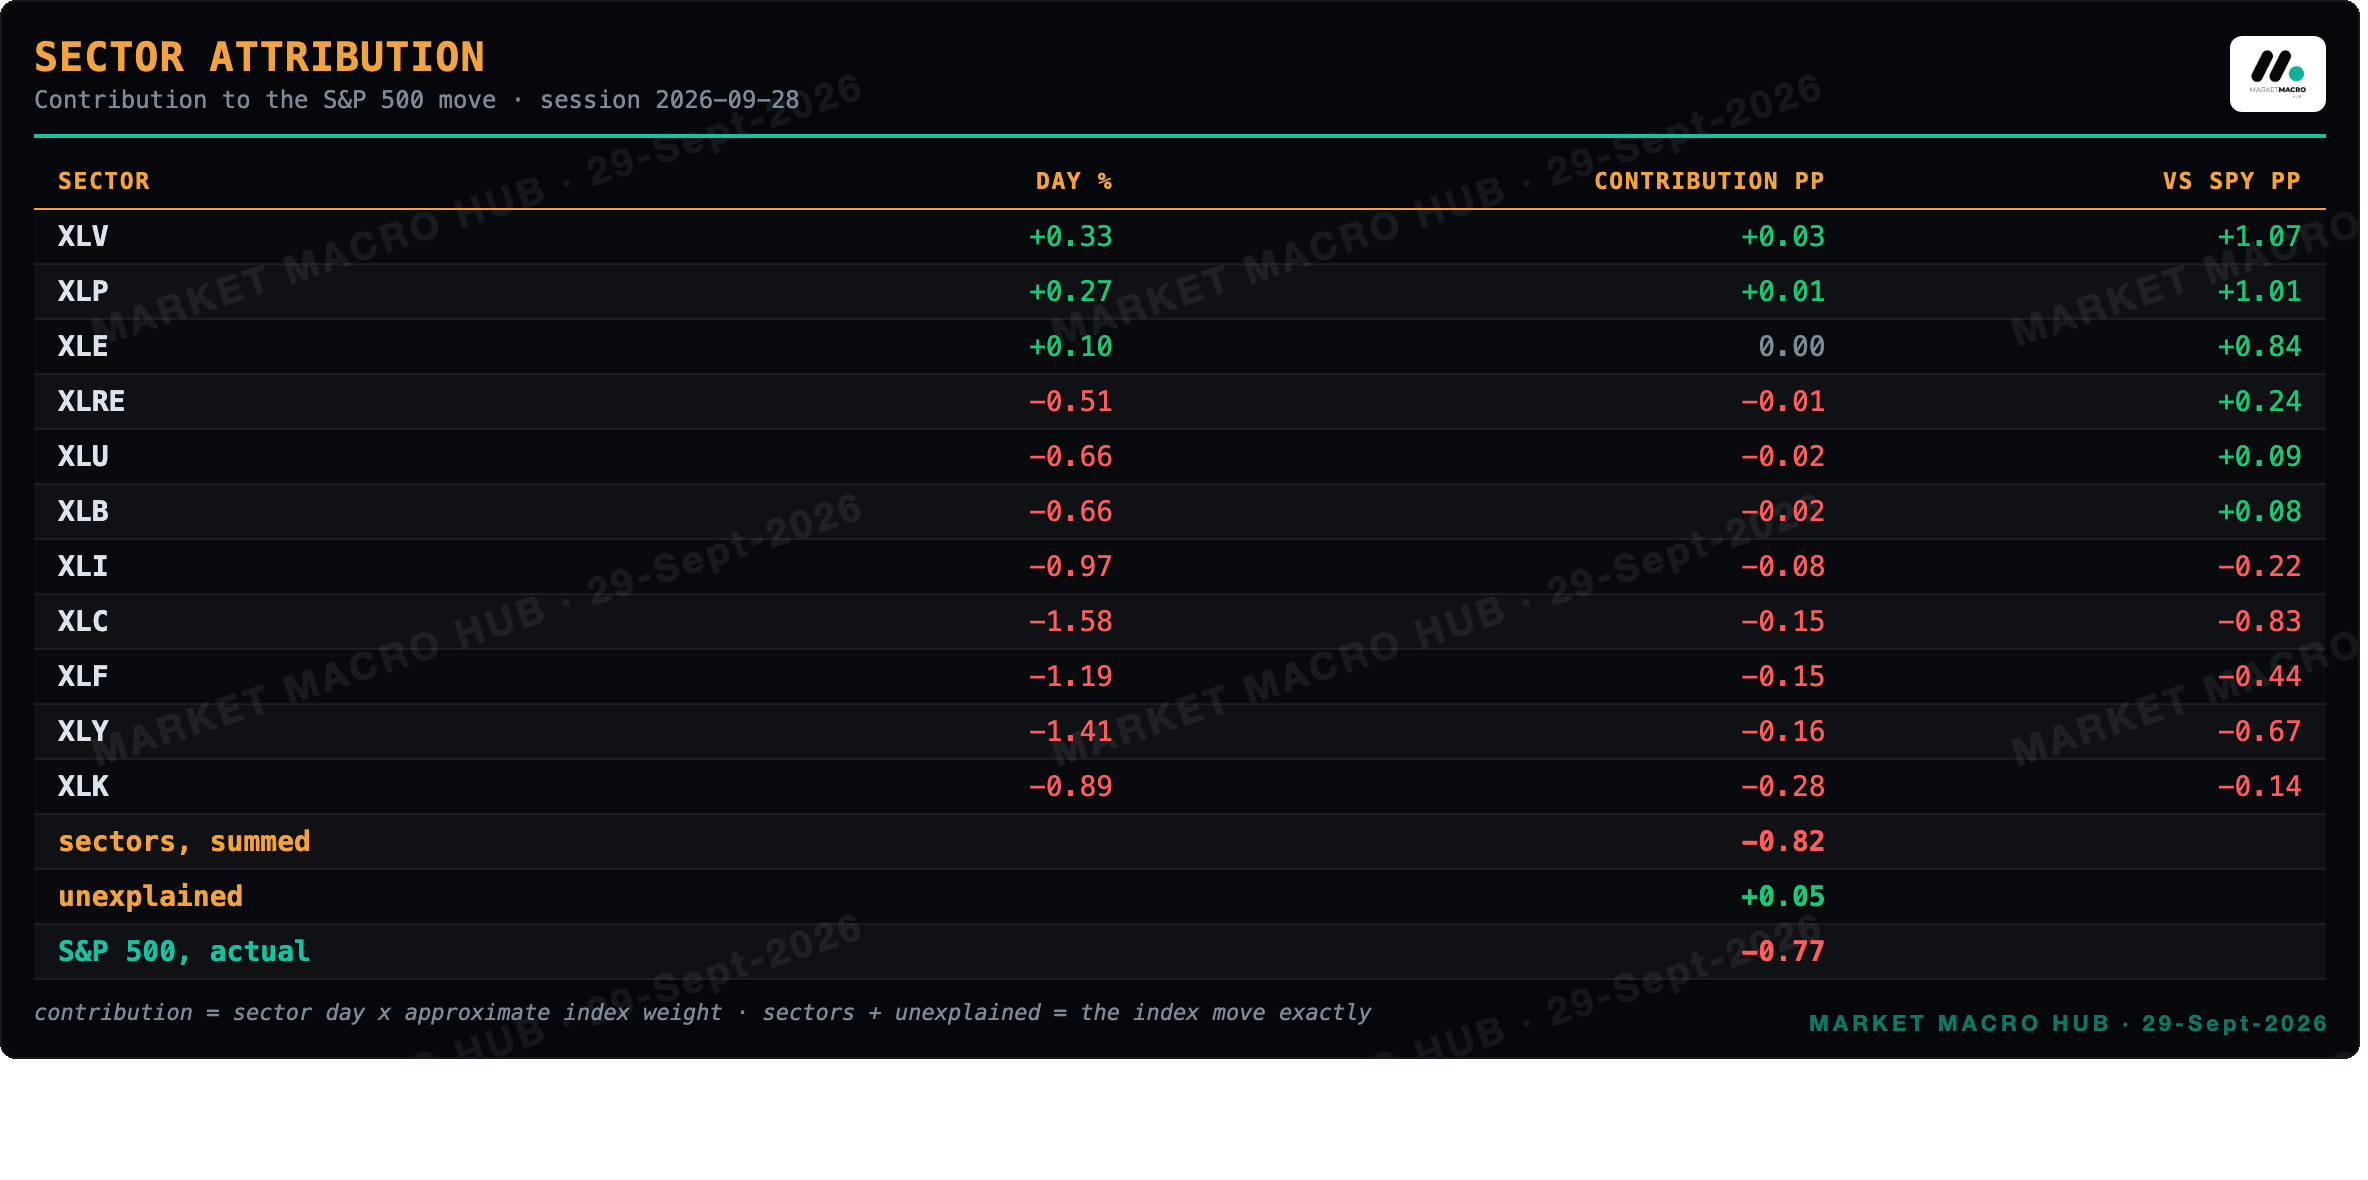
Session 2026-09-28. Sectors plus the unexplained remainder sum to the index move, and the sector split accounts for 94% of it.
Attribution
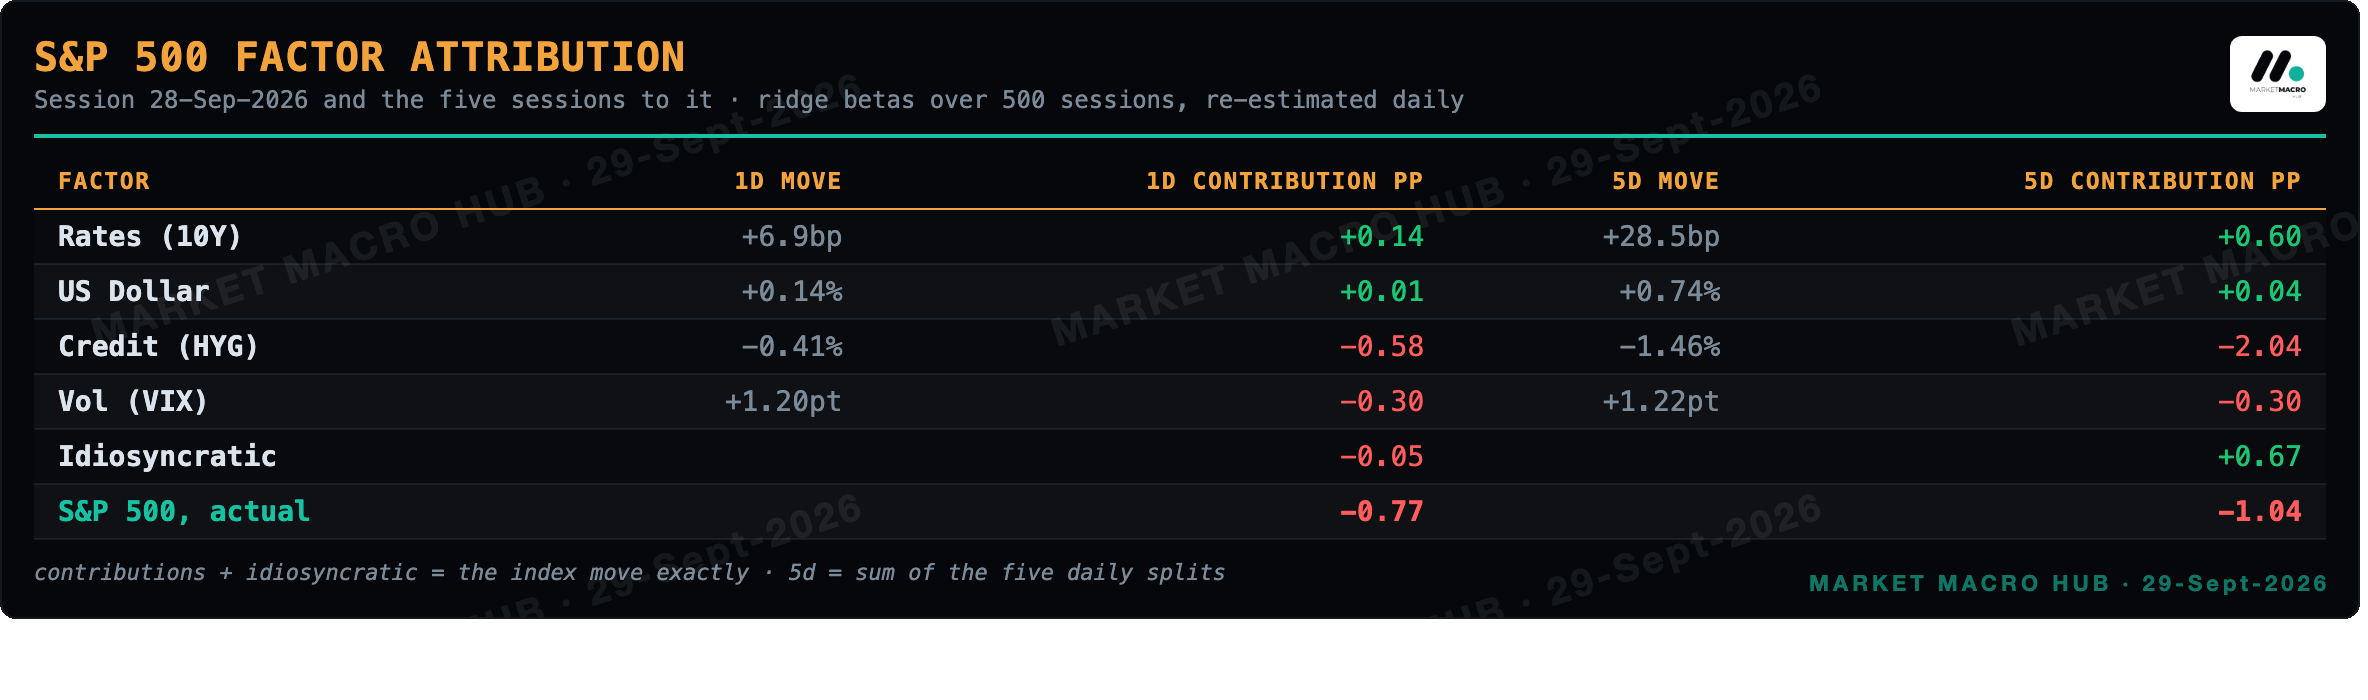
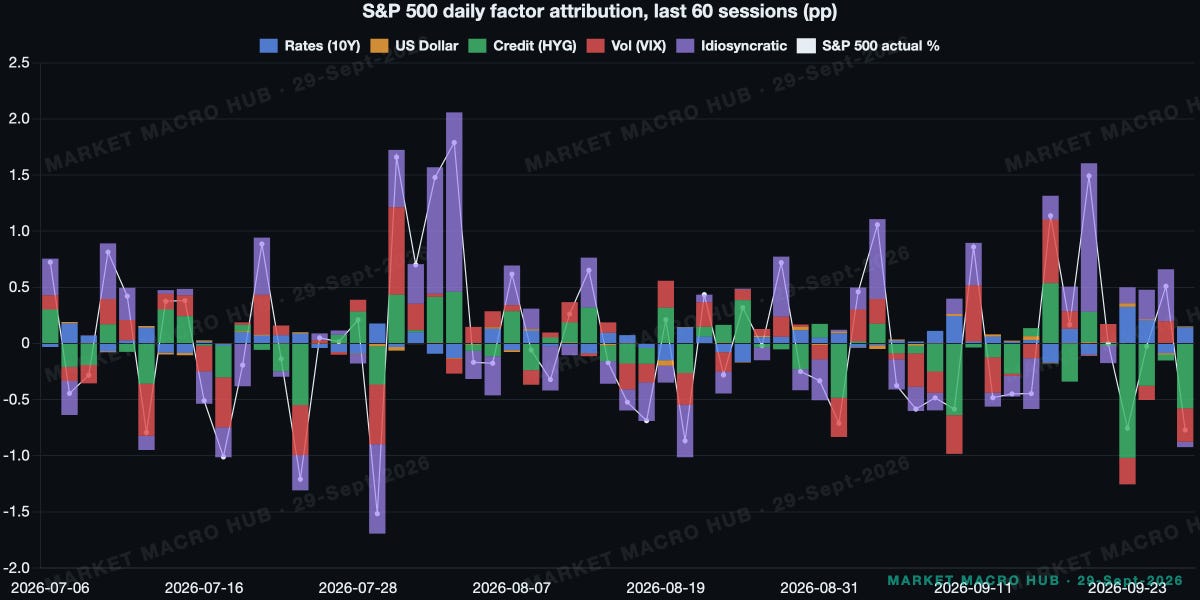
The S&P 500 closed -0.77% on 28-Sep-2026 and the largest driver was credit (HYG) at -0.58pp; over the five sessions to that close the index summed to -1.04% with credit (HYG) the largest driver at -2.04pp.
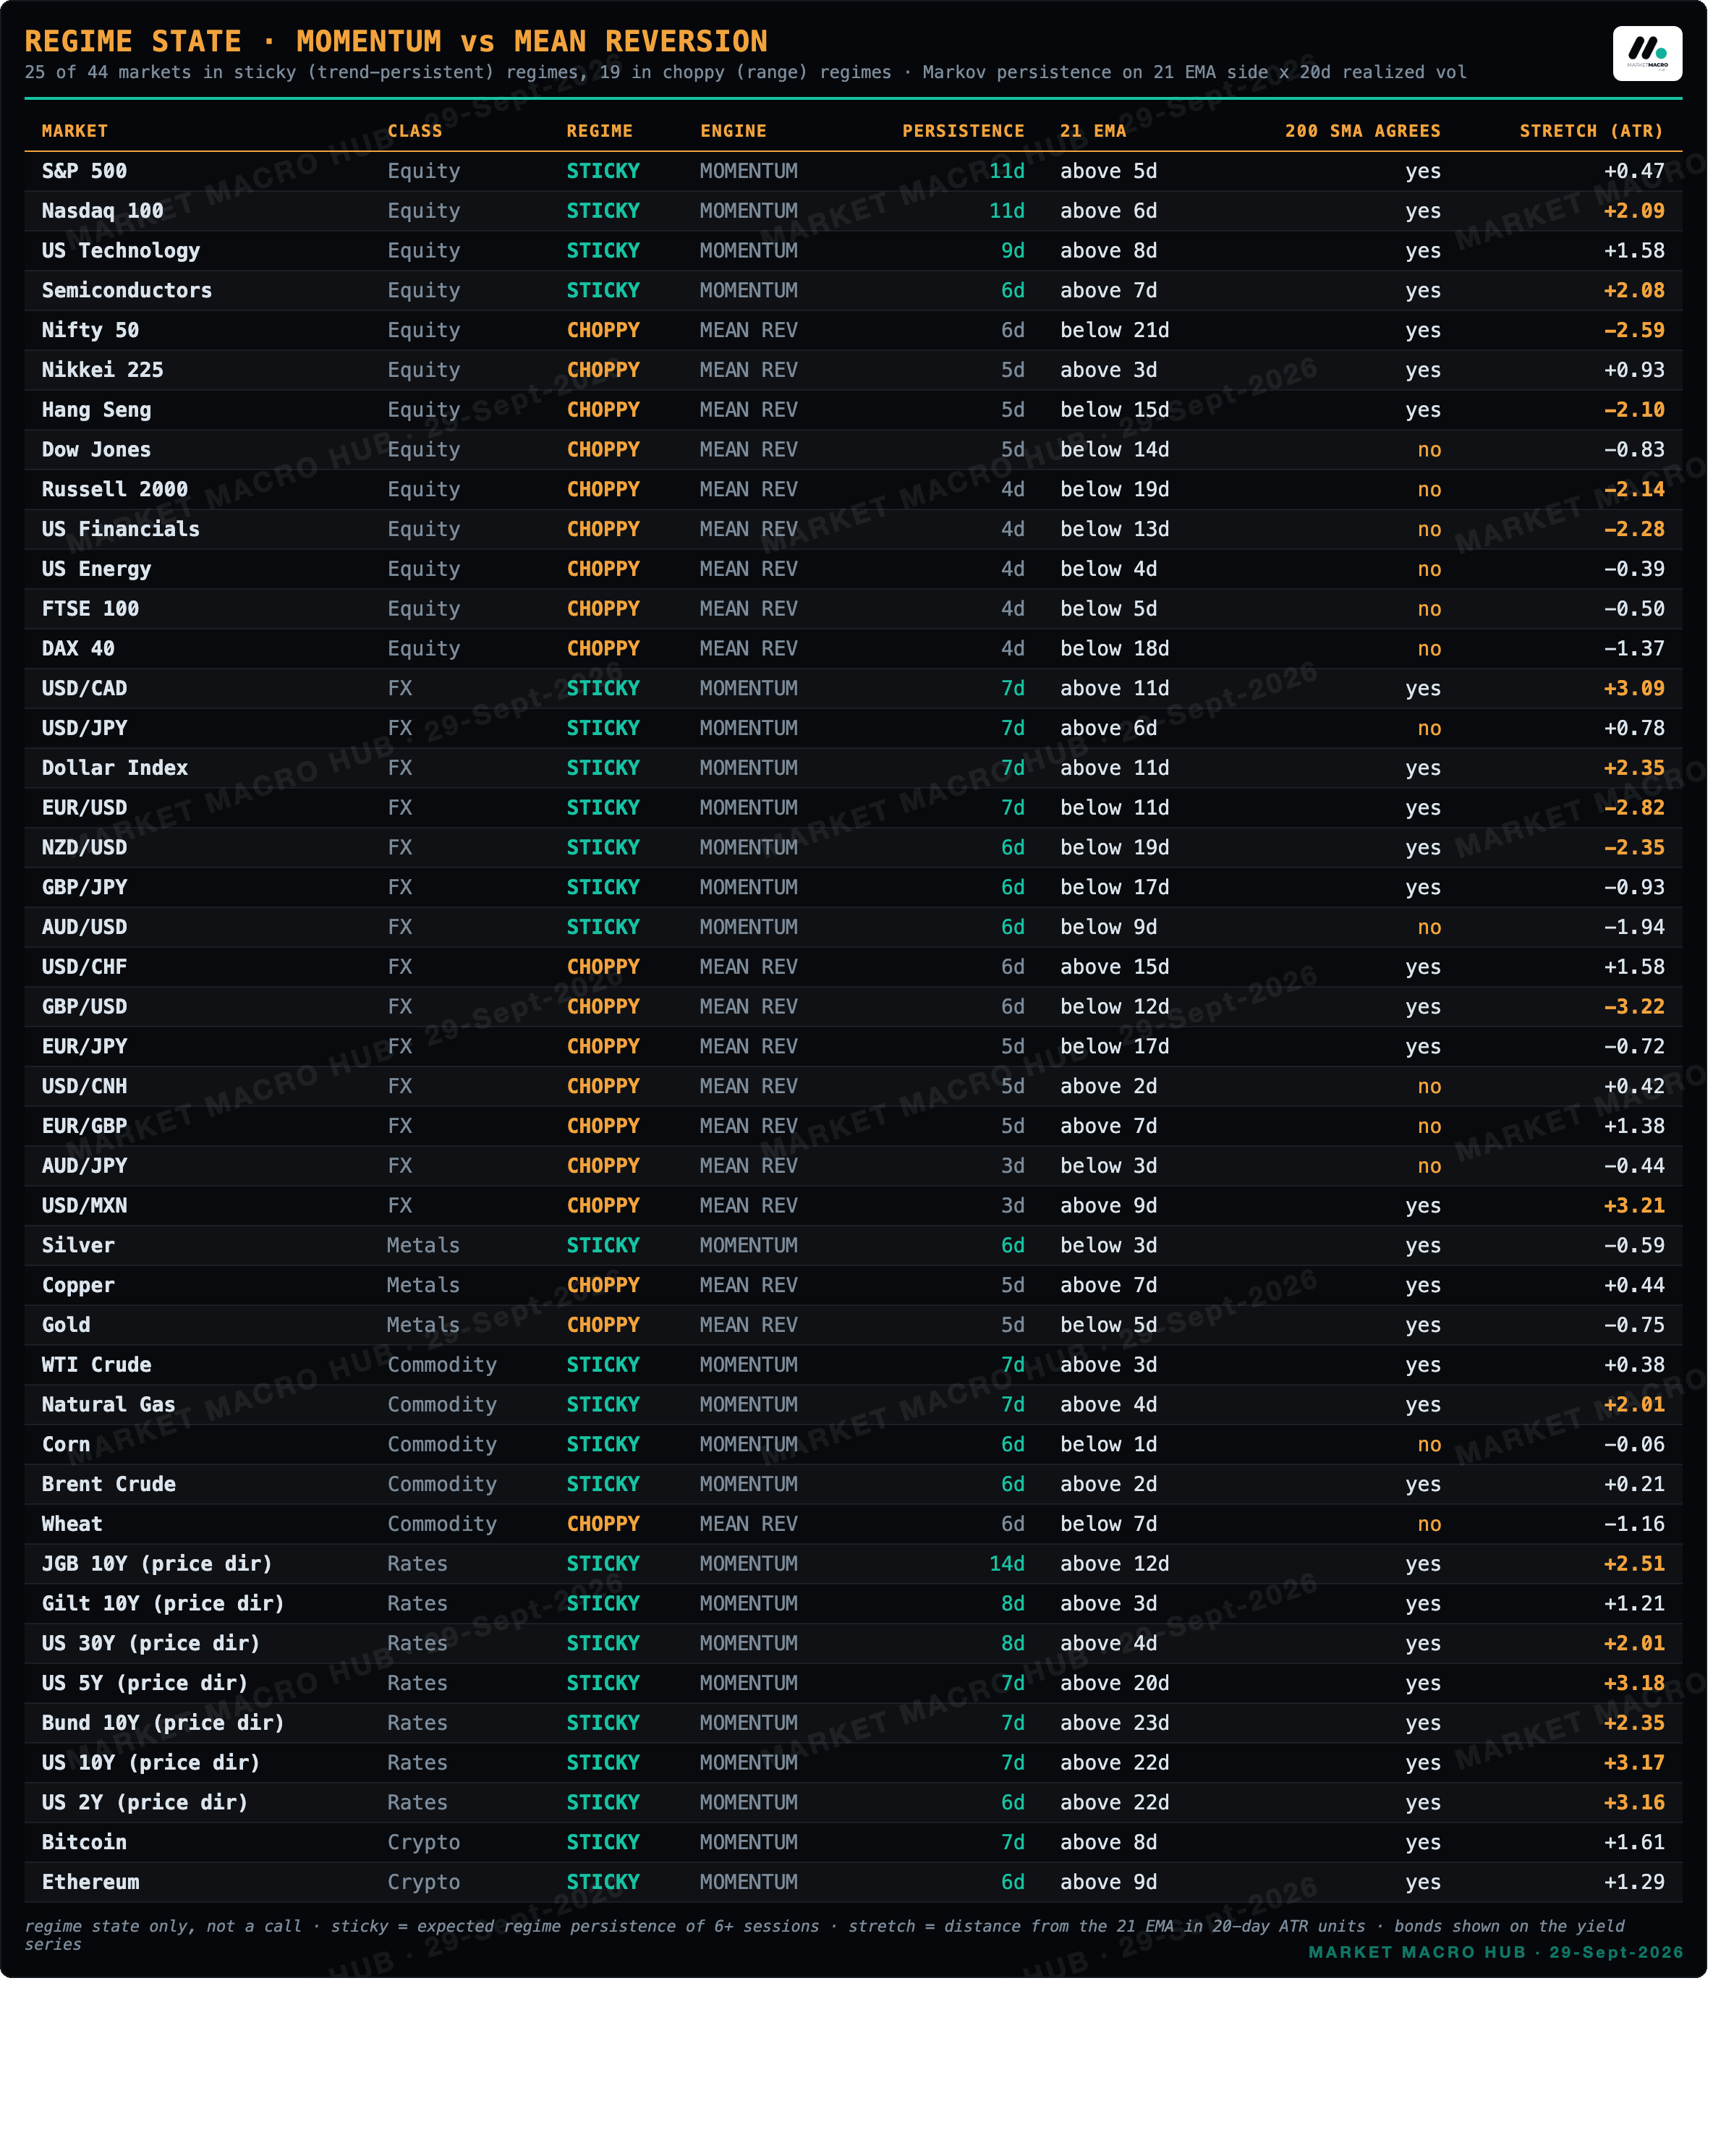
Regime State · Momentum vs Mean Reversion
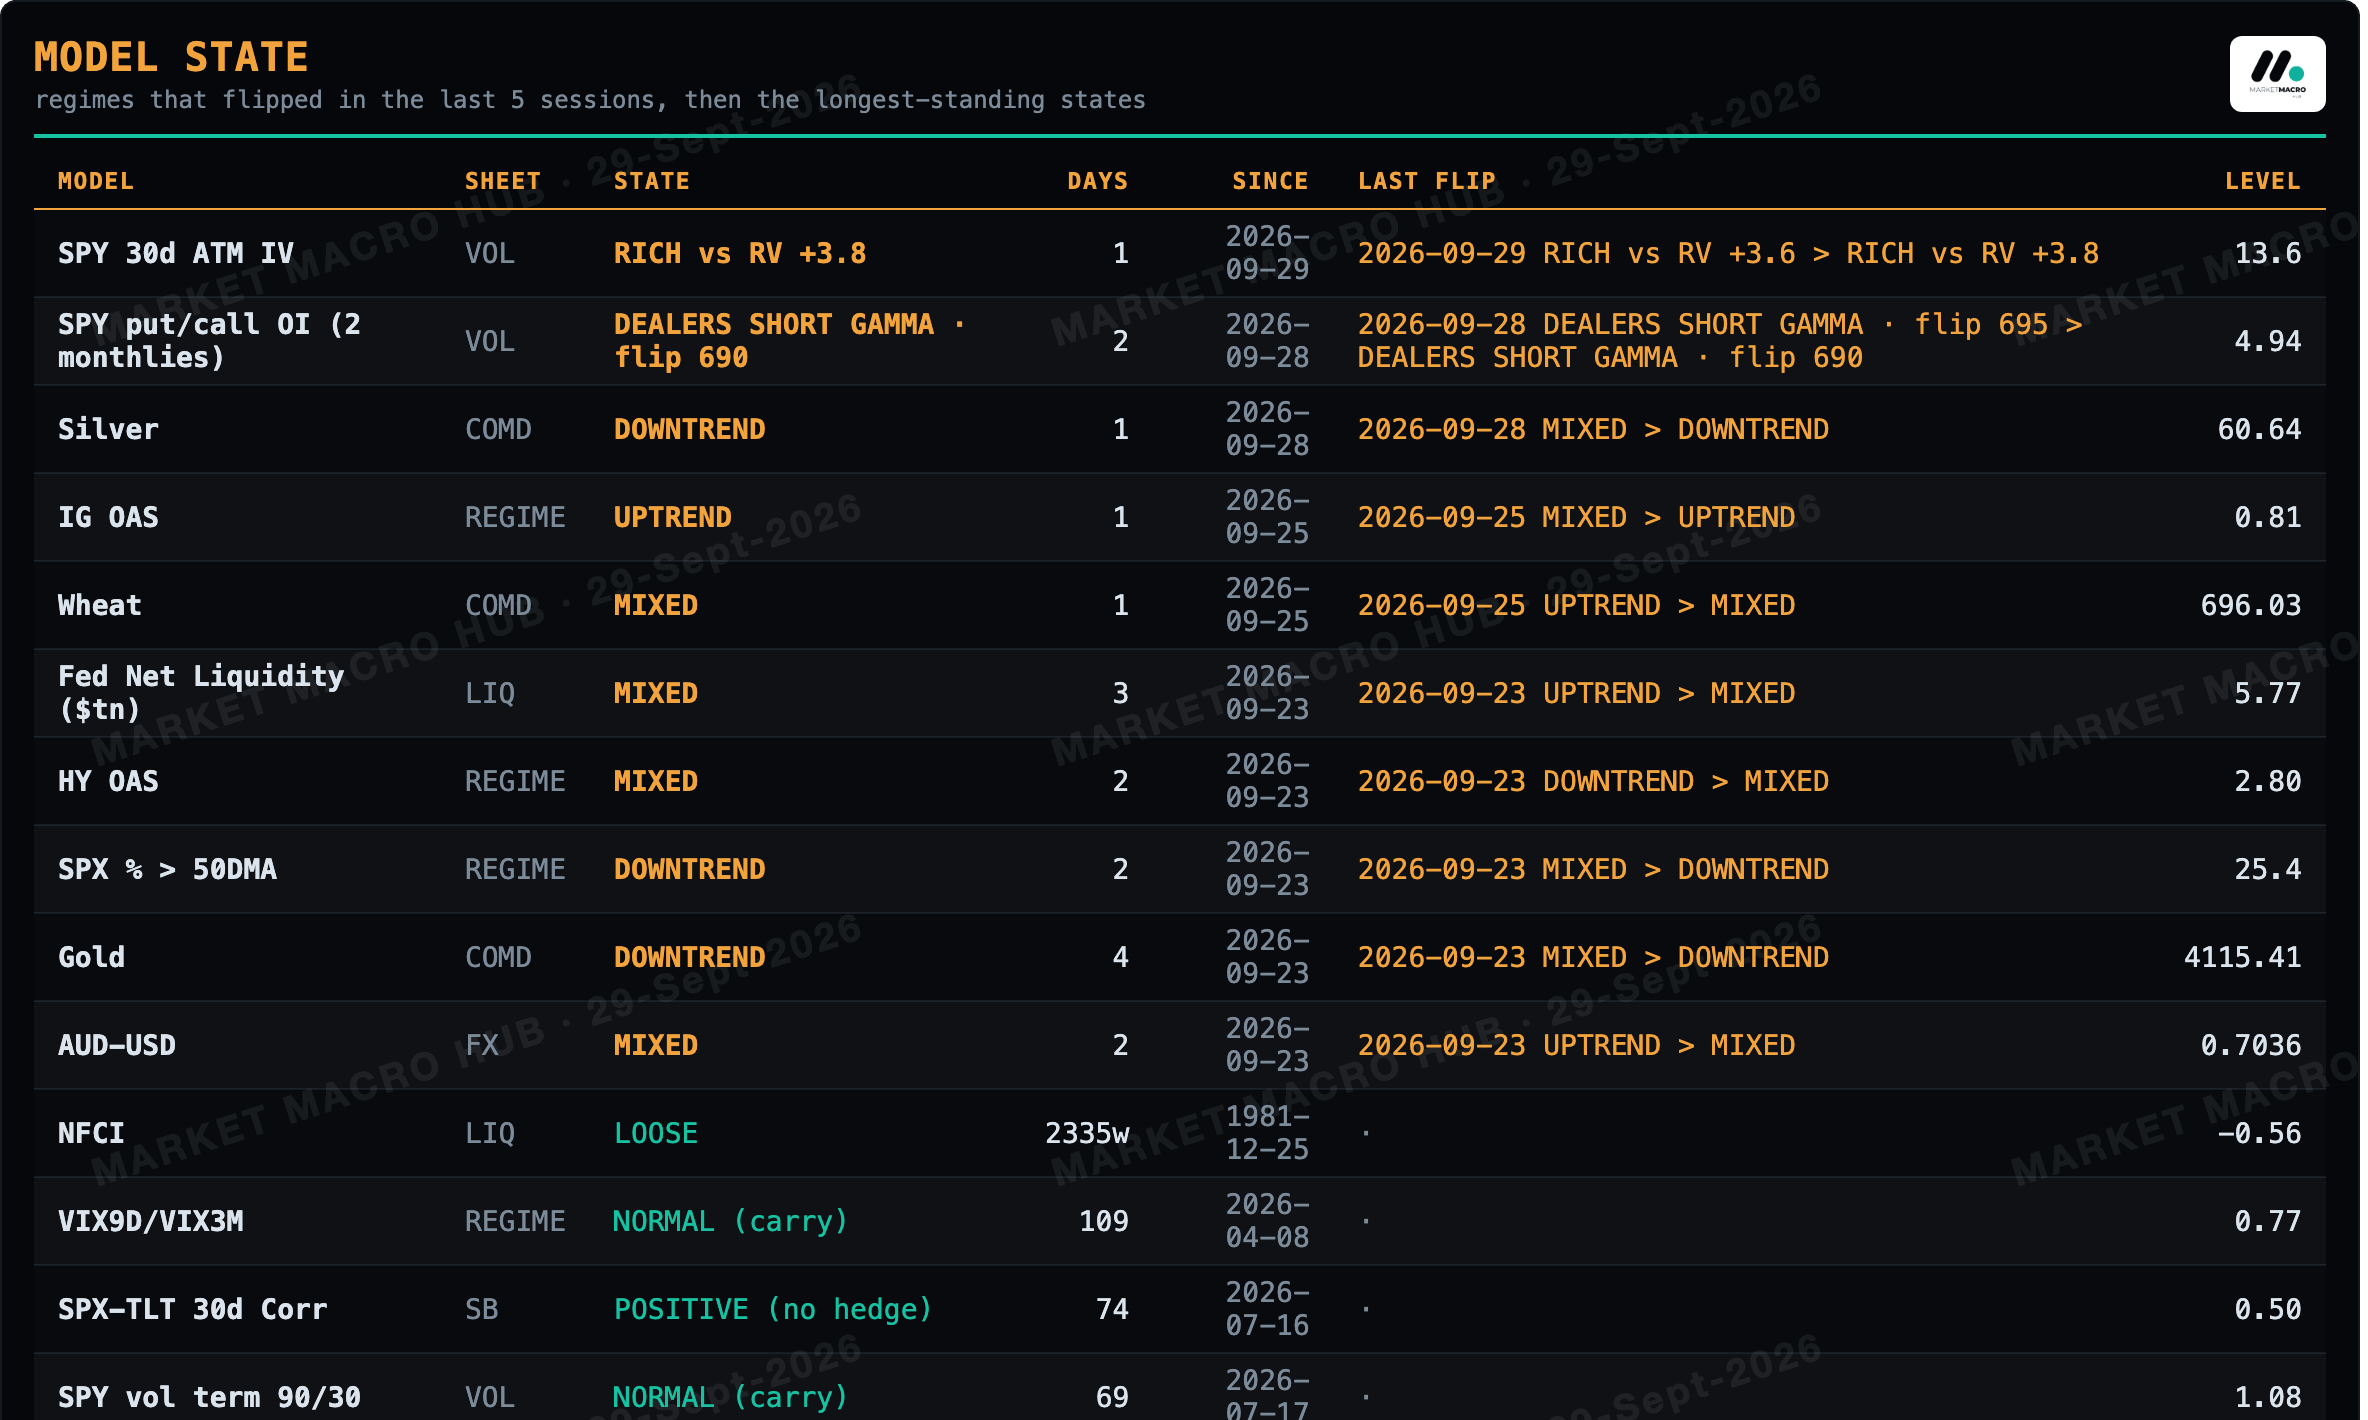
Model State
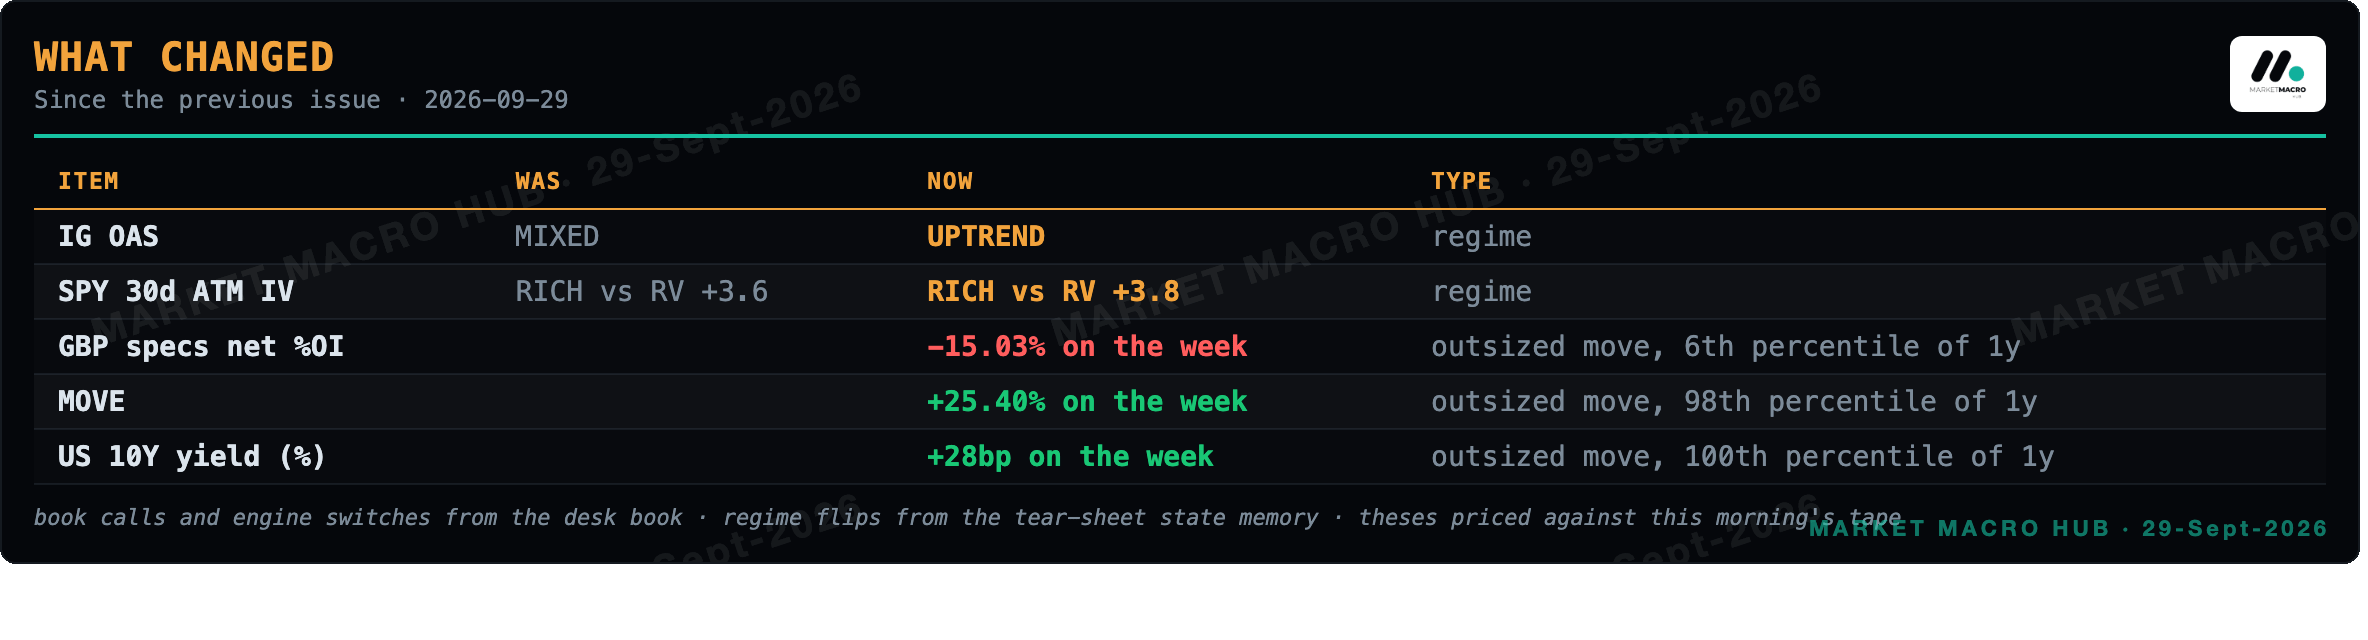
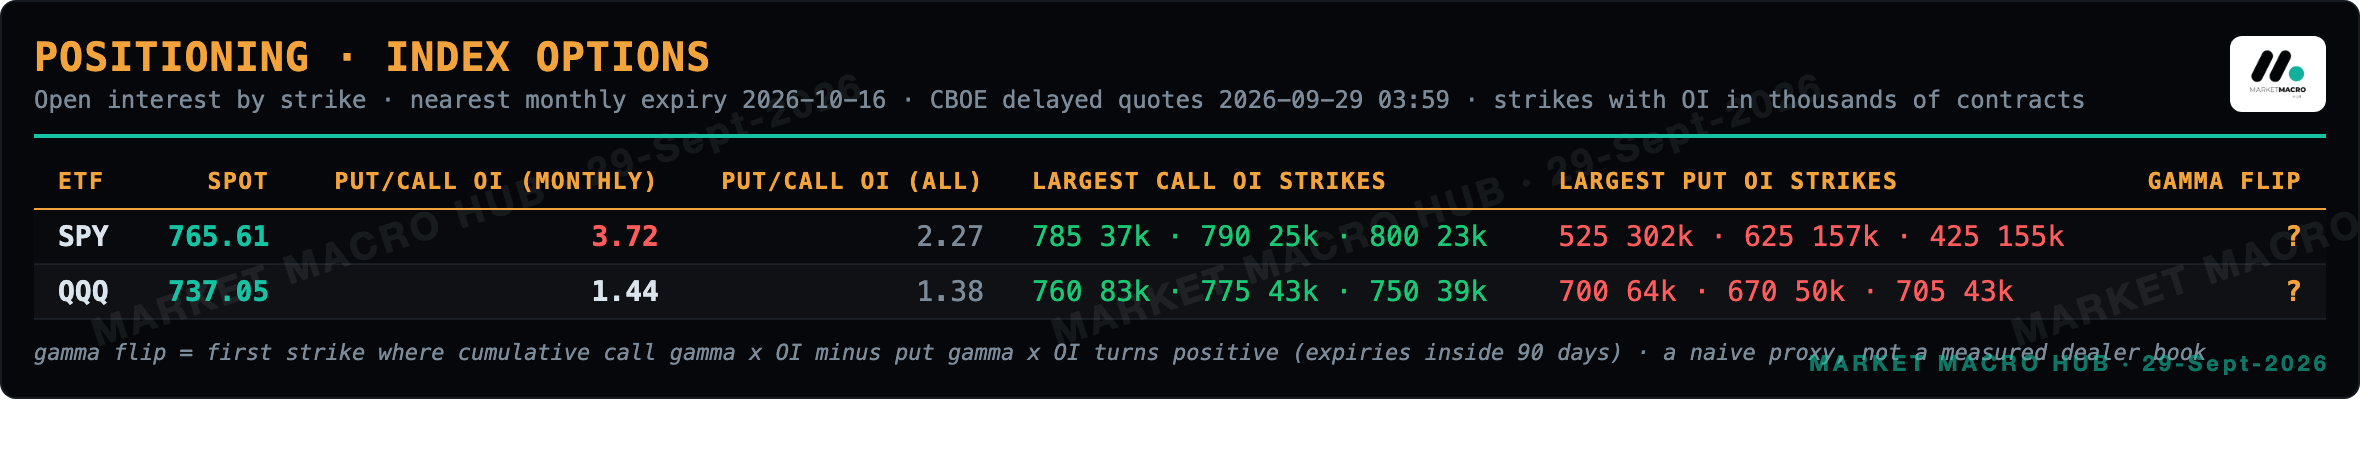
10 model states flipped inside the last five sessions: SPY 30d ATM IV to RICH vs RV +3.8, SPY put/call OI (2 monthlies) to DEALERS SHORT GAMMA · flip 690, Silver to DOWNTREND, IG OAS to UPTREND and more.
Measured Books · E1 to E5
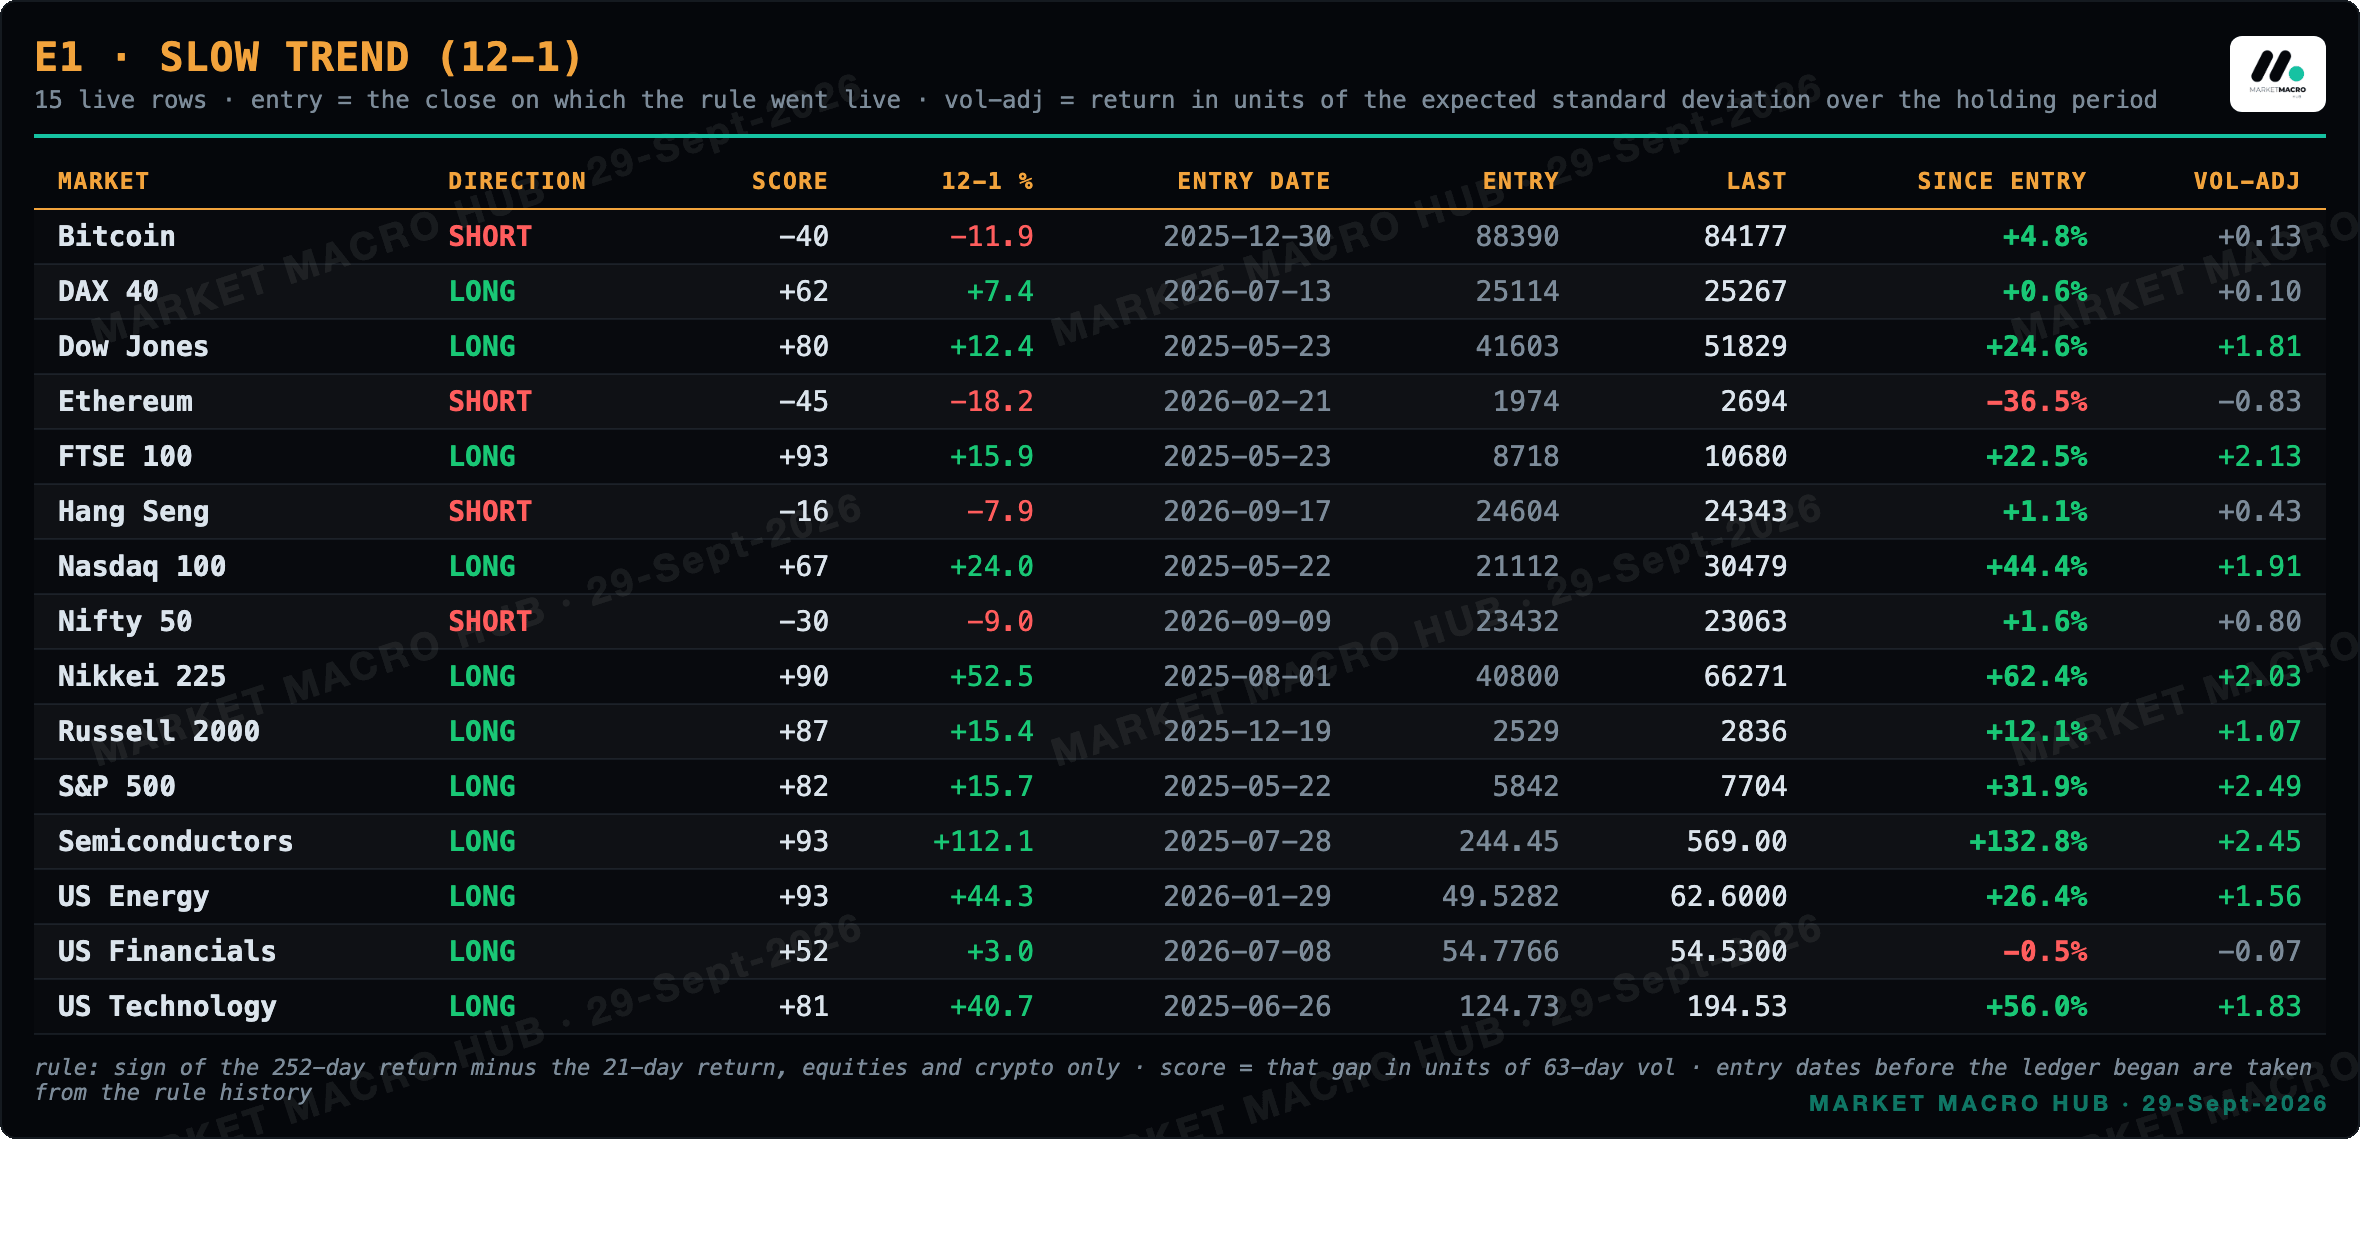
E1 since entry: 15 live rows, 13 positive, average +25.6%, median +1.56 vol-adjusted.
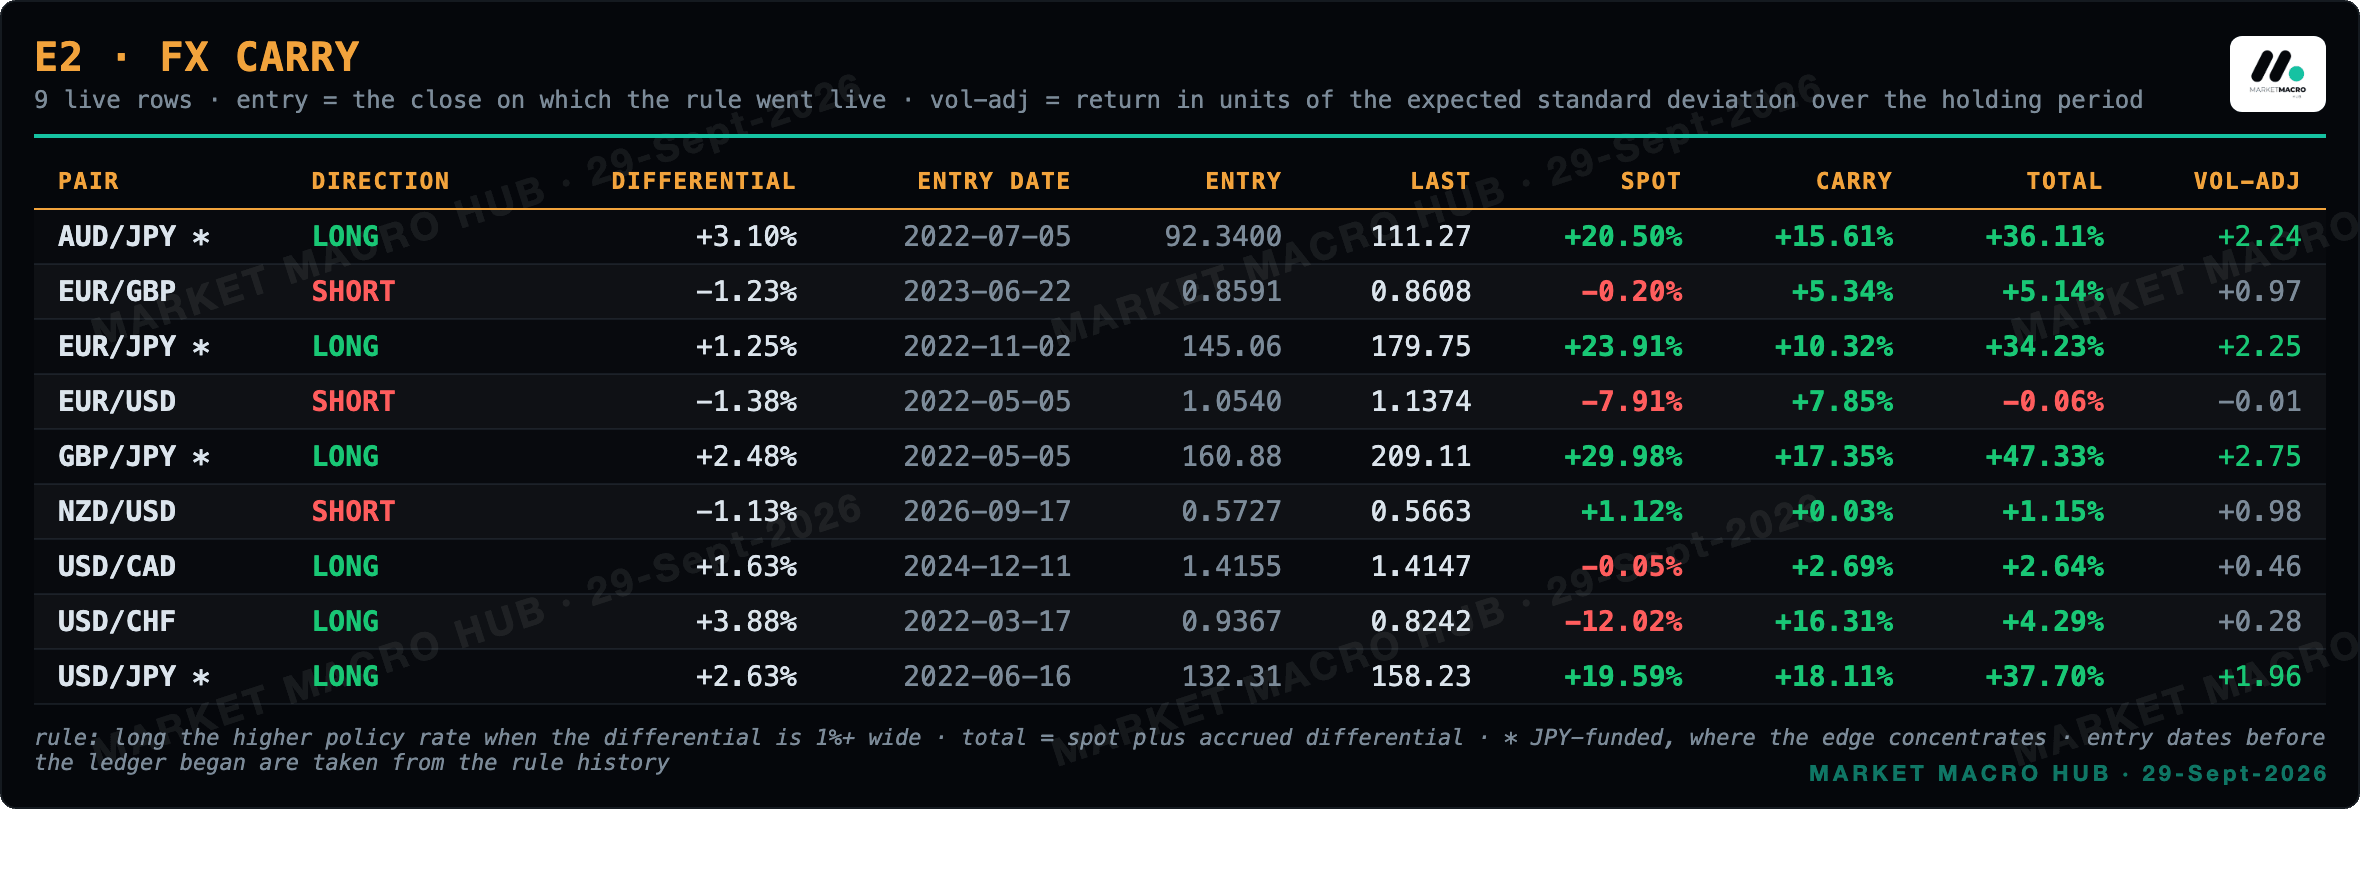
E2 since entry: 9 live rows, 8 positive, average +18.7%, median +0.98 vol-adjusted.
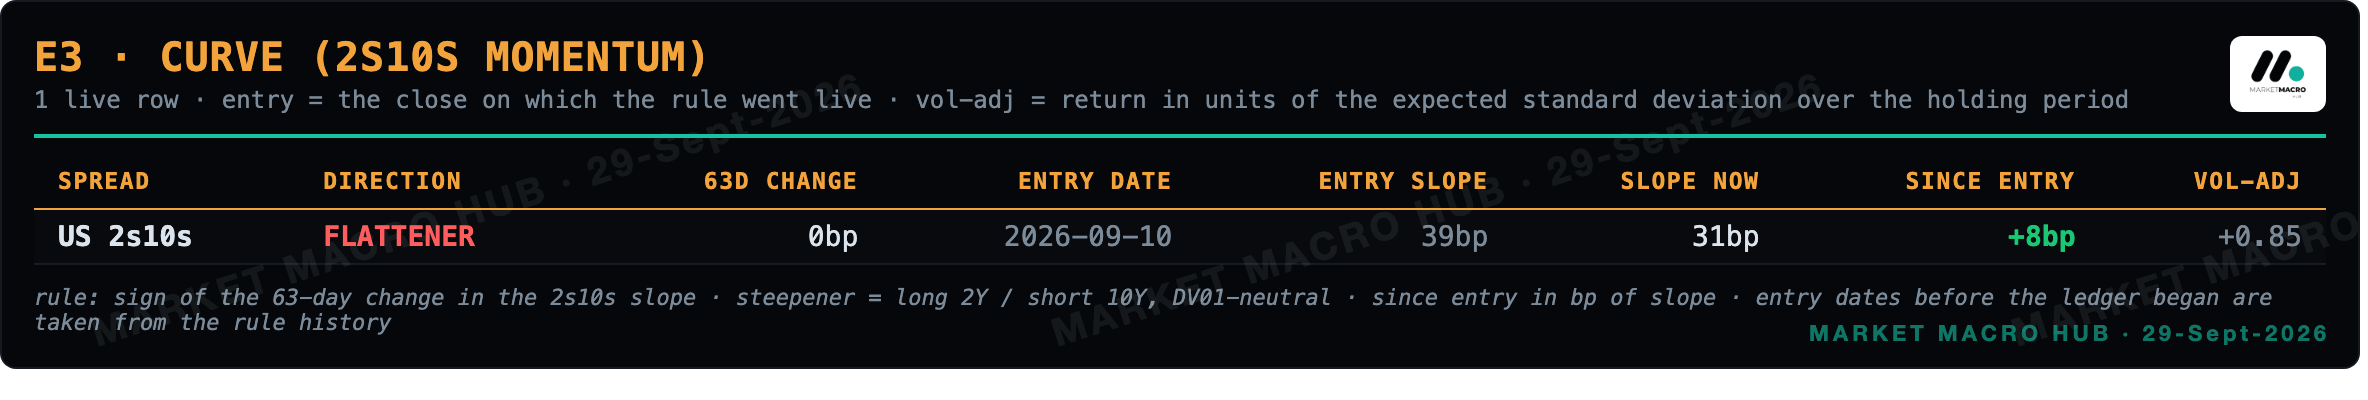
E3 since entry: SHORT US 2s10s from 2026-09-10, +8bp over 10 sessions (+0.85 vol-adjusted).
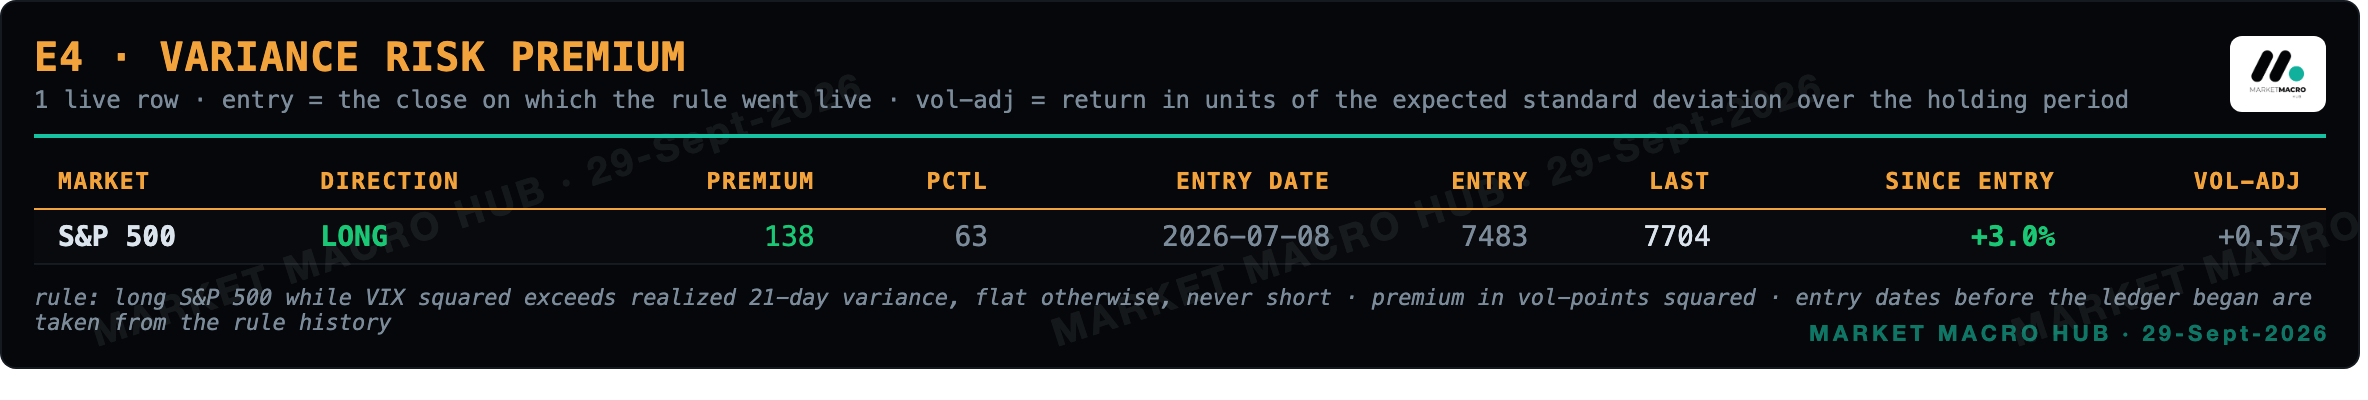
E4 since entry: LONG S&P 500 from 2026-07-08, +3.0% over 55 sessions (+0.57 vol-adjusted).
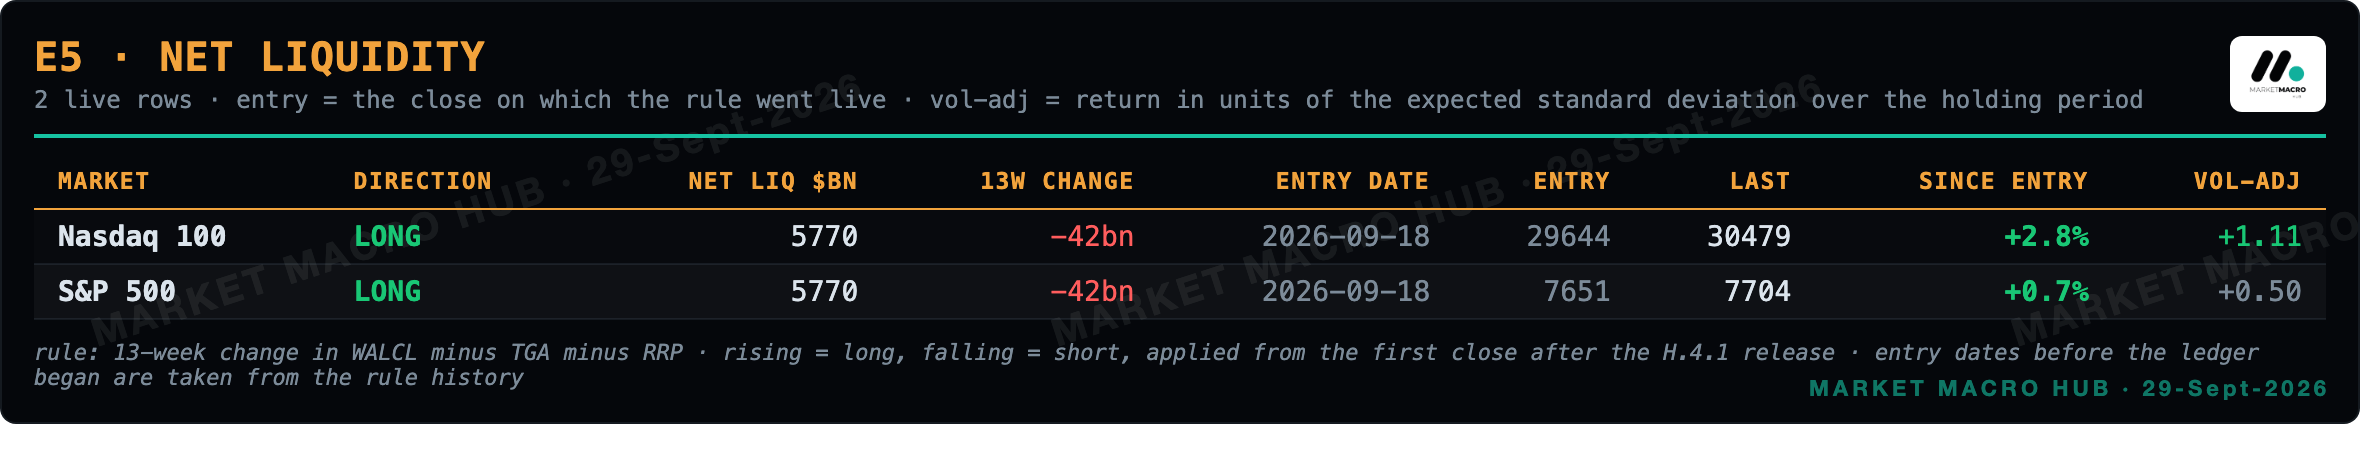
E5 since entry: 2 live rows, 2 positive, average +1.8%, median +1.11 vol-adjusted.
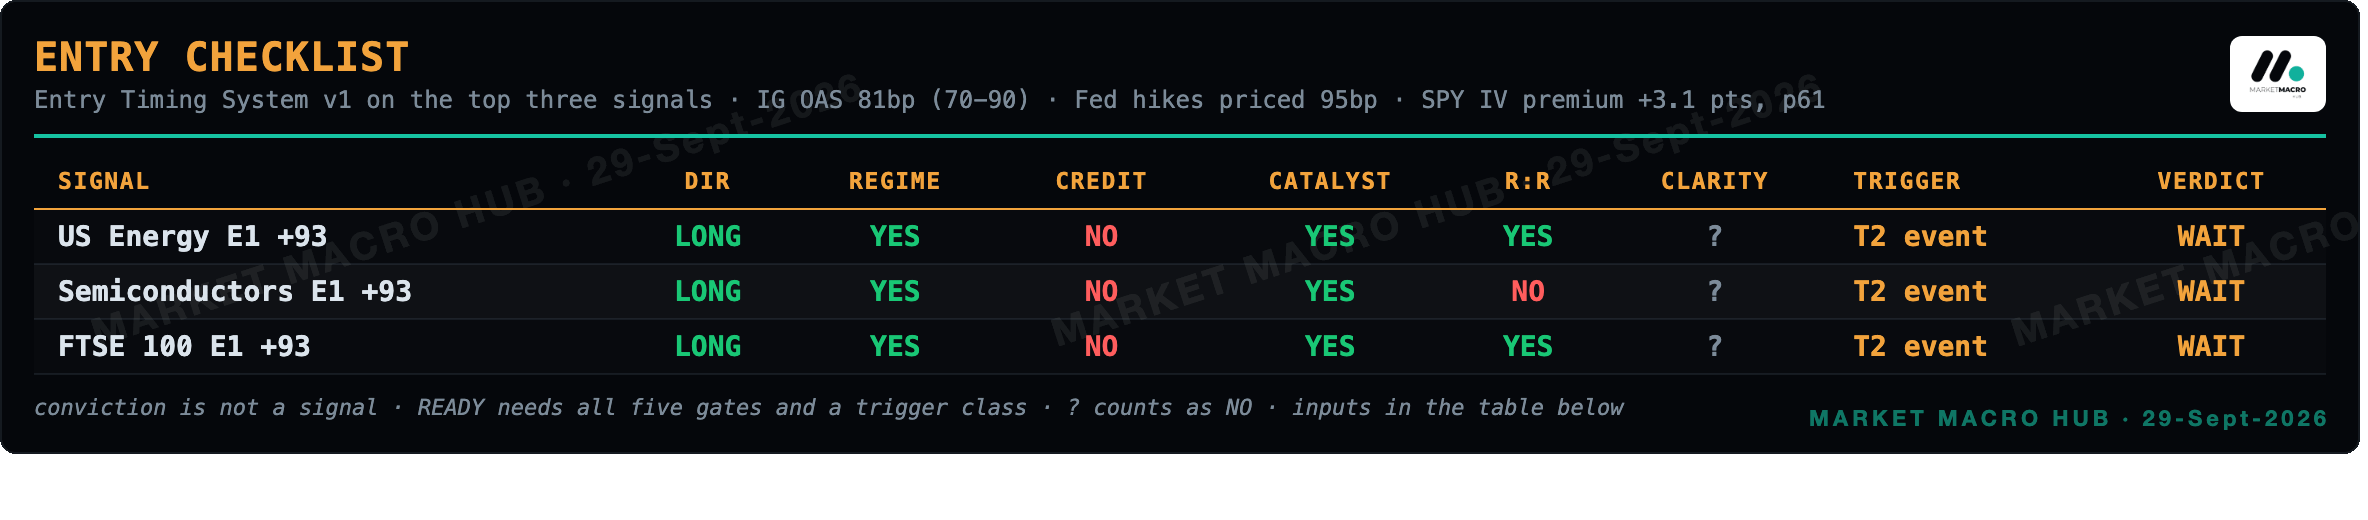
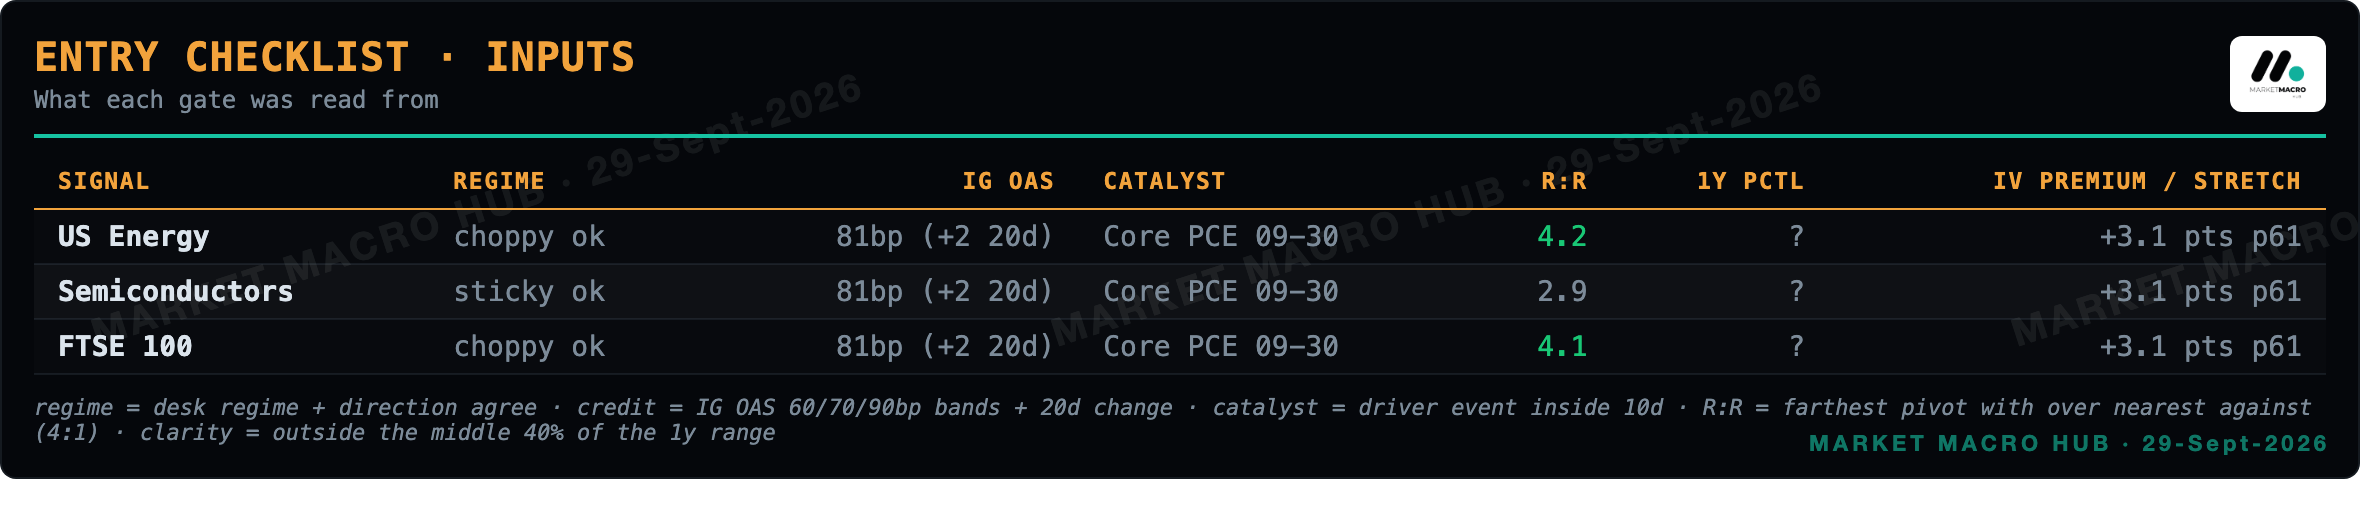
Entry Checklist
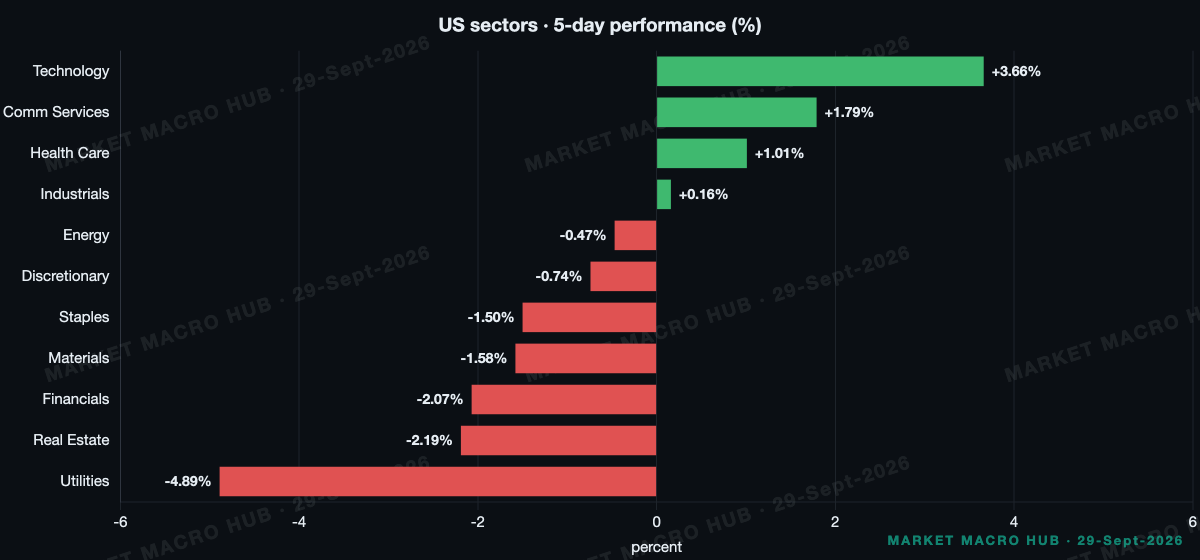
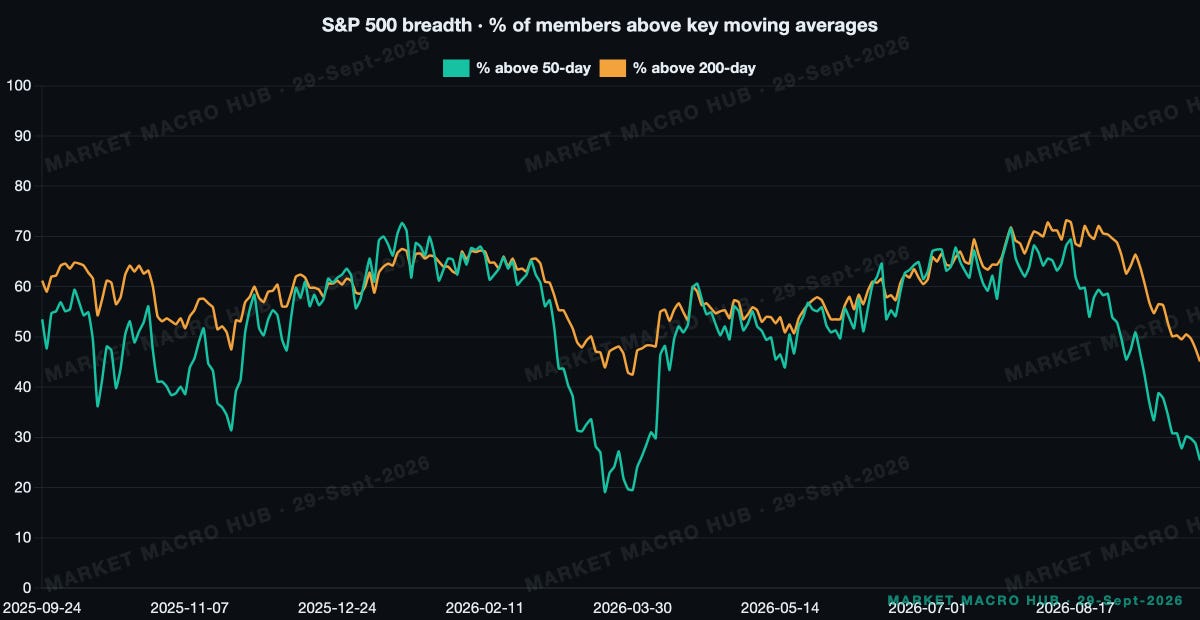
Sector Snapshot & Breadth
Scenarios for the Week
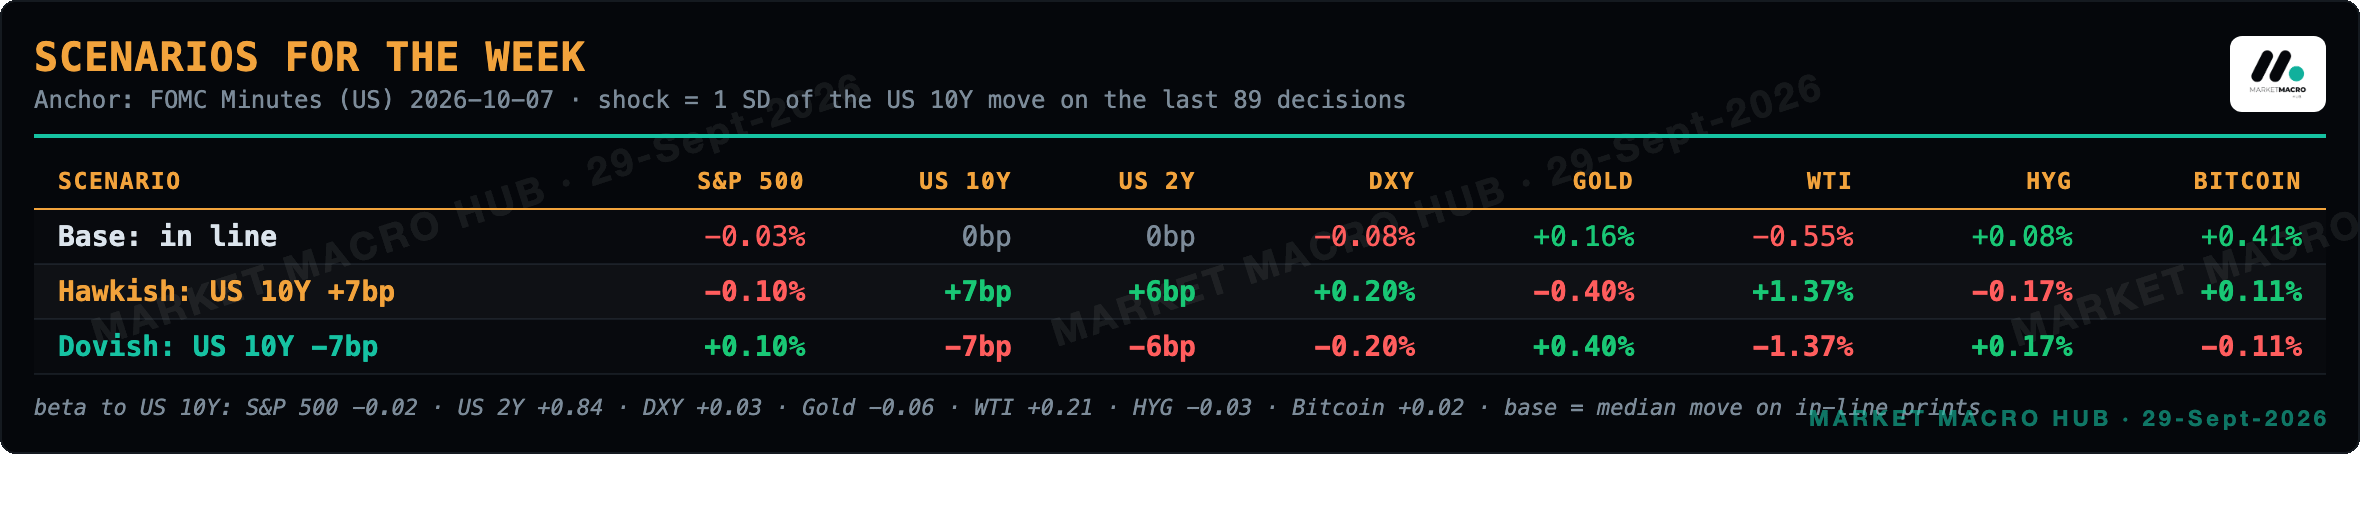
Expected moves are conditional means from 2-year betas to the anchor times a 1-standard-deviation event-day shock, not forecasts.
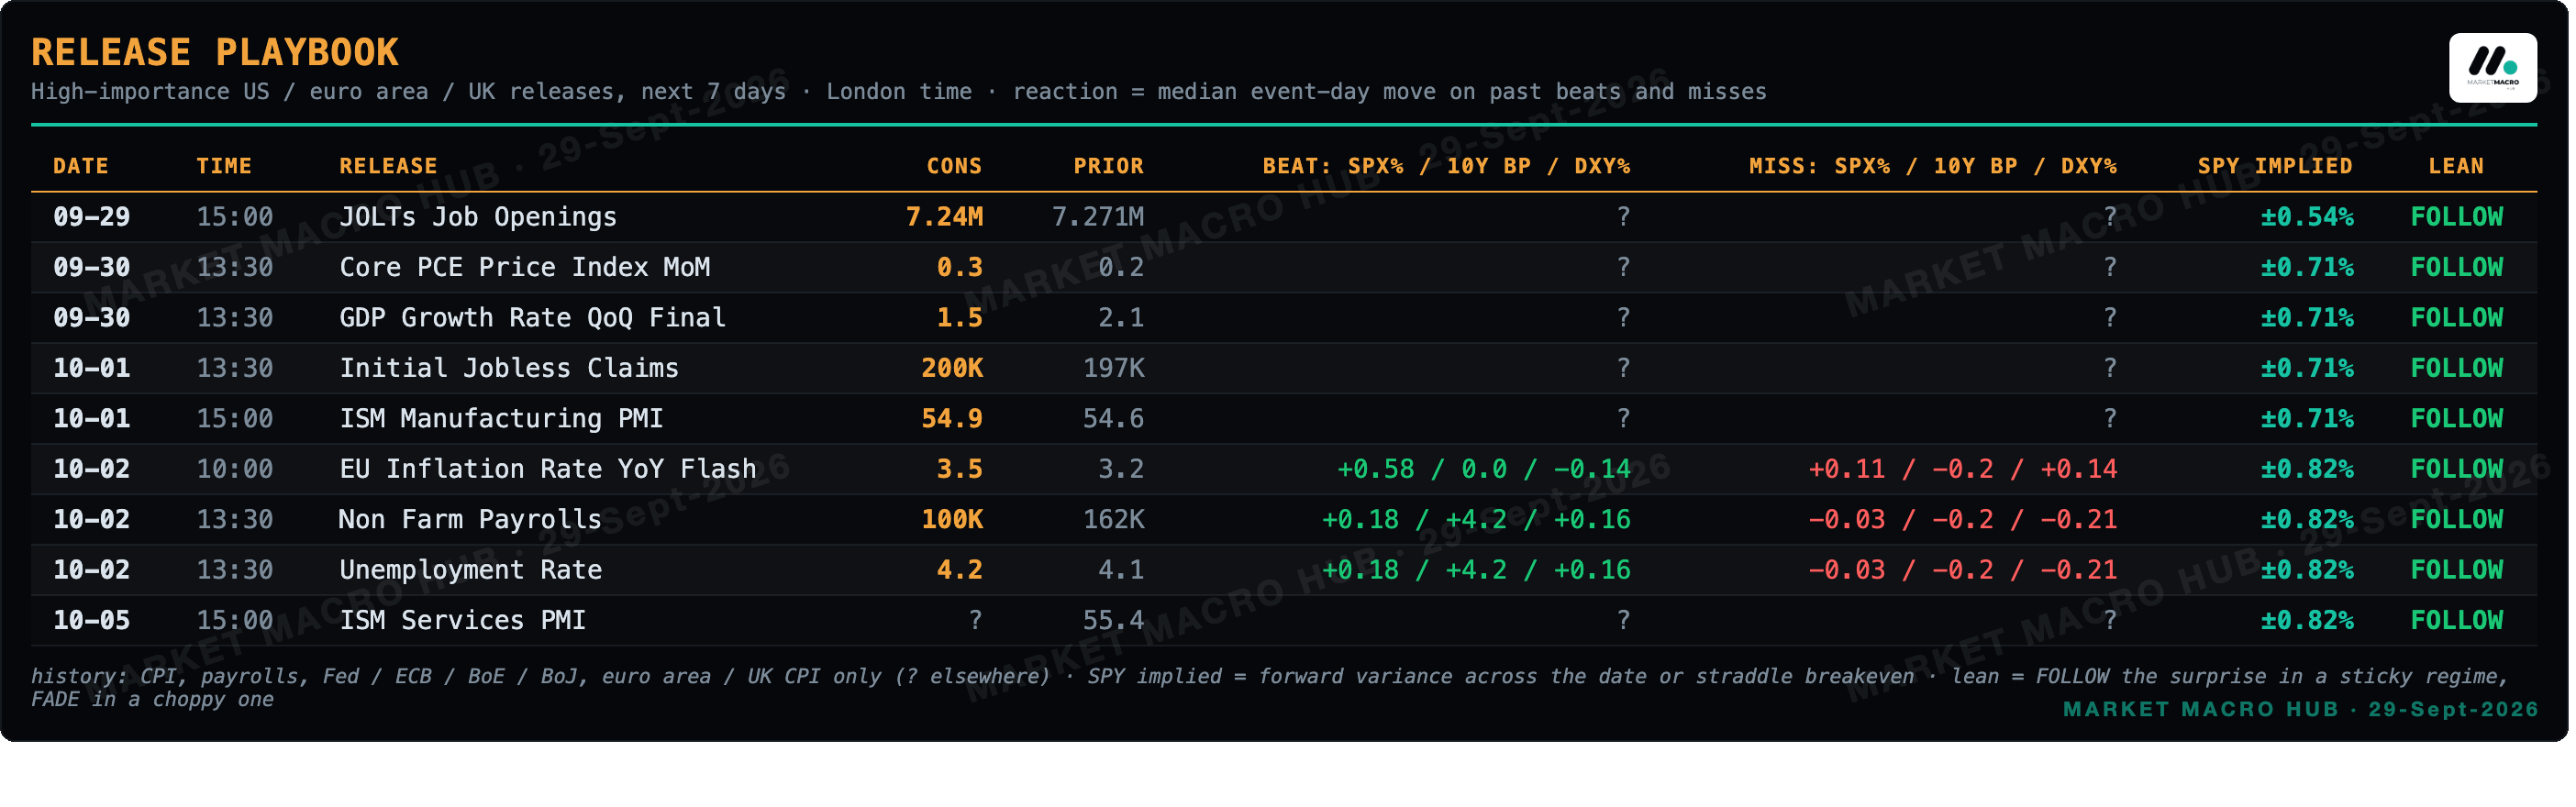
Release Playbook
Main Developments in Macro
WTI +1.8%, BRENT +2% AS IRAN HORMUZ STANDOFF DRAGS ON, CONFLICTING NUCLEAR HEADLINES
IRAN FM ARAGHCHI: HORMUZ REOPENING CONTINGENT ON CONDITIONS; US SOURCE SAYS CHANCE OF DEAL "EXTREMELY SLIM"
TRUMP: WILL WIN IRAN WAR SOON, GAS PRICES TO COME DOWN, INFLATION ERADICATED AFTER WAR
FED'S COOK (VOTER): EXPECTS CONTINUED INFLATION PRESSURE FROM AI AND MIDDLE EAST, LABOUR MARKET CAN HANDLE RATE INCREASE
RBA HIKED AS EXPECTED, STUCK TO HAWKISH SCRIPT; NIKKEI -1.4% LEADS APAC LOWER
US IMPORT BAN ON RANGE OF CANADIAN PRODUCTS TOOK EFFECT AT MIDNIGHT
HASSETT: PRODUCTIVITY GROWTH AROUND 2.5%, GDP BASE CASE NEAR 4%
The data underneath is not soft. New Home Sales beat at 0.684 and jumped 6.4% on the month, and jobless claims printed 197 against 201 expected, so the labour and housing prints refuse to crack. Durable goods ex-transport missed at 0.3% against 0.6%, but the headline beat, so I read the growth backdrop as firm enough to carry the hikes the strip is pricing.
Cross-Asset Read
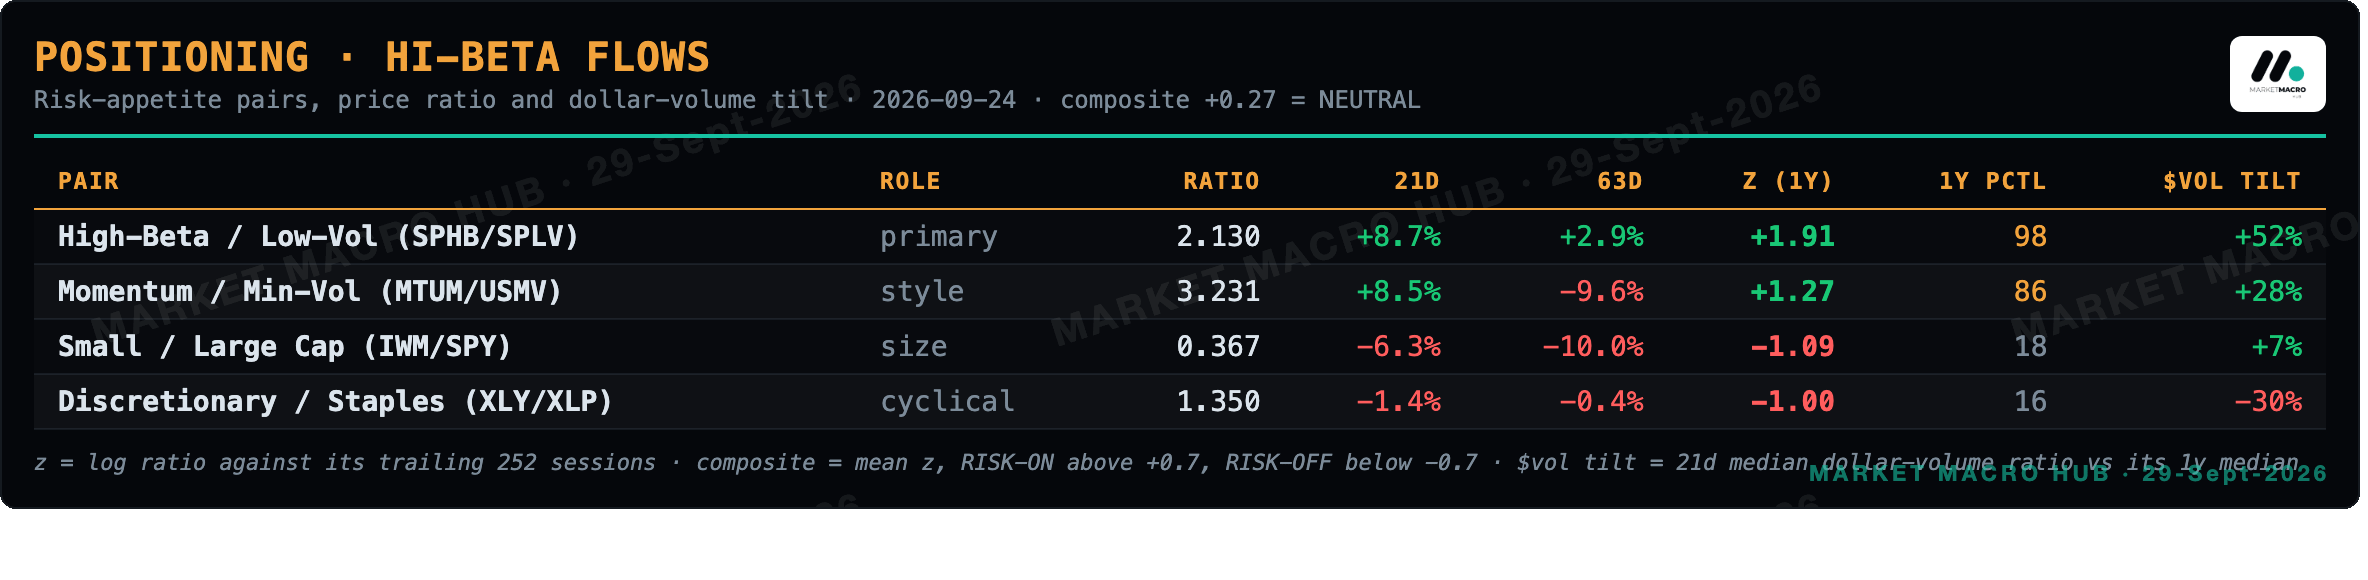
The selling on the tape was led by tech and discretionary, XLK cost the index -0.28pp and XLY another -0.16pp, with defensives, health care and staples the only green. That reads as a rate-sensitivity story given the yield move.
The correlation flagged BIG SHIFT is SPX versus Bitcoin, up to 0.45 from 0.09. Bitcoin is trading like a risk asset again, so it no longer diversifies an equity book the way it did a month ago. Gold versus the 10-year also flipped harder negative at -0.44, so higher yields are now actively pressuring gold, which fits the -5.23% weekly move flag still live.
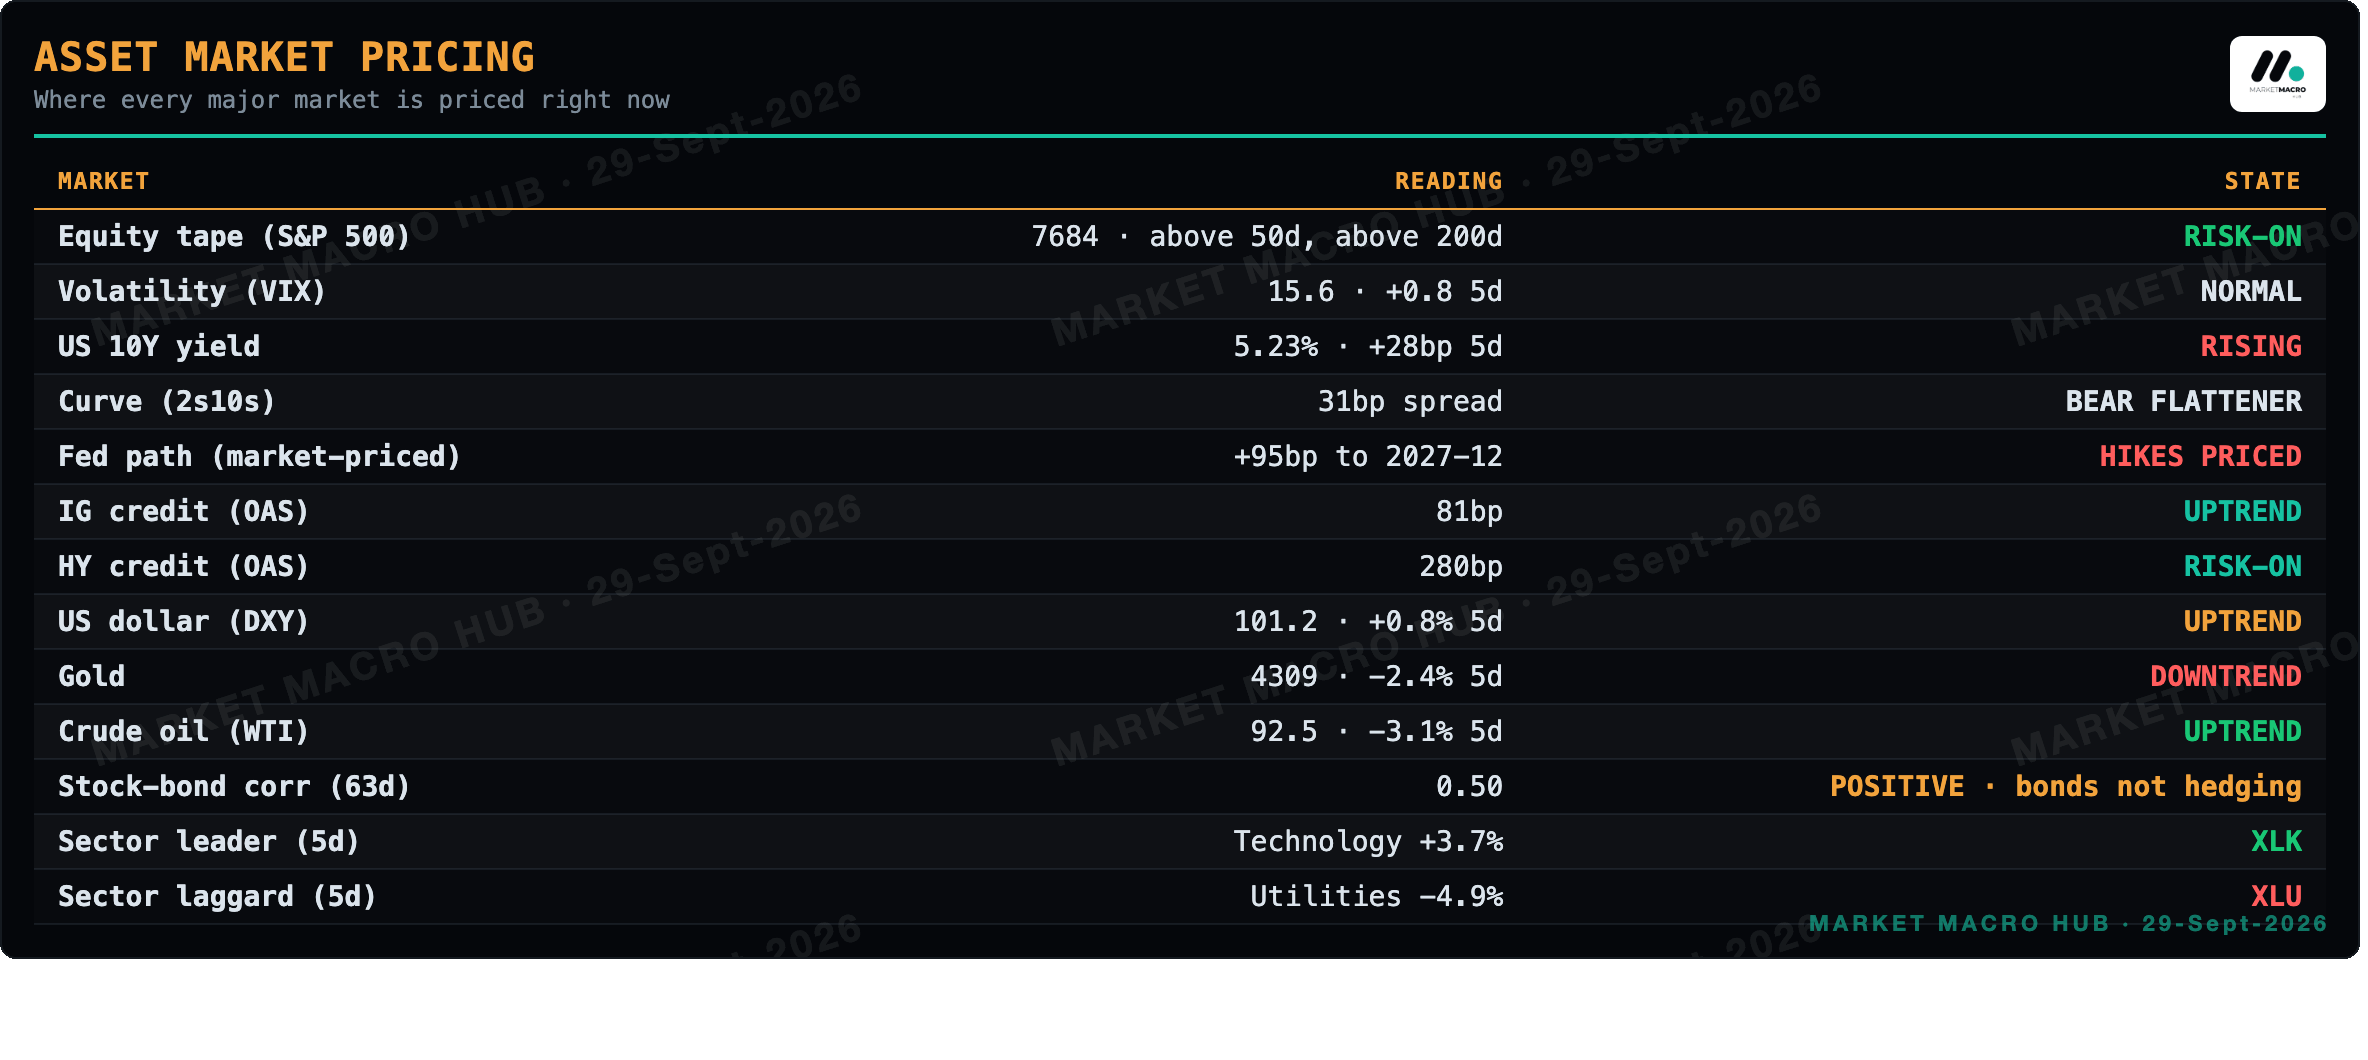
Credit stays quiet. IG sits at 81bp, the middle of its own range and well inside the 89bp mean, so credit is not the marginal story today and my anchor holds. HY at 280bp sits at the tight end, risk appetite at the low-quality end is intact.
Rates & Fed Pricing
No cut is anywhere on this strip, so the whole conversation is about hikes. November is the first month with a hike at least half-priced at around 72%, and December is effectively locked at close to 100% with an implied 4.2%. The strip peaks in September 2027 at 4.85%, +97bp over the current EFFR, and the trough is now, +1bp. The terminal repriced +8.5bp on the day and +28bp on the week, driven by the Iran oil bid and Cook's inflation-pressure line.
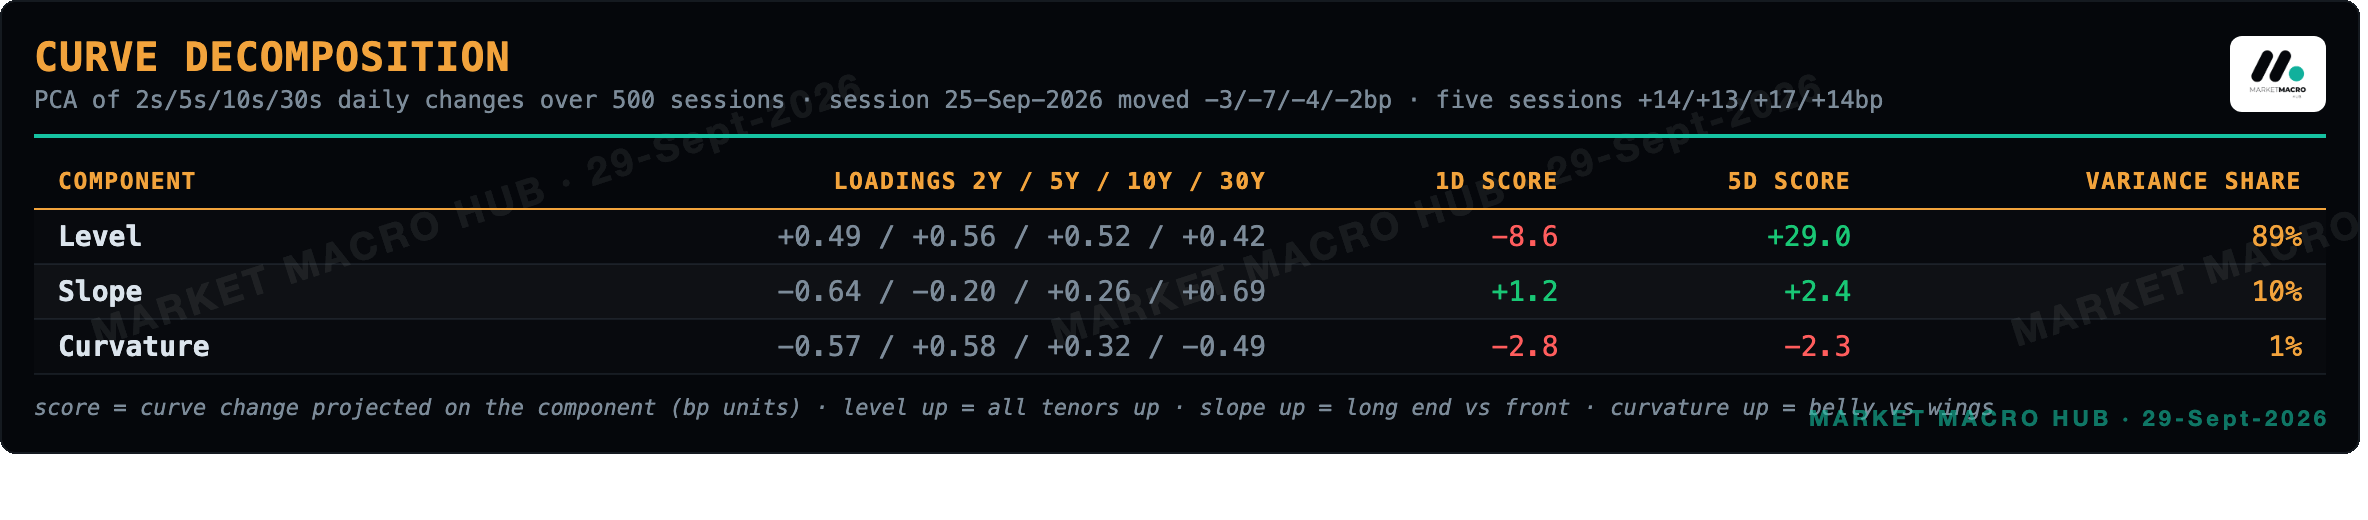
That is why I stay short the three-hikes-fully-priced story. My tell is 2s10s. It steepened to 31bp, which tells me the long end thinks the short-end path is too aggressive. If the curve starts bear flattening as equities sell, I'd take that as the market believing the hikes, and I'd change my read.
The Week Ahead
Tuesday, JOLTs job openings (cons 7.24). A soft print is the cleanest way to start doubting the hike path; a firm one hardens my read.
Tuesday, CB Consumer Confidence (cons 90) and Case-Shiller, second-order for me unless confidence rolls over.
Tuesday, Goolsbee, Musalem and Williams all speak; I want to hear whether Cook's inflation line is the committee consensus.
Wednesday, ADP employment (cons 72). This matters, a big beat feeds the front-end bid directly.
Wednesday, Goods Trade Balance and mortgage rates, watching mortgages at 7.12% for housing durability.
Tradeable Levels
Pivots off the last completed session (2026-09-24 / 2026-09-25 / 2026-09-28). Levels marked * sit within 0.6 x ATR14 of the close.
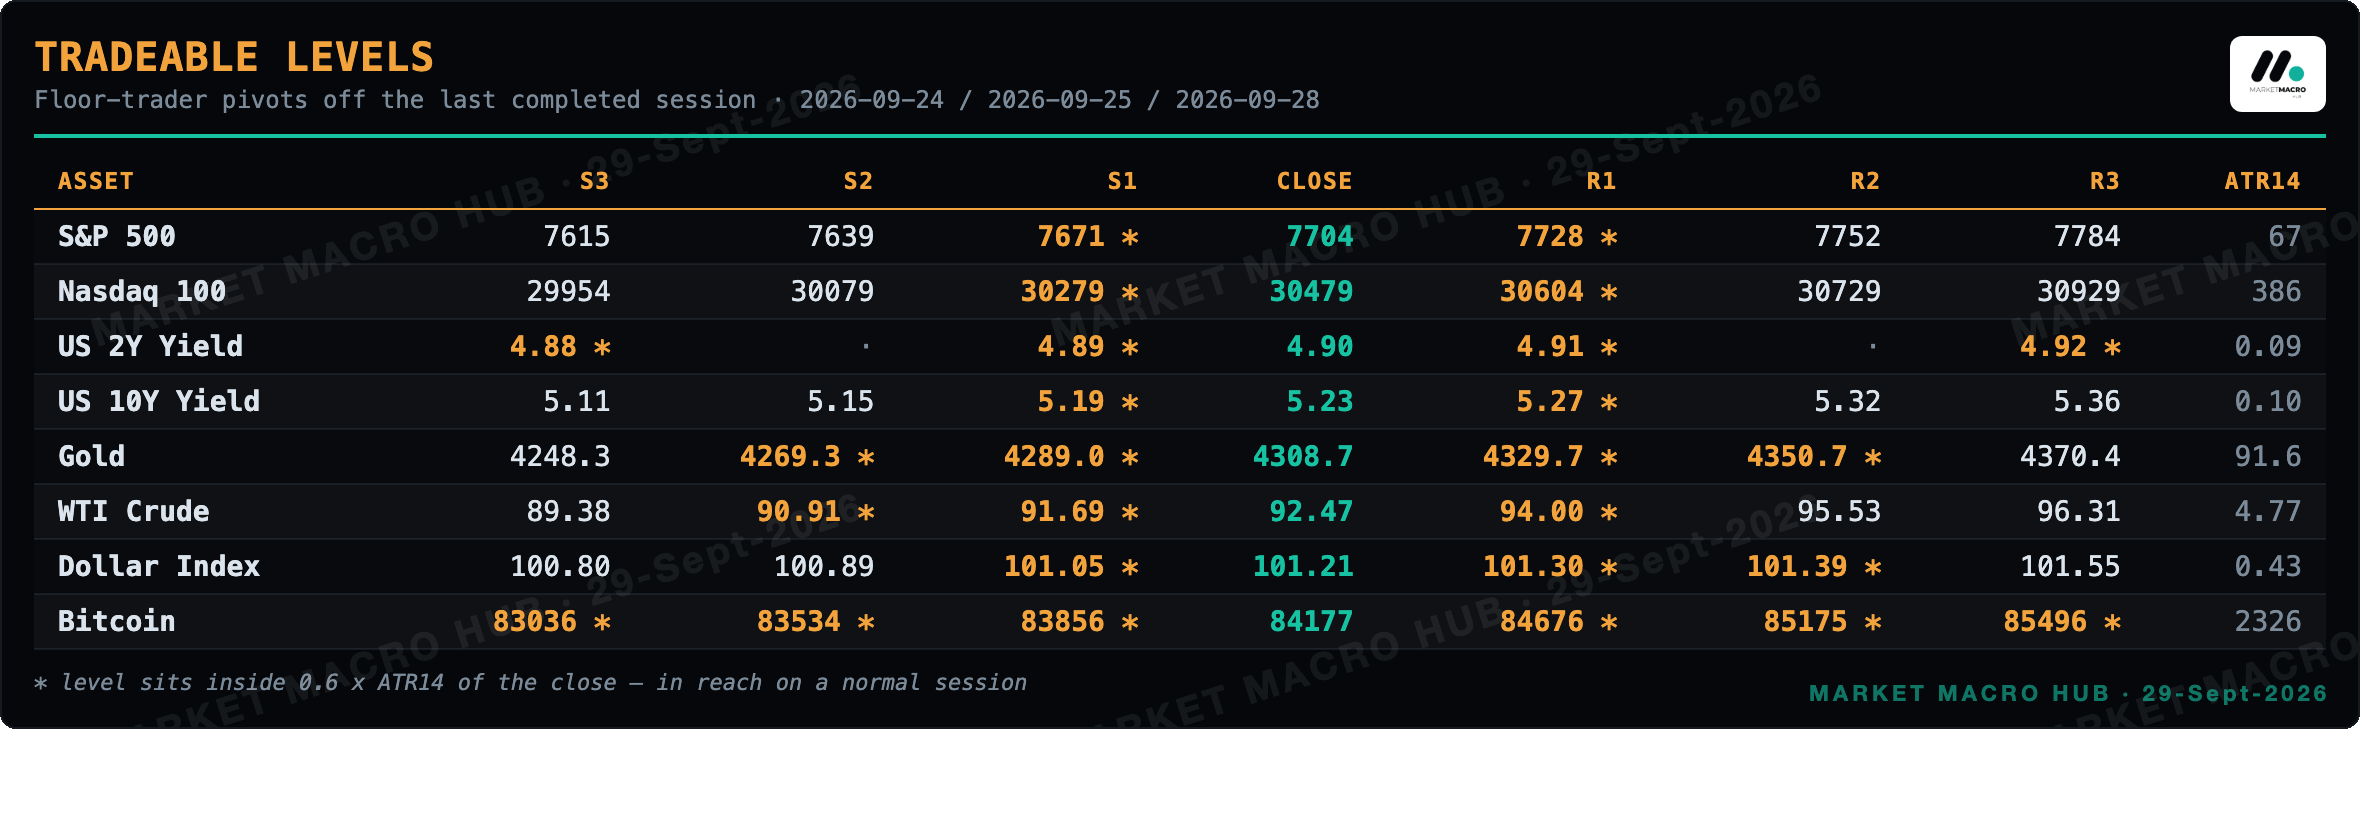
US 2Y Yield priced off a session whose range was under a third of normal travel, so that board is compressed and nearly every level sits in reach. Weekend crypto and half-day holiday sessions do this; treat the levels as loose rather than precise.
Vol Screen · Rich and Cheap Implied Vol
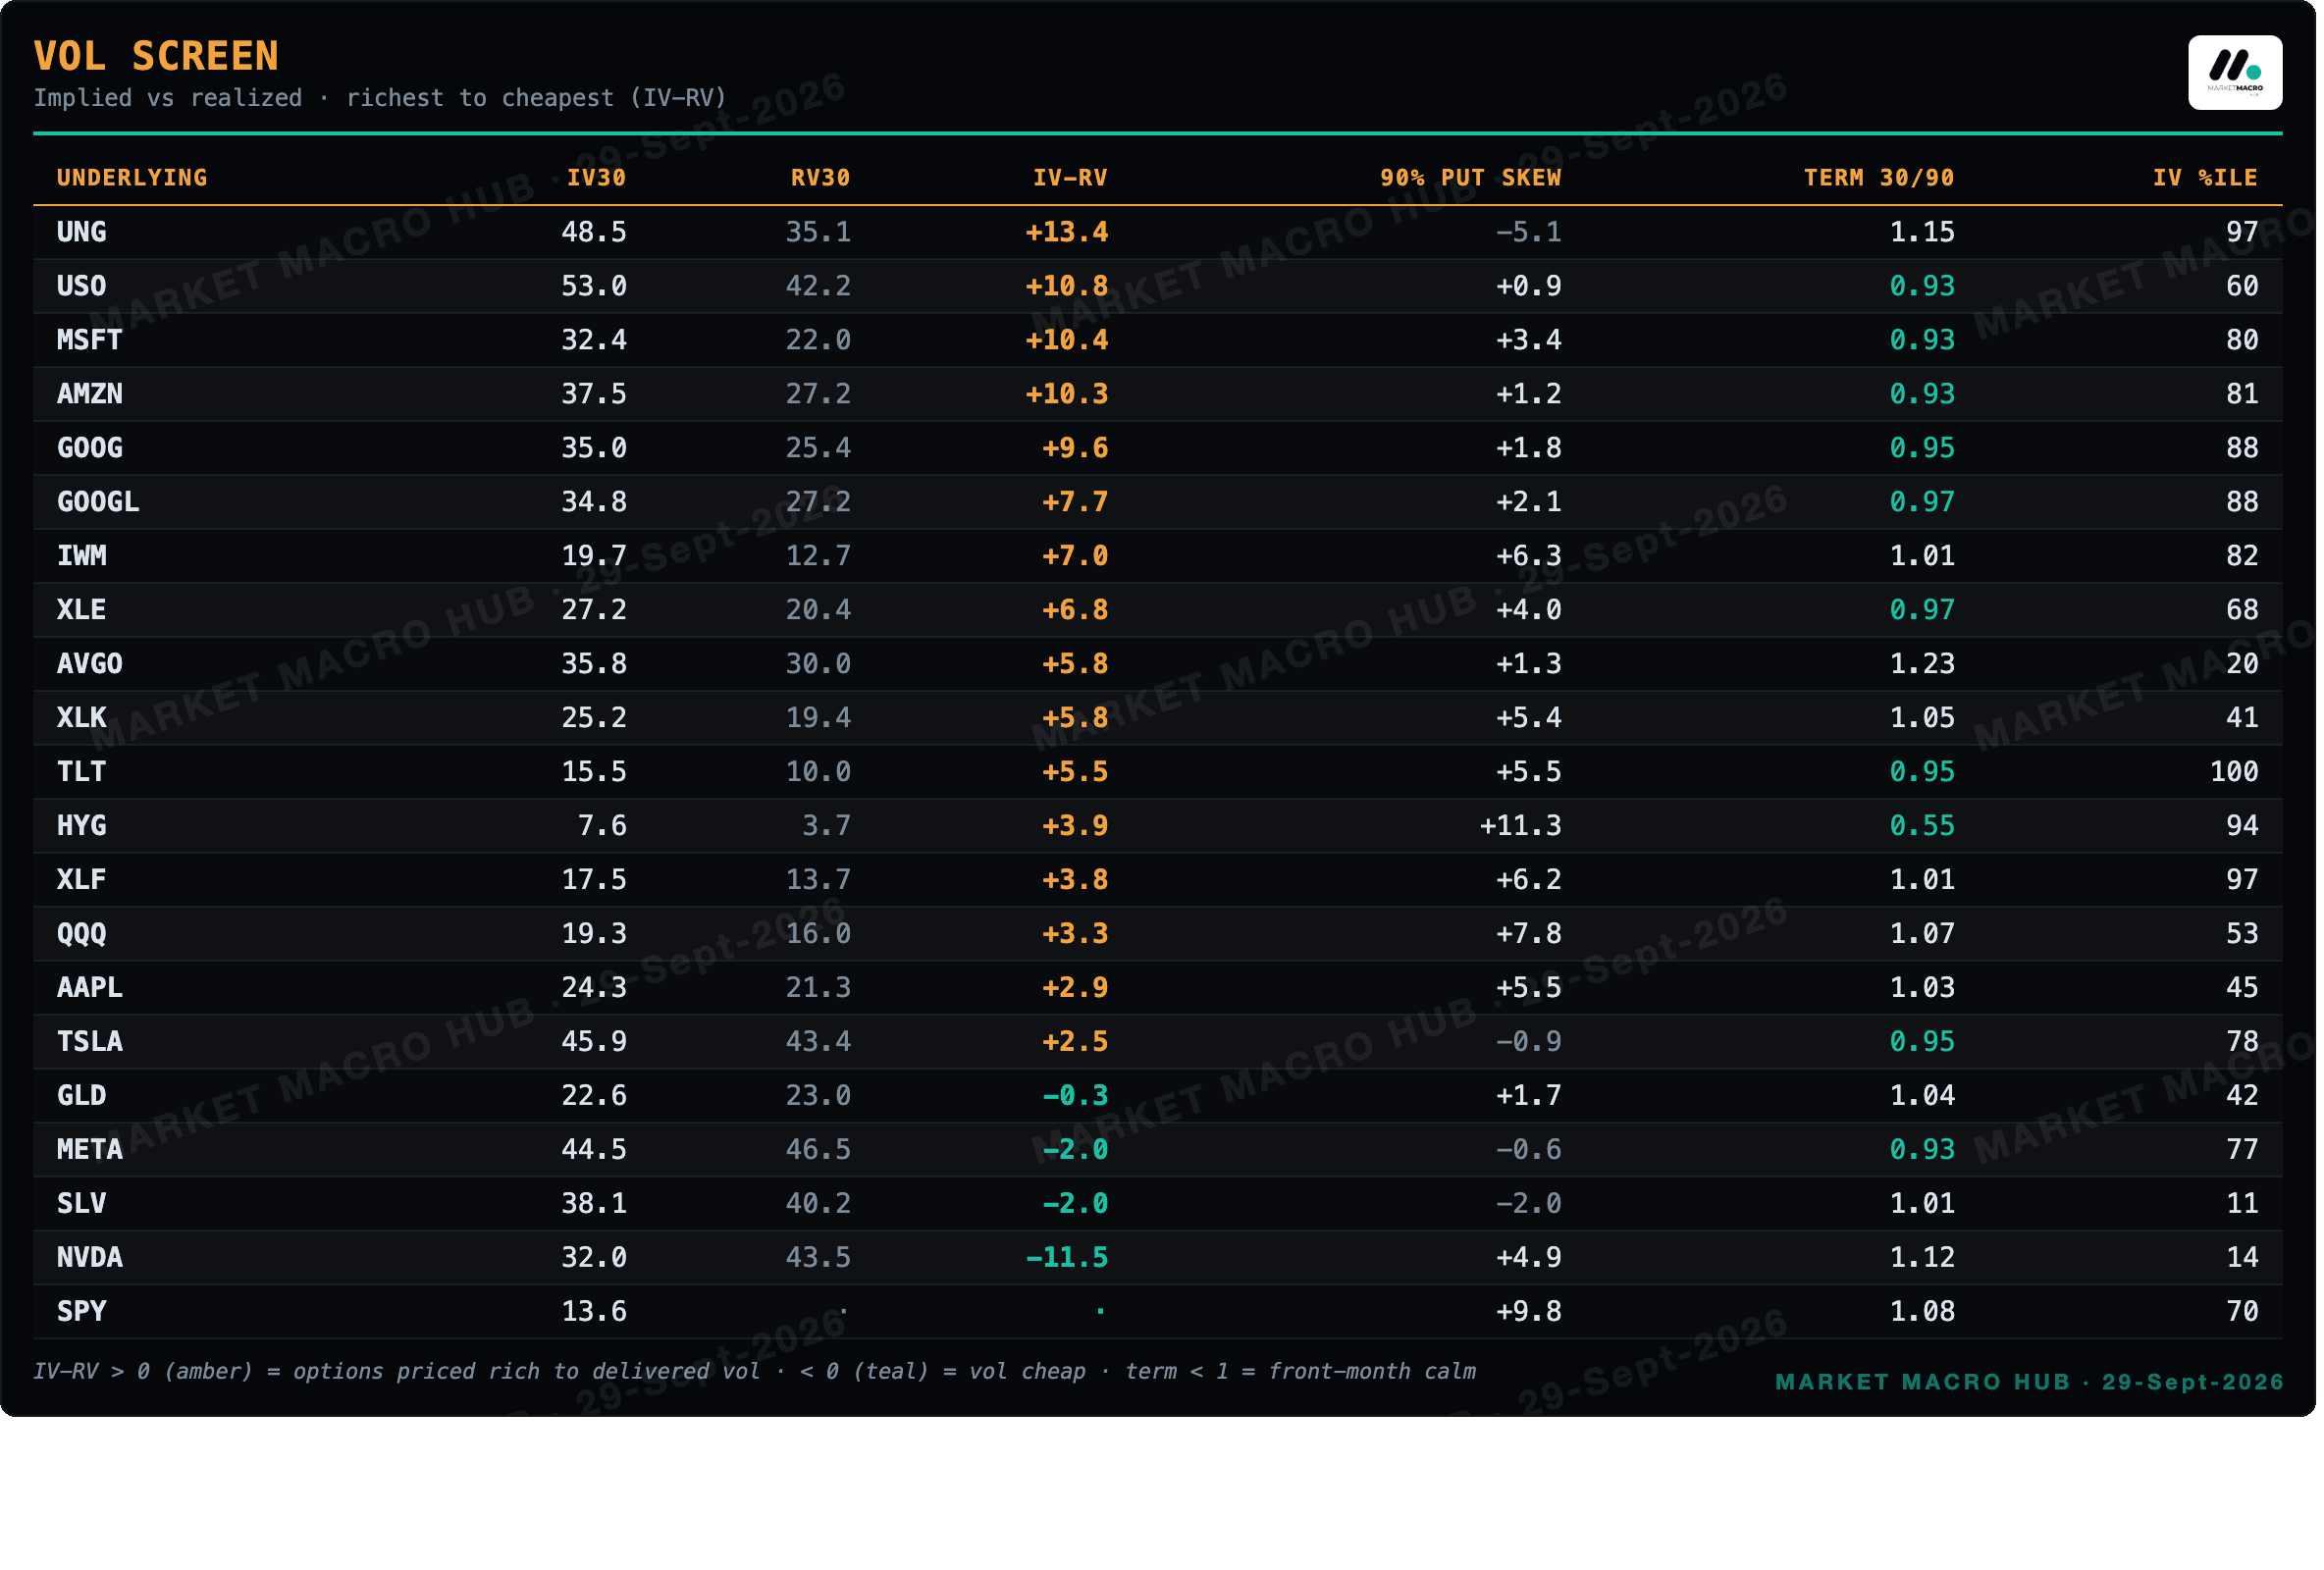
Positive IV-RV = options priced rich to what the tape is delivering (UNG and USO richest today); negative = vol going cheap (NVDA and SLV). Percentiles are each name's own archive history.
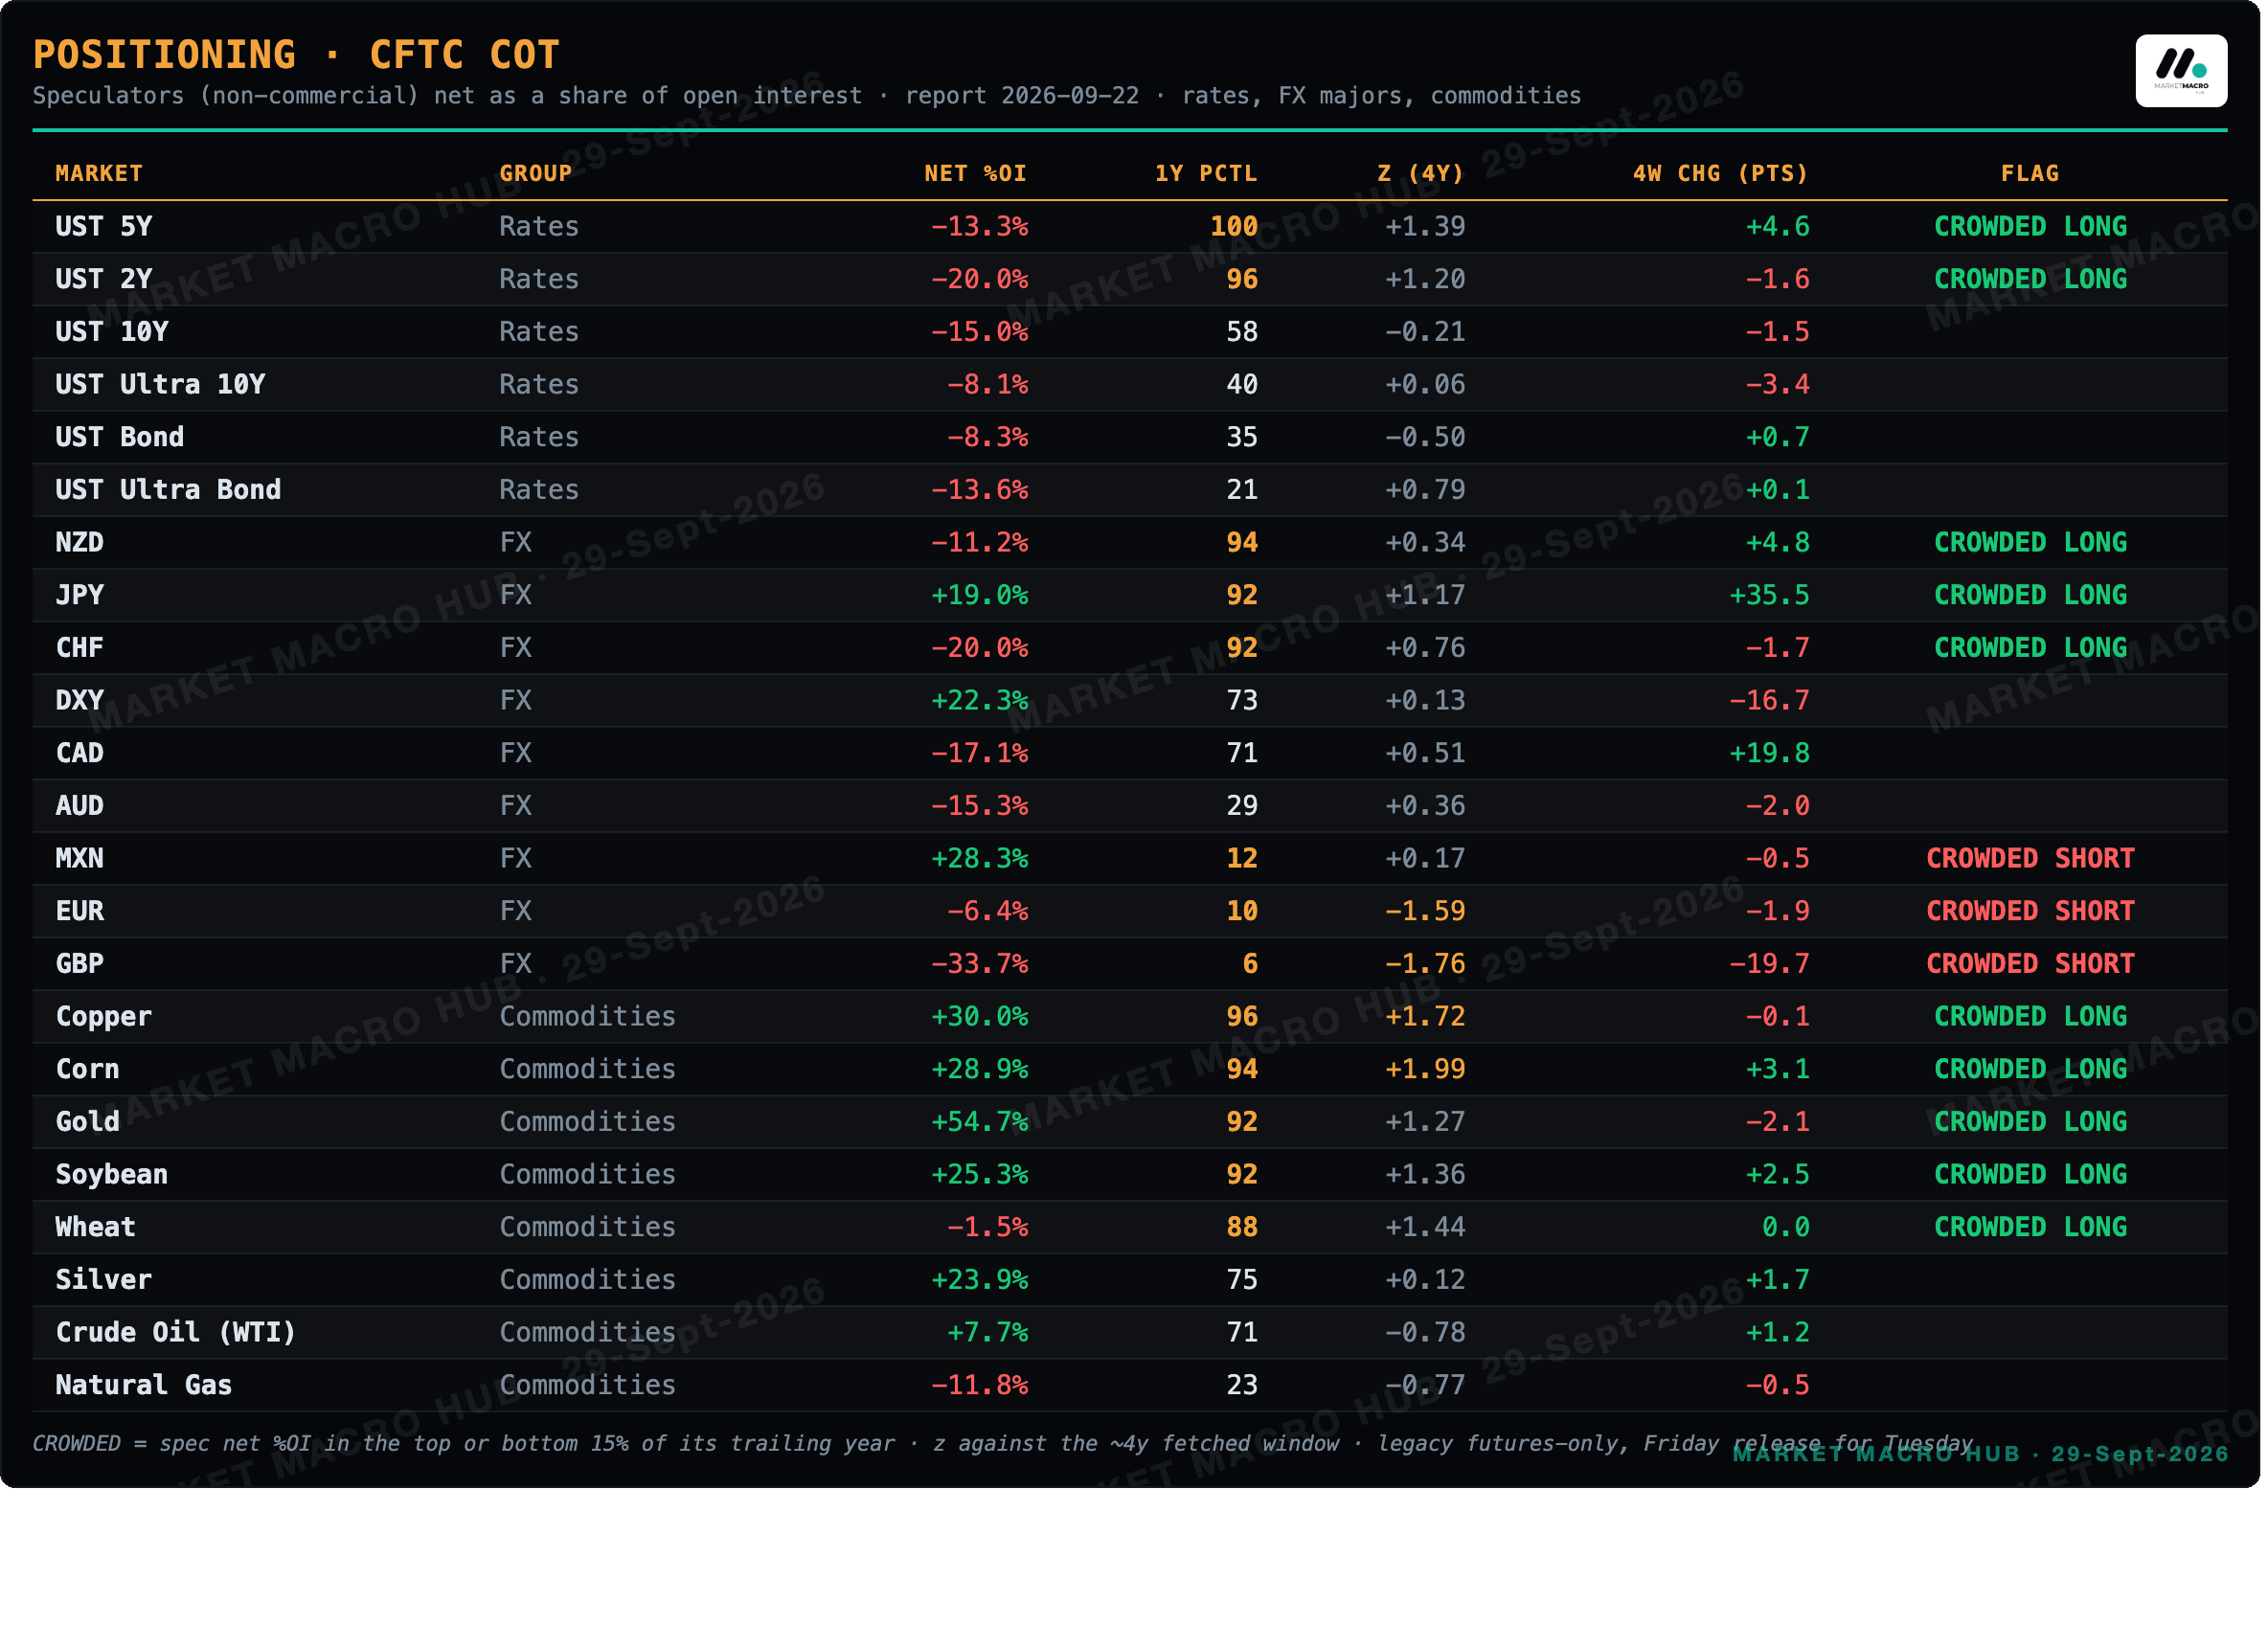
Positioning
Disclaimer
The information in this publication is provided for informational and educational purposes only and is believed to be reliable, but its accuracy and completeness are not guaranteed. Nothing herein constitutes investment advice, an offer, or a solicitation to buy or sell any security, derivative, digital asset, or other financial instrument, nor a recommendation suited to any specific reader. All figures are drawn from the day's computed data set at the time of generation and may be delayed, revised, or superseded. Markets involve risk, including the possible loss of principal; past performance and historical relationships do not guarantee future results. Readers should conduct their own research and consult a qualified financial adviser before making any investment decision. The author may hold positions in instruments discussed. This publication is licensed for the personal use of the subscriber only: redistribution, reproduction, or resale in any form is prohibited. © 2026 MARKET MACRO HUB. All rights reserved.