


TL;DR
Long the hike story, December is fully priced and no cut sits on the strip; today's core PCE at 0.3% consensus is the test.
Three-plus hikes still look stretched to me, my tell is 2s10s at 32bp; bear flattening flips it.
Rate vol is the live tail, MOVE at 106.61 has not leaked into equity vol.
Credit is my anchor, IG at 83bp is mid-range and calm; invalidation stays 90bp.
The bond rout is the risk equities keep shrugging off, 10Y +28bp on the week.
Where We Stand
Yesterday I said long the hike story, December is the first fully-priced move and no cut sits anywhere on the strip. This morning's tape confirms it. The strip still has December at essentially 100% and the terminal added +19bp on the week, so the front end keeps grinding my way.
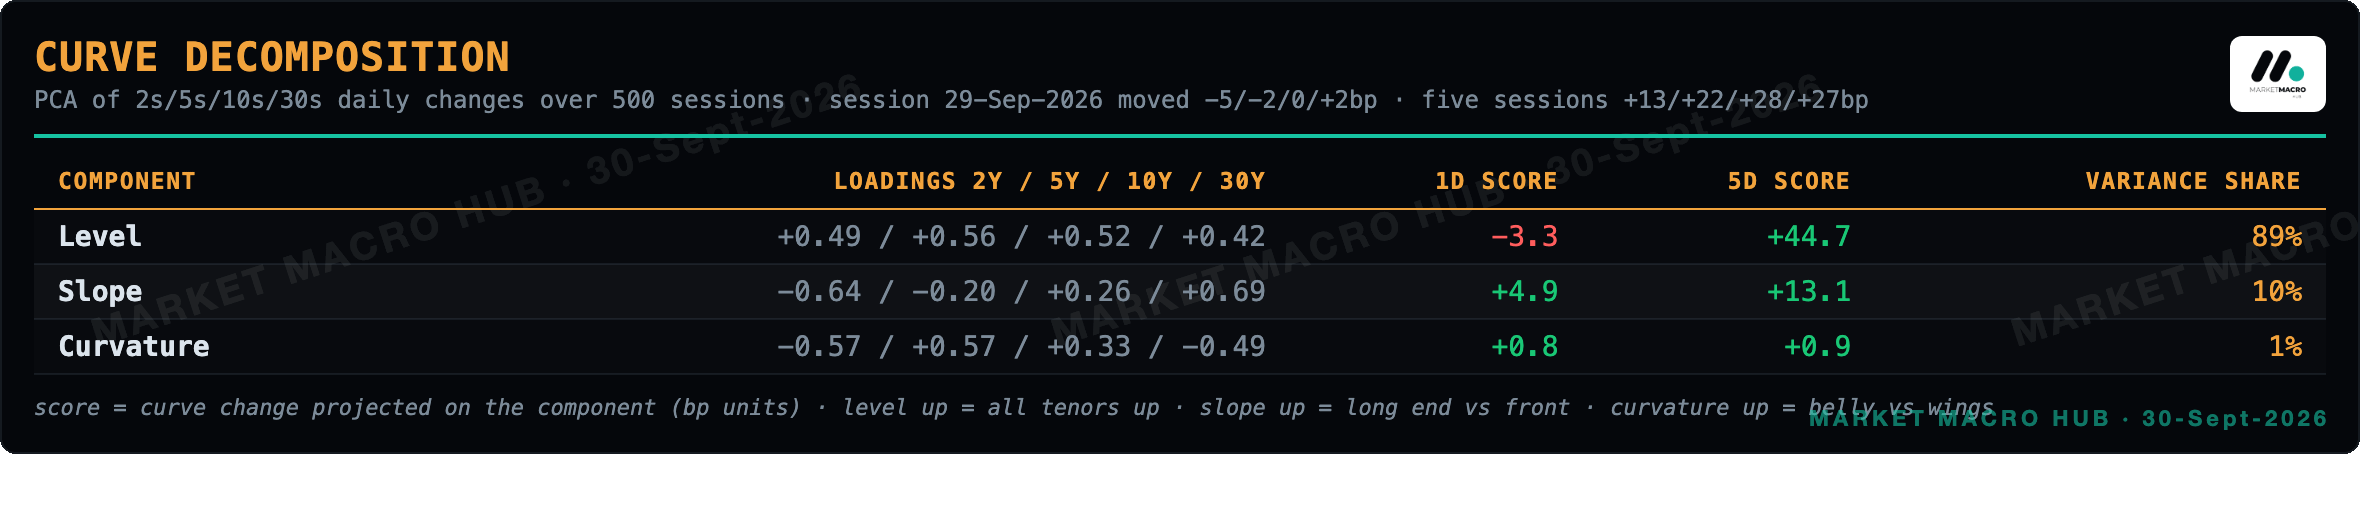
The oldest open thesis is the rate vol tail from five days ago, and it is more alive today. MOVE is up to 106.61 while VIX sits at 16.03, so the anxiety lives in rates and not in equities. My "three hikes are stretched" thesis stays intact for now because 2s10s held at 32bp rather than bear flattening, but the curve gave back 4bp on the day and that is the tell I'm watching. The GBP positioning flag is still live after another washed-out week.
Today's Tear Sheets
The full daily pack is attached below · six PDFs generated from the same computed data set as this note:
Macro Regime · regime classifier, growth x inflation quadrant, curve regimes, cross-asset drivers, crisis phase, model state card, breadth, credit, vol term structure, liquidity, stock-bond correlation, housing
Fixed Income · UST complex, term premia, rate risk, auctions, global curves, Fed/ECB/BoE/BoJ implied policy paths, global 2Y and 10Y panels
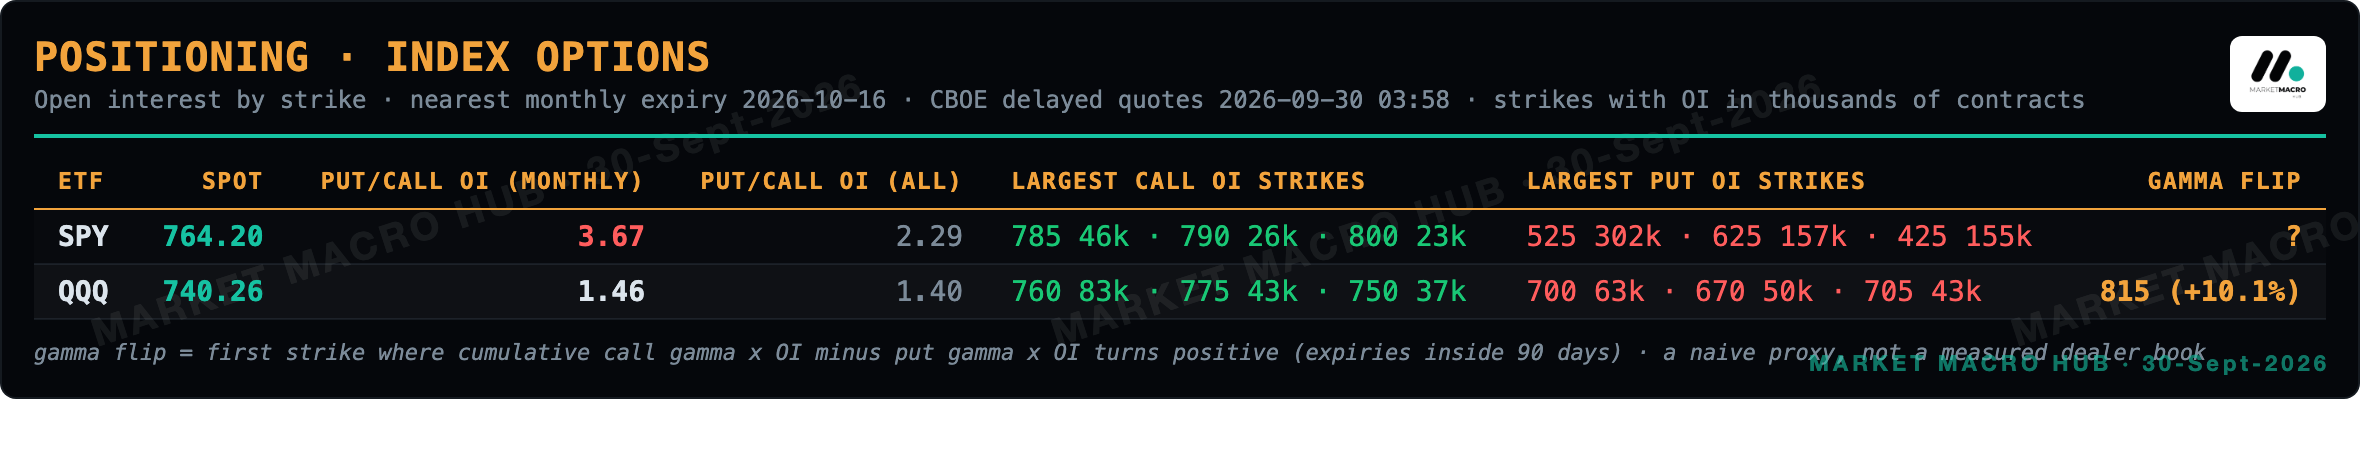
Equities · index pages, daily attribution, relatives, vol suite, vol cone, gamma, global relatives, Mag7+ quant sheet, options surfaces
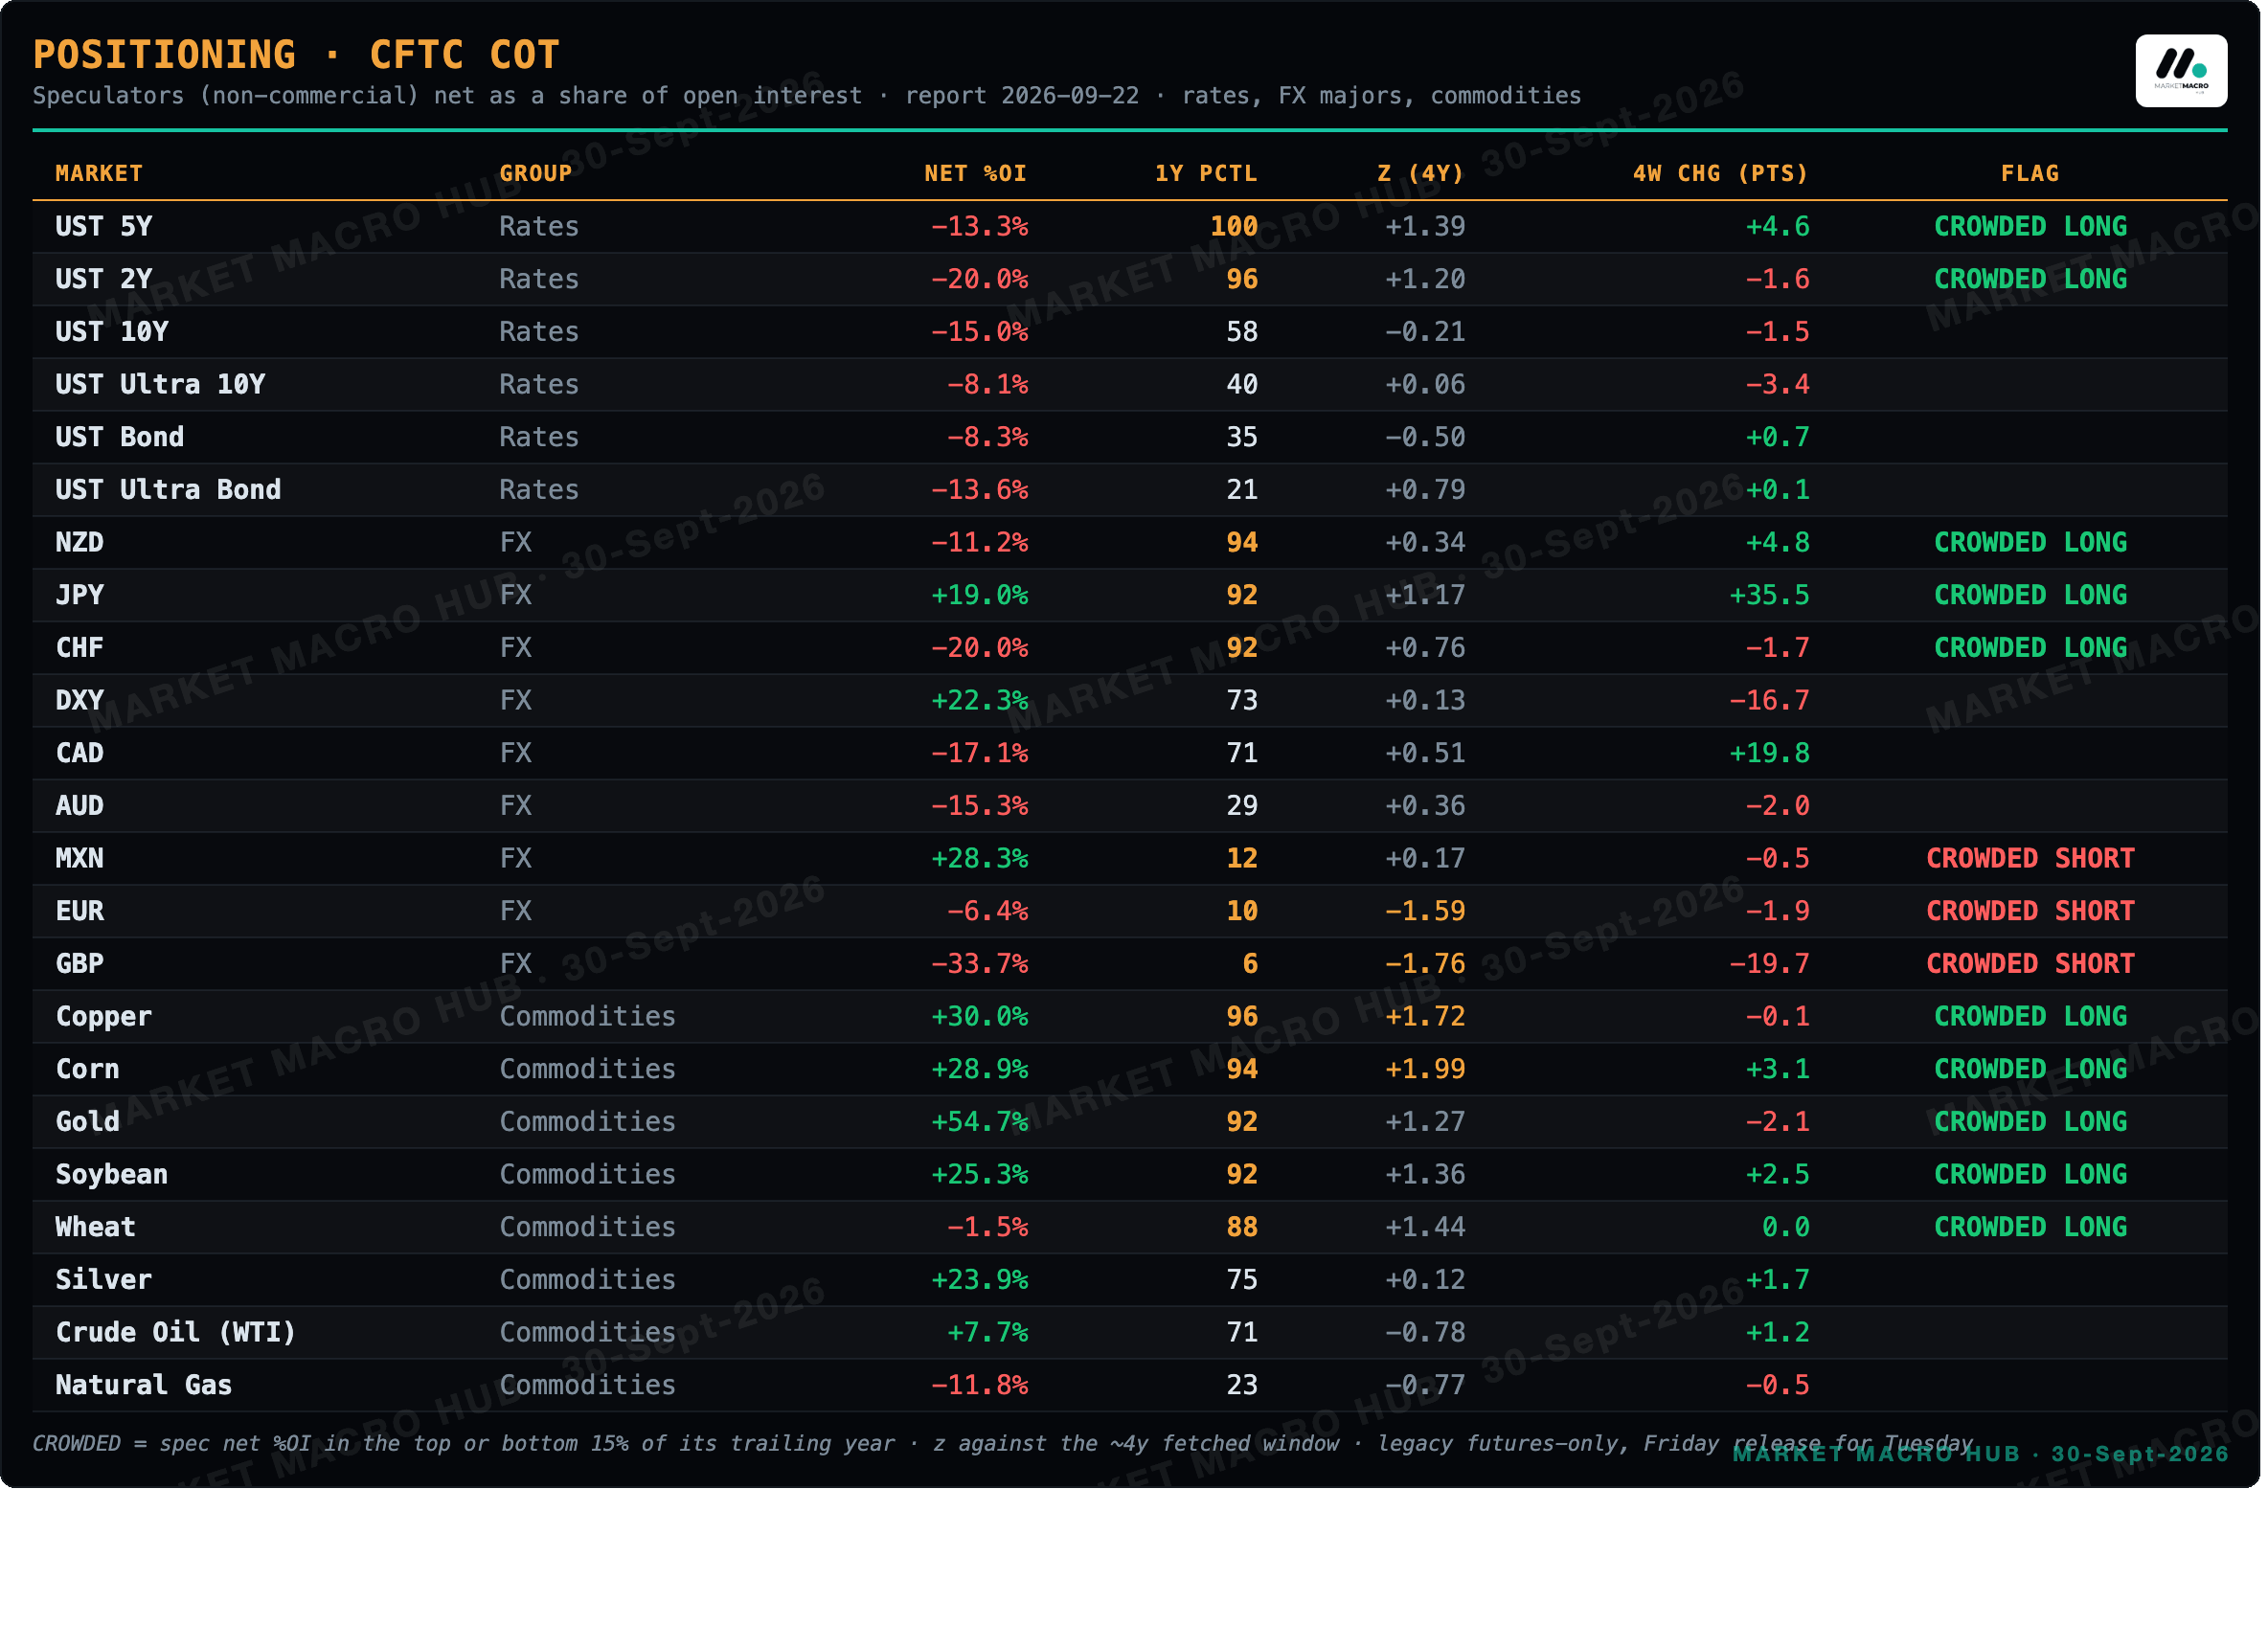
FX · majors dashboards, carry, correlations, COT positioning, crosses
Commodities · energy, metals, agriculture, COT crowding, term structure
Crypto · BTC ladders, ETH, macro correlations, ETF flow proxy

Machine-readable pack (CSV + JSON): https://drive.google.com/drive/folders/1K-0kndwdgnDttITaQyfNgyO0Qh6Zd1sl
What Changed
What the Tape Is Arguing About
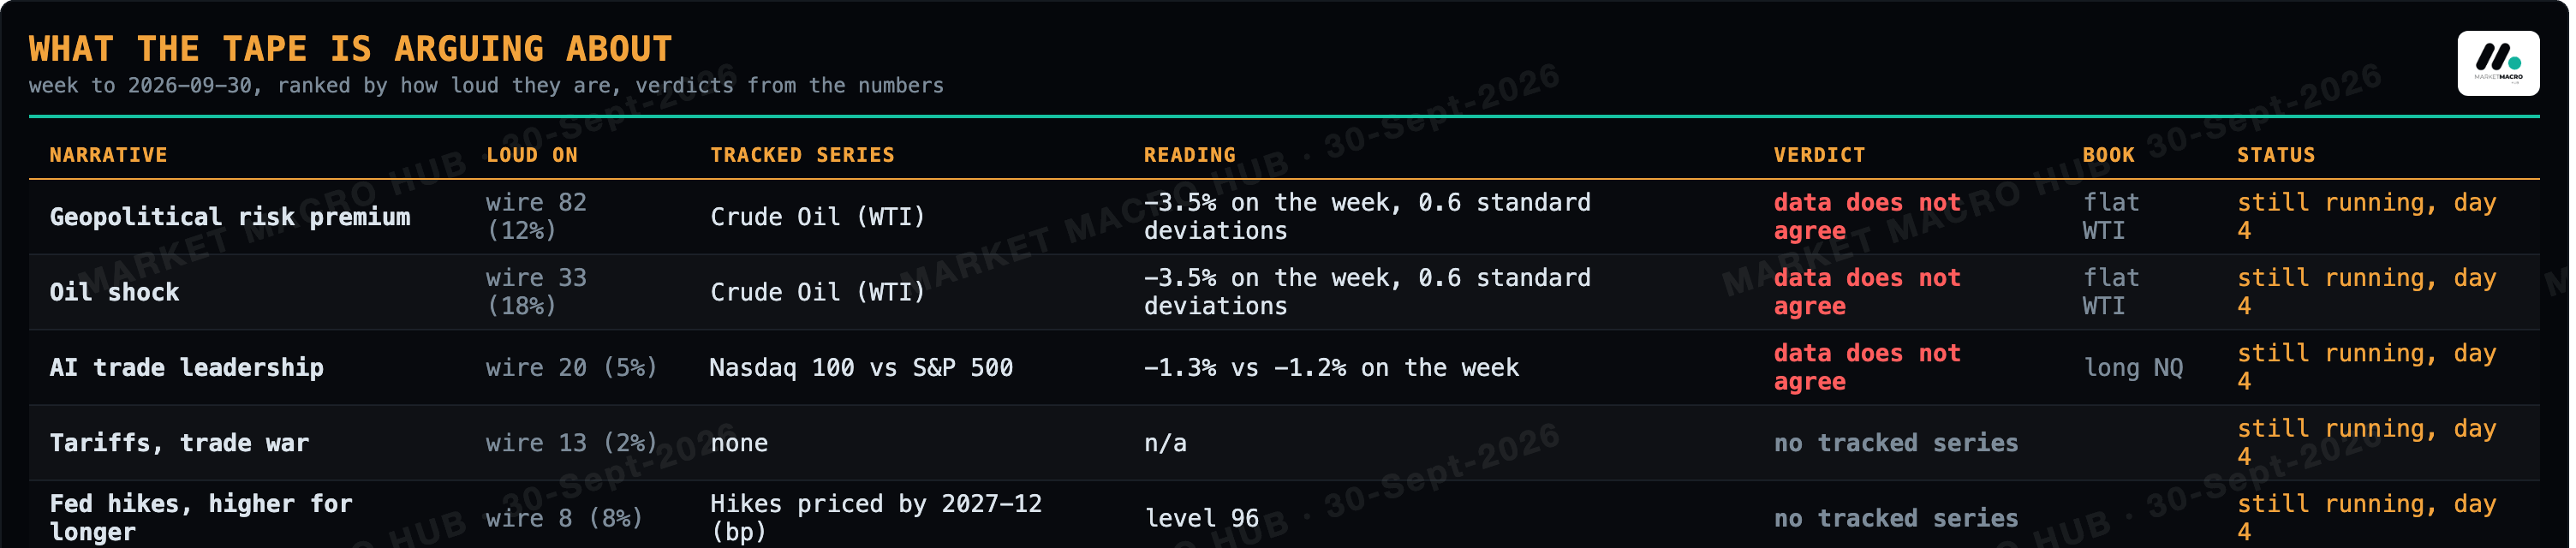
Geopolitical risk premium: data does not agree (Crude Oil (WTI) -3.5% on the week, 0.6 standard deviations).
Oil shock: data does not agree (Crude Oil (WTI) -3.5% on the week, 0.6 standard deviations).
AI trade leadership: data does not agree (Nasdaq 100 -0.1% relative on the week).
Tariffs, trade war: no tracked series.
Fed hikes, higher for longer: no tracked series.
Asset Market Pricing
Sector Attribution
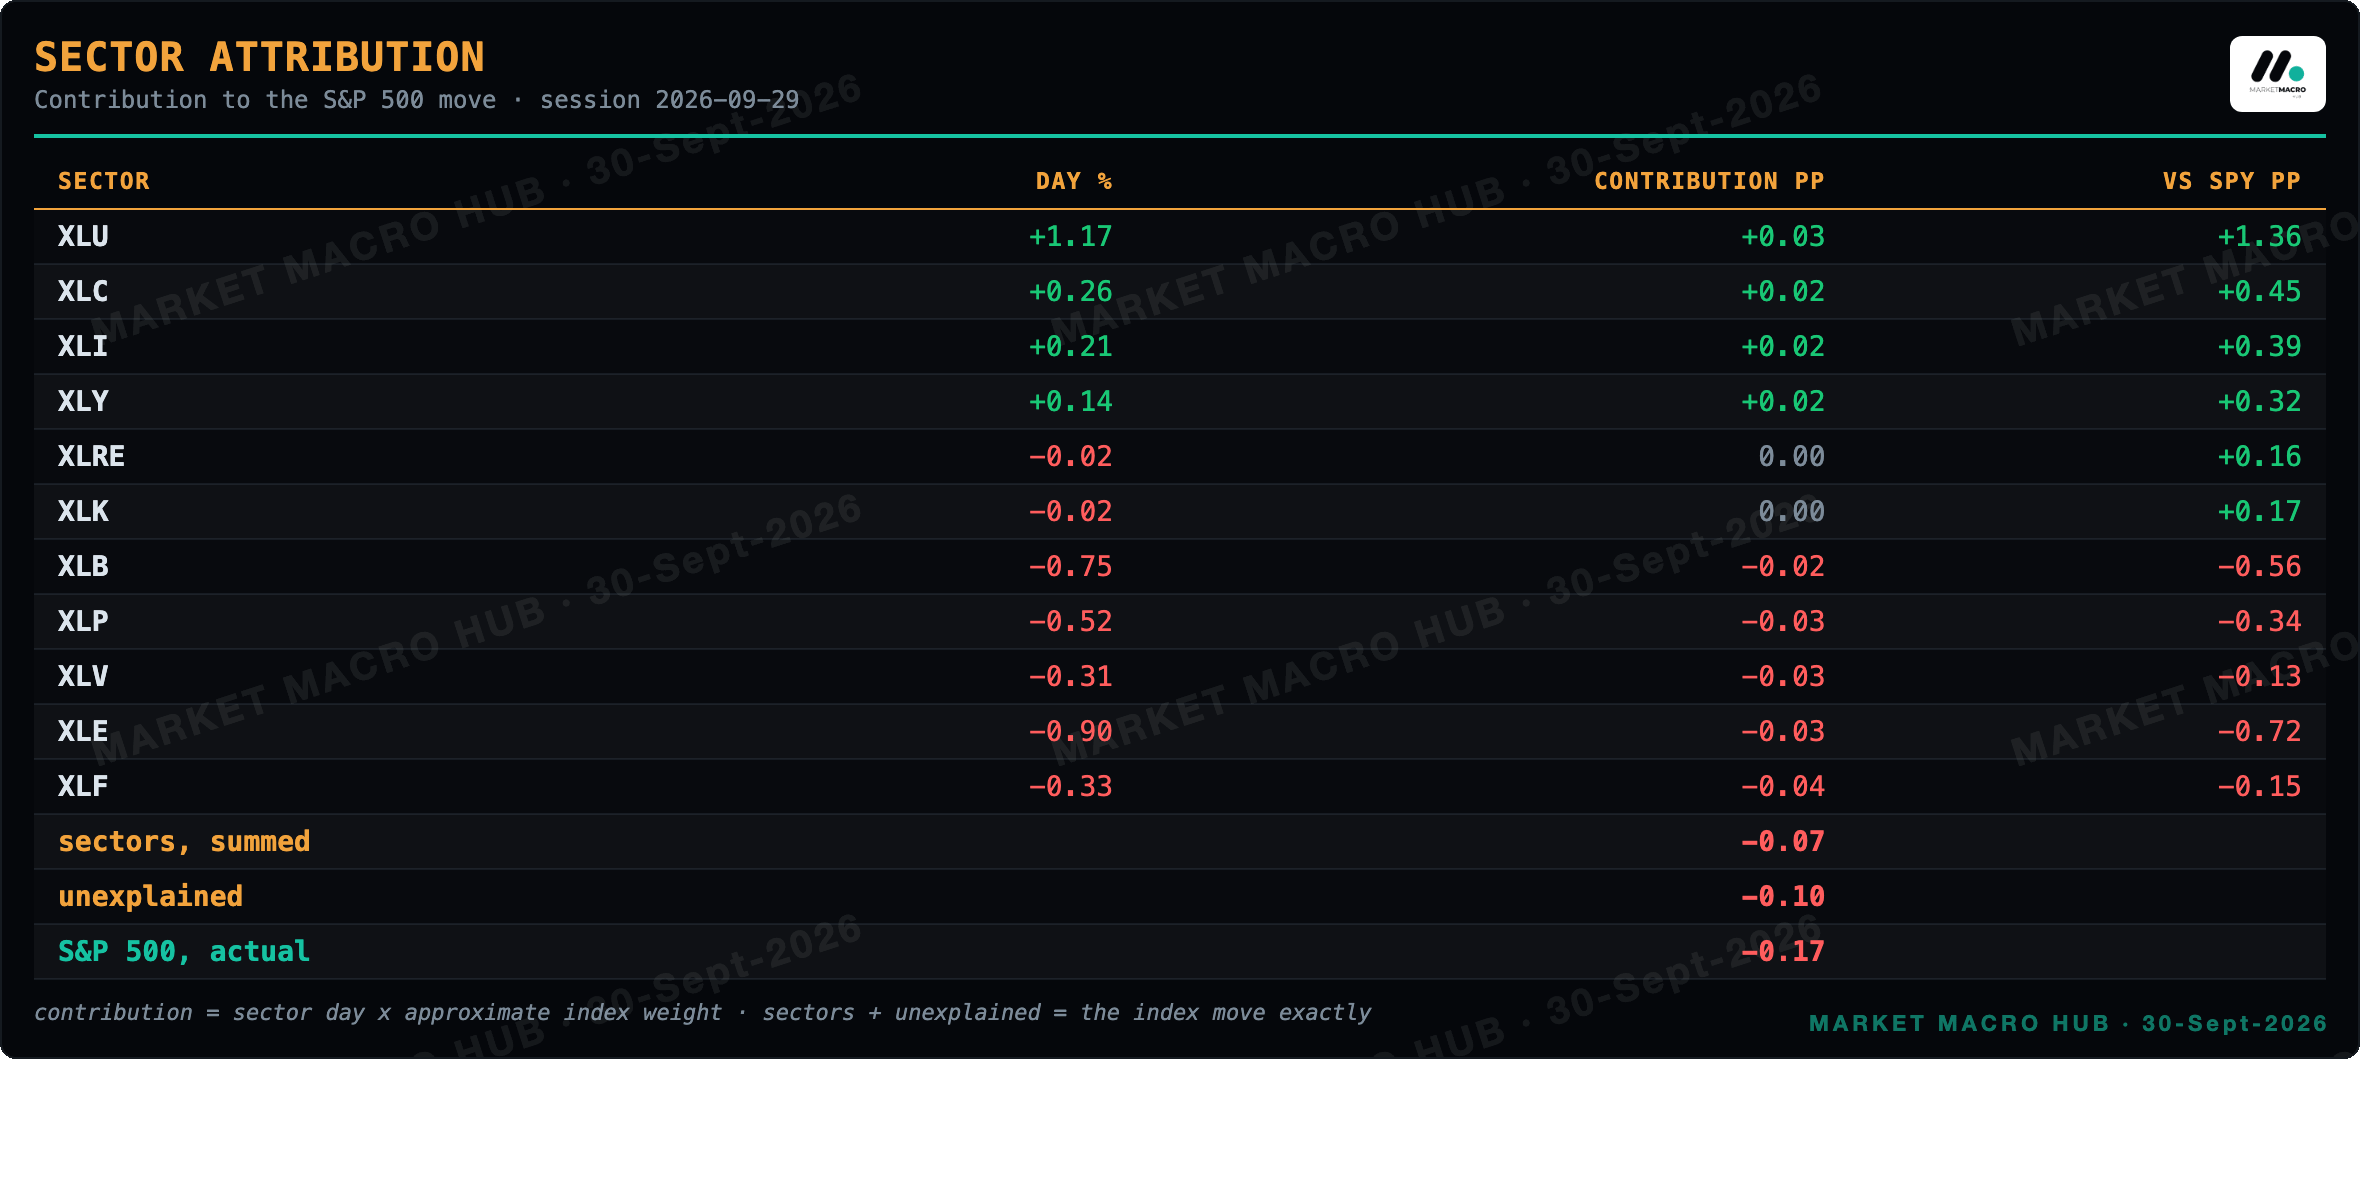
Session 2026-09-29. Sectors plus the unexplained remainder sum to the index move, and the sector split accounts for 43% of it.
Attribution
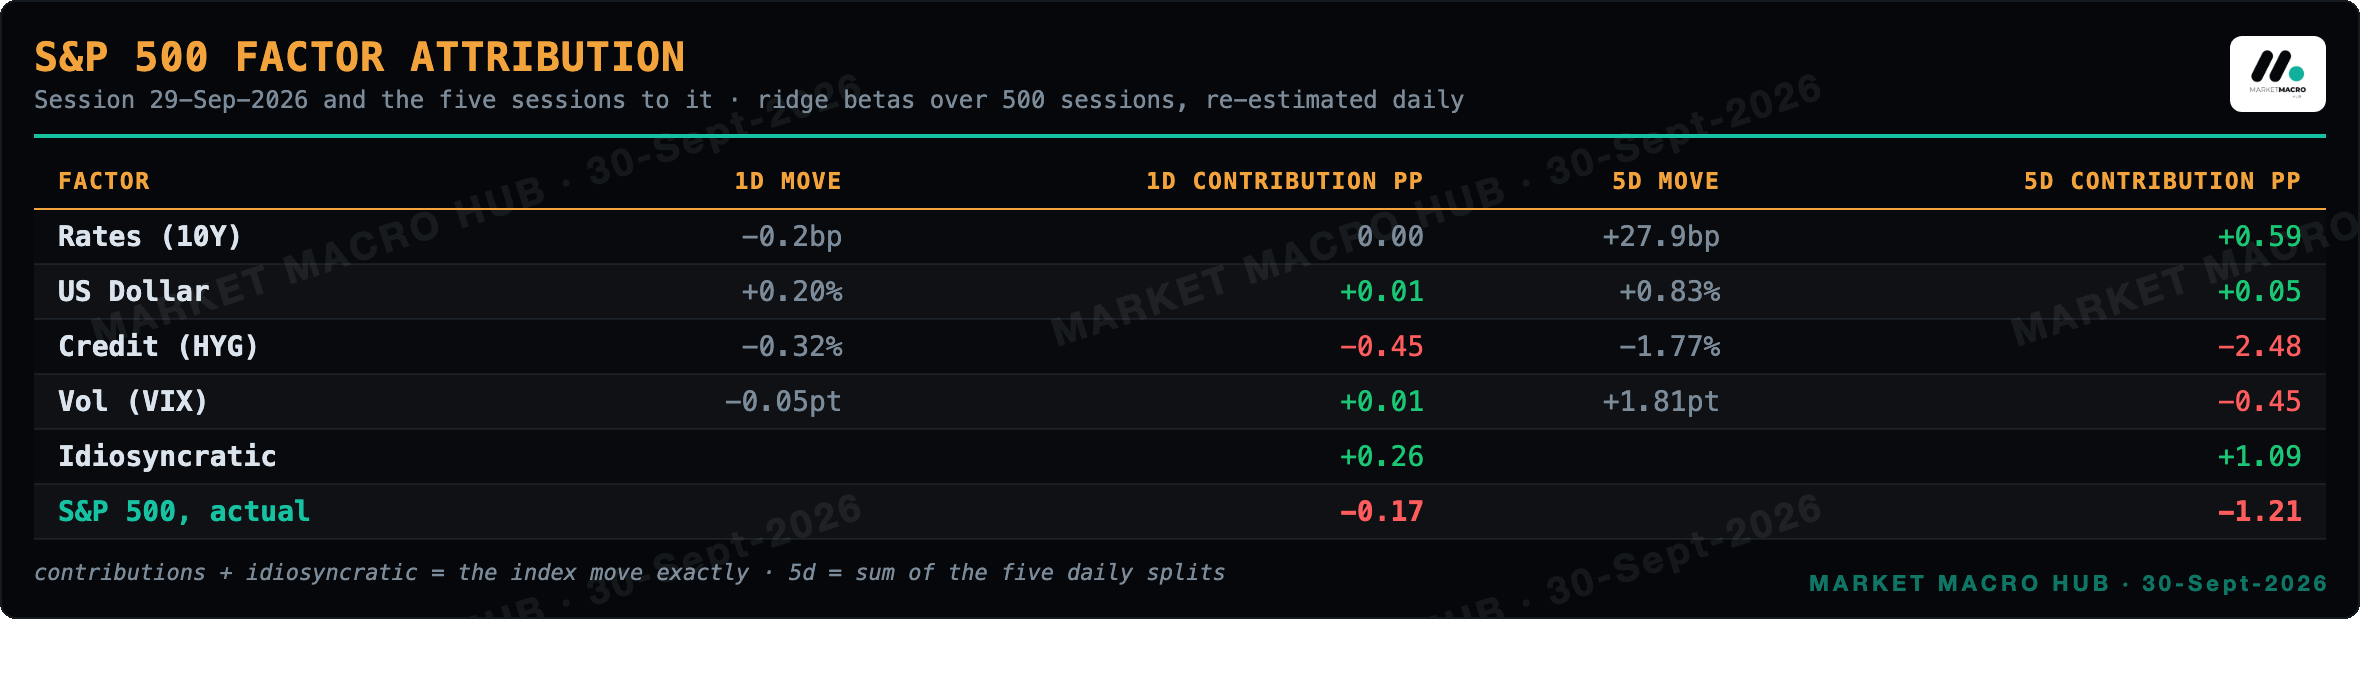
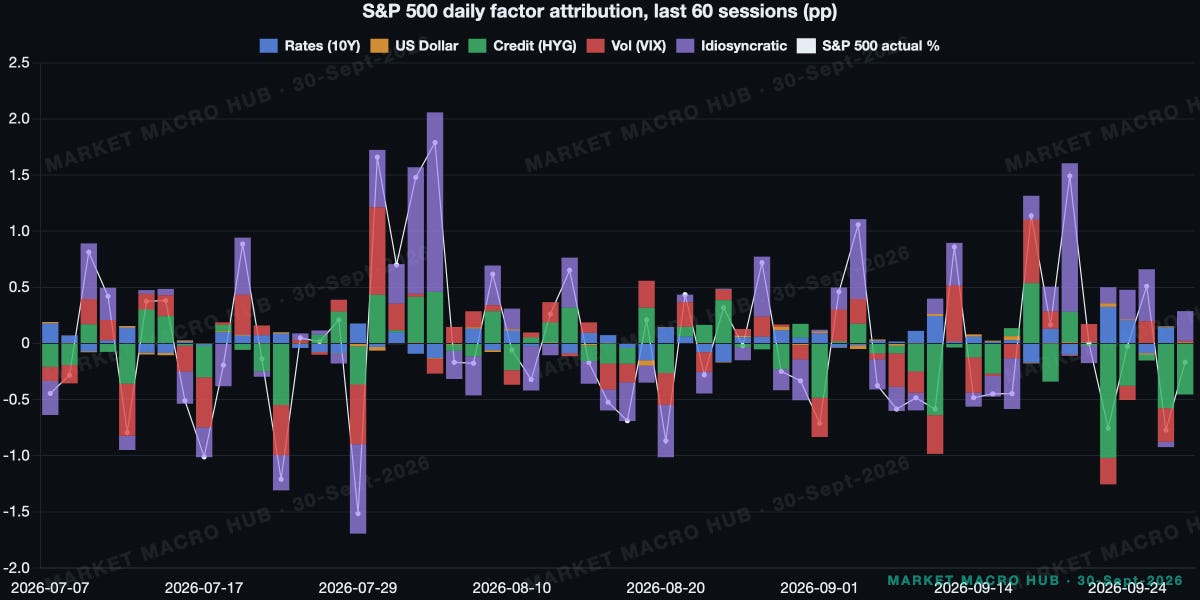
The S&P 500 closed -0.17% on 29-Sep-2026 and the largest driver was credit (HYG) at -0.45pp; over the five sessions to that close the index summed to -1.21% with credit (HYG) the largest driver at -2.48pp.
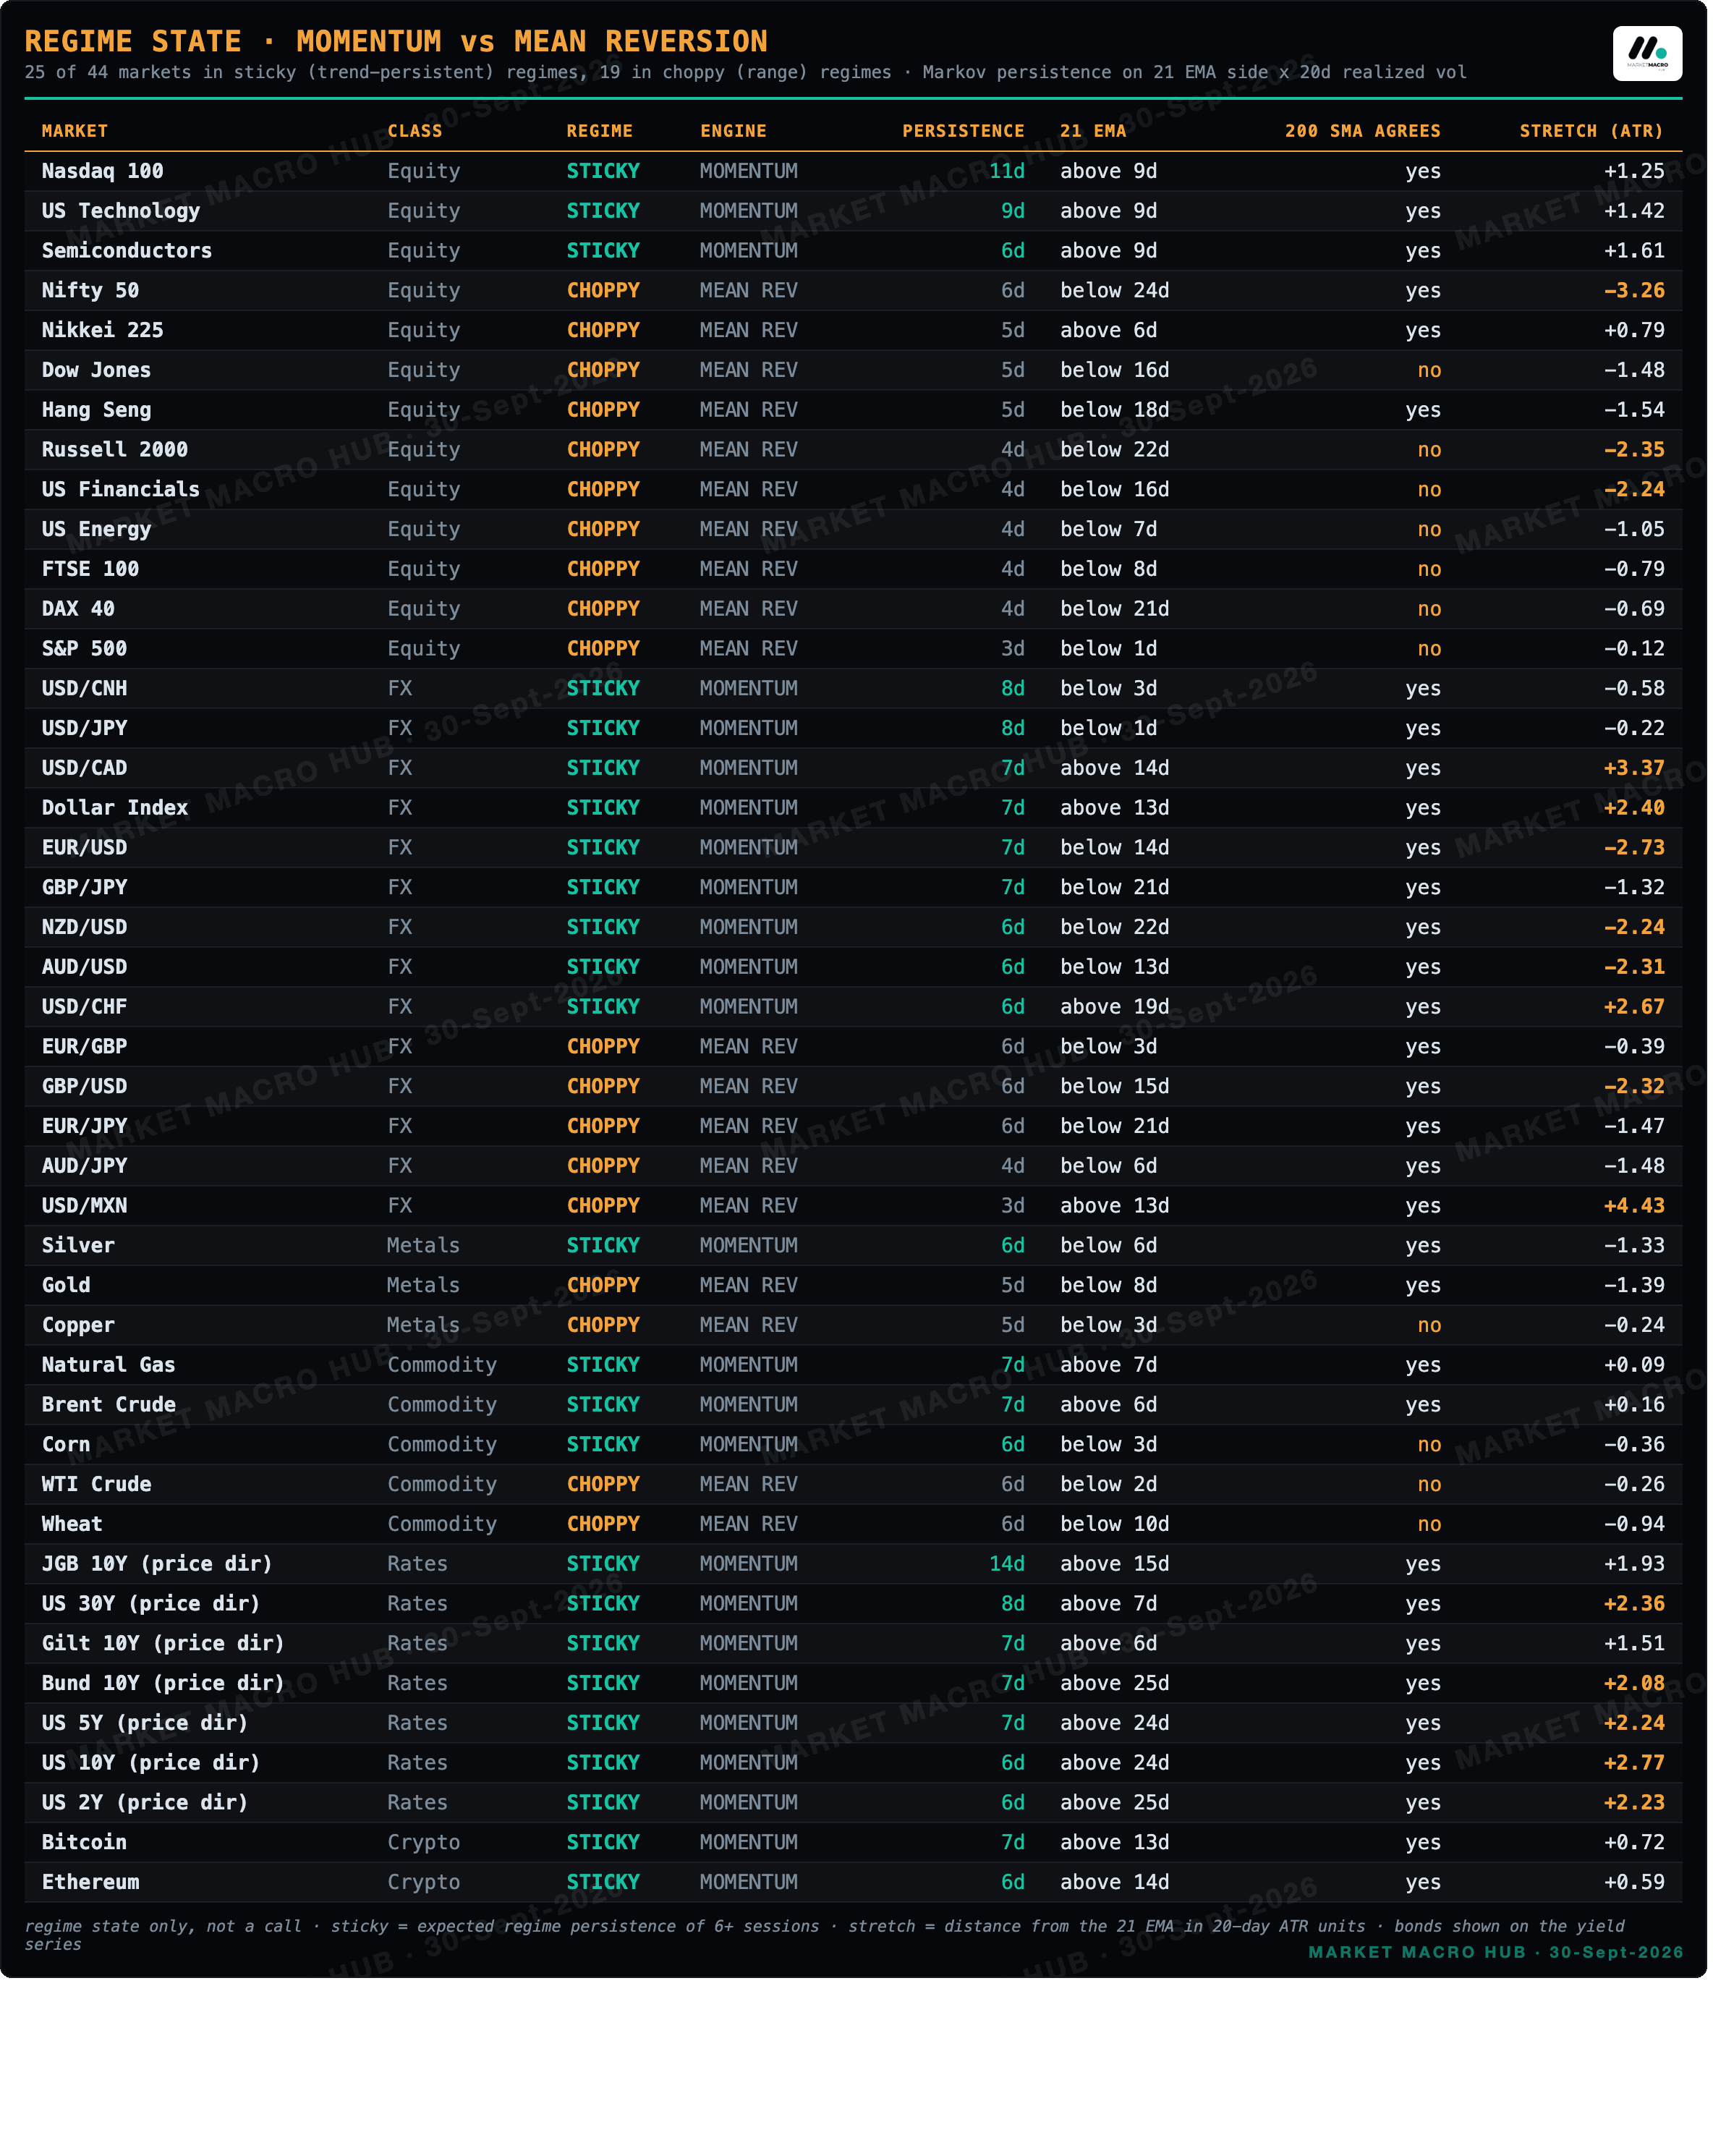
Regime State · Momentum vs Mean Reversion
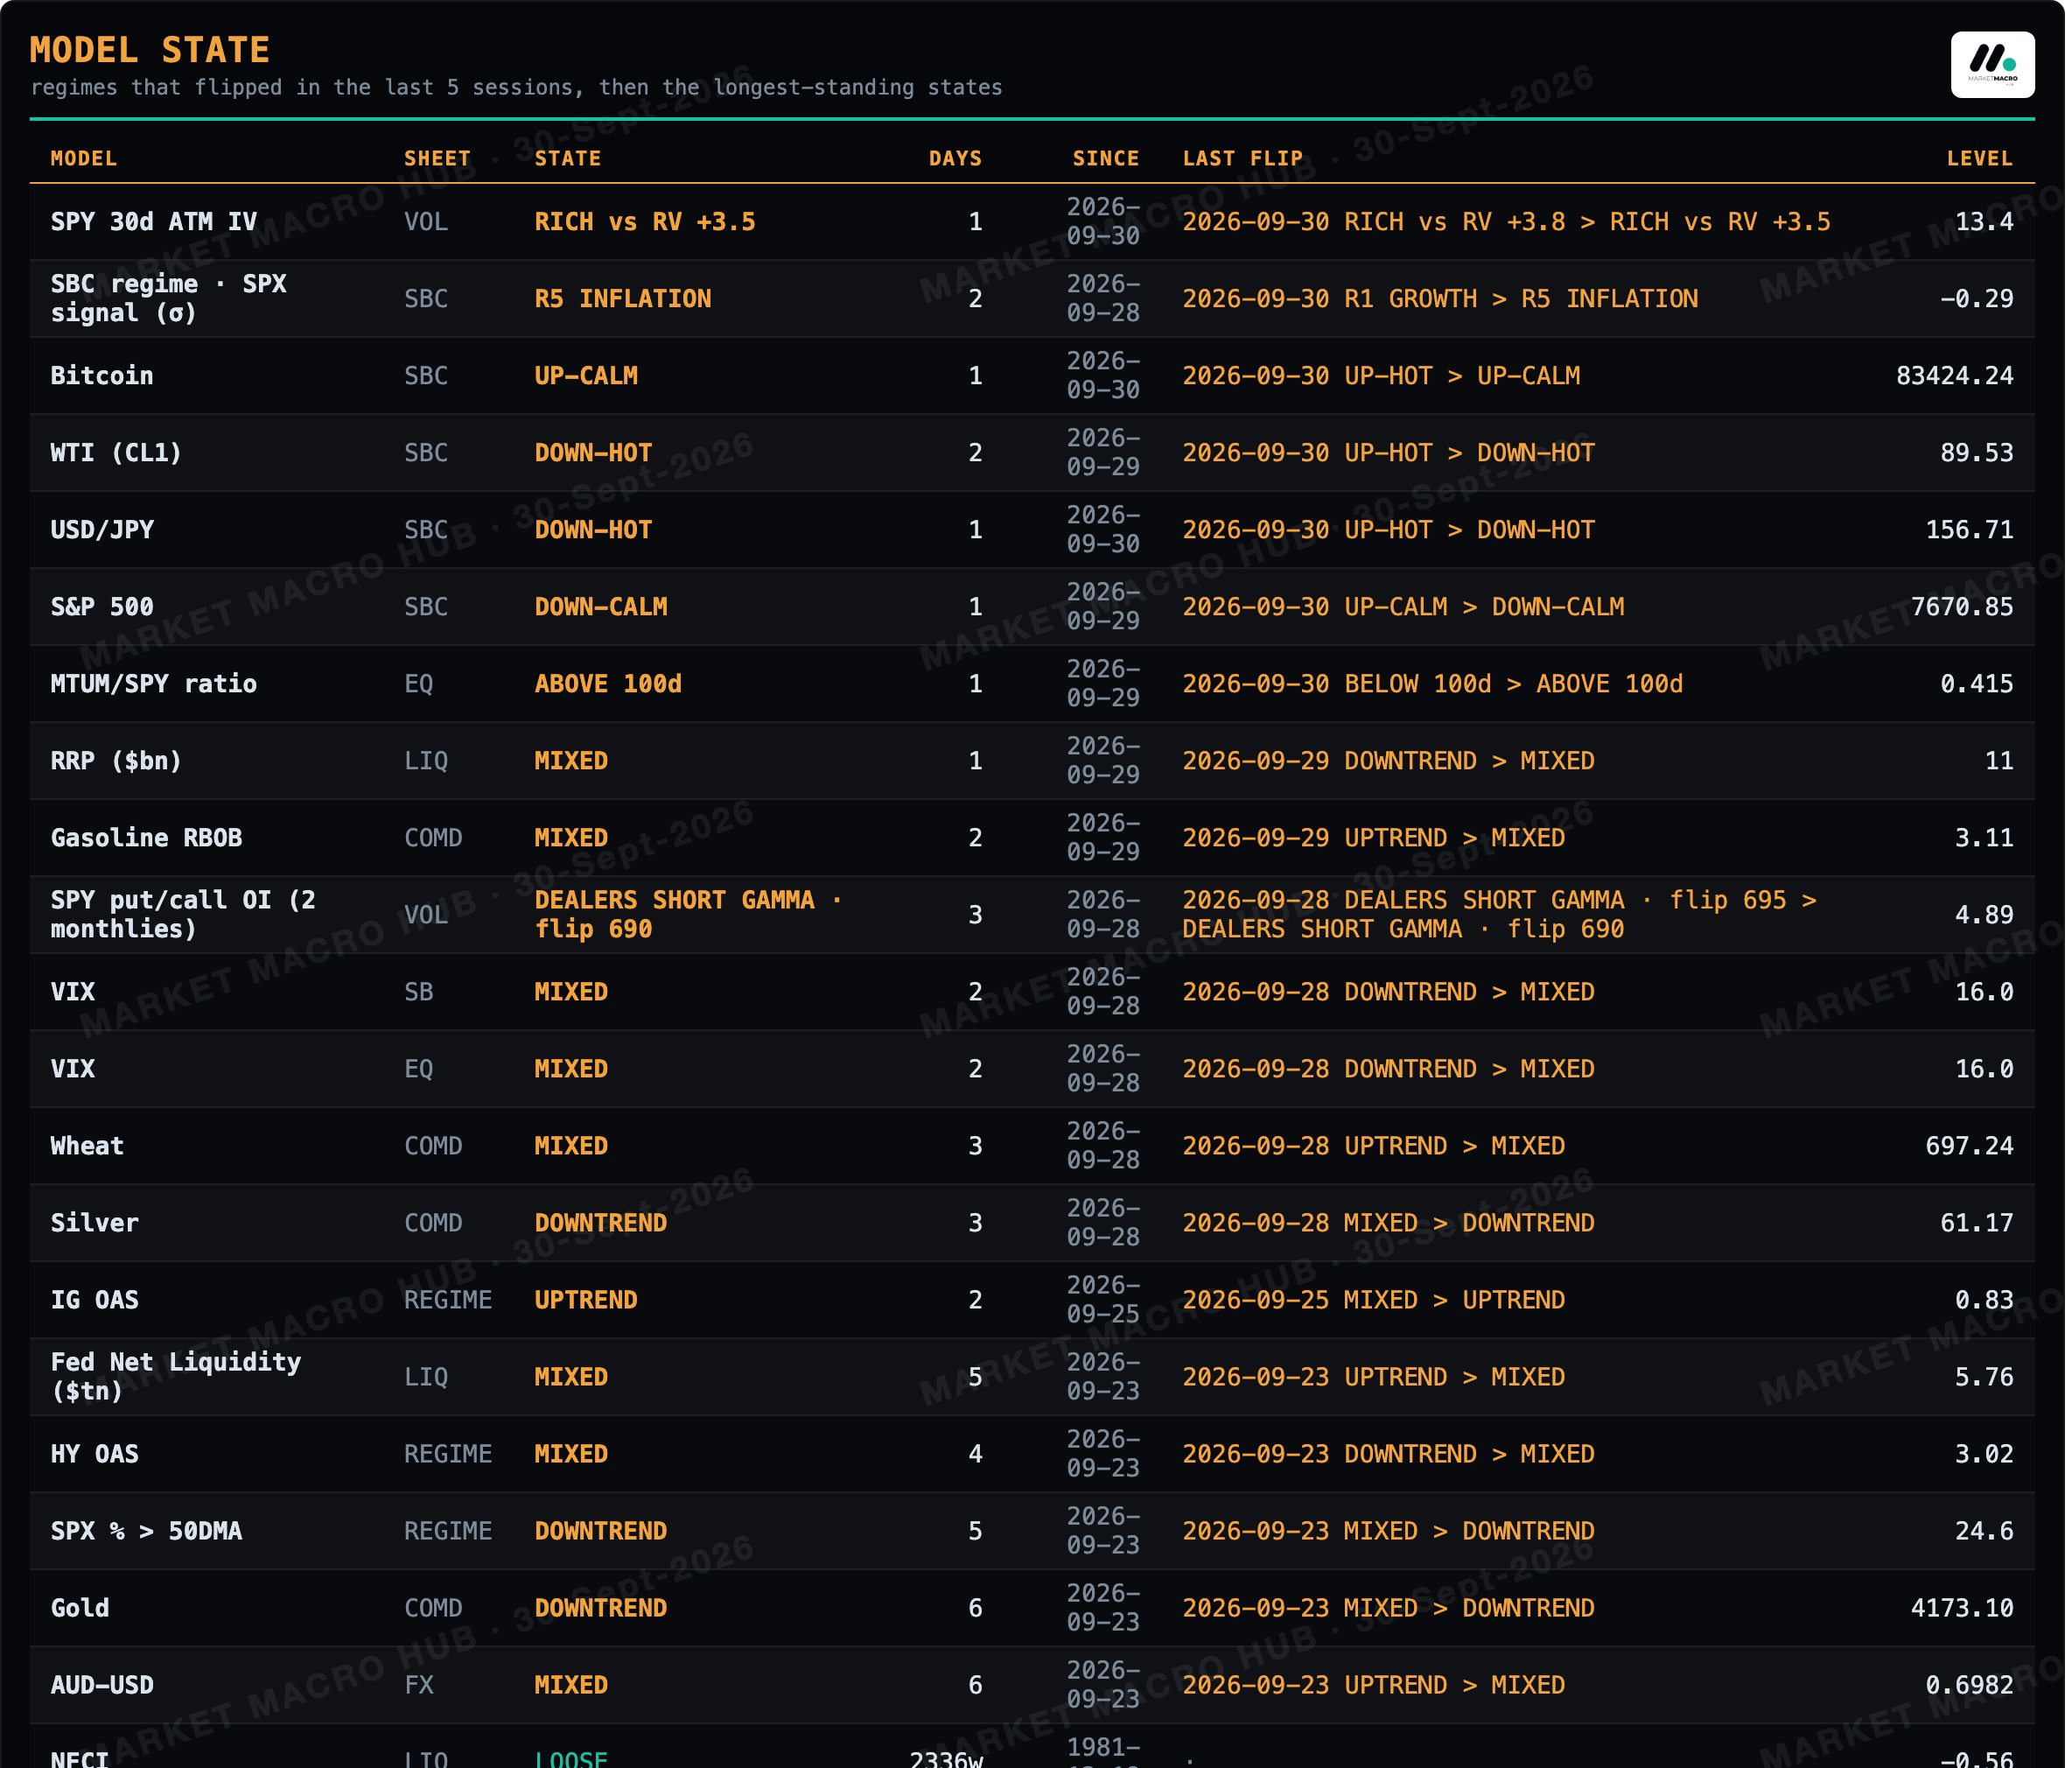
Model State
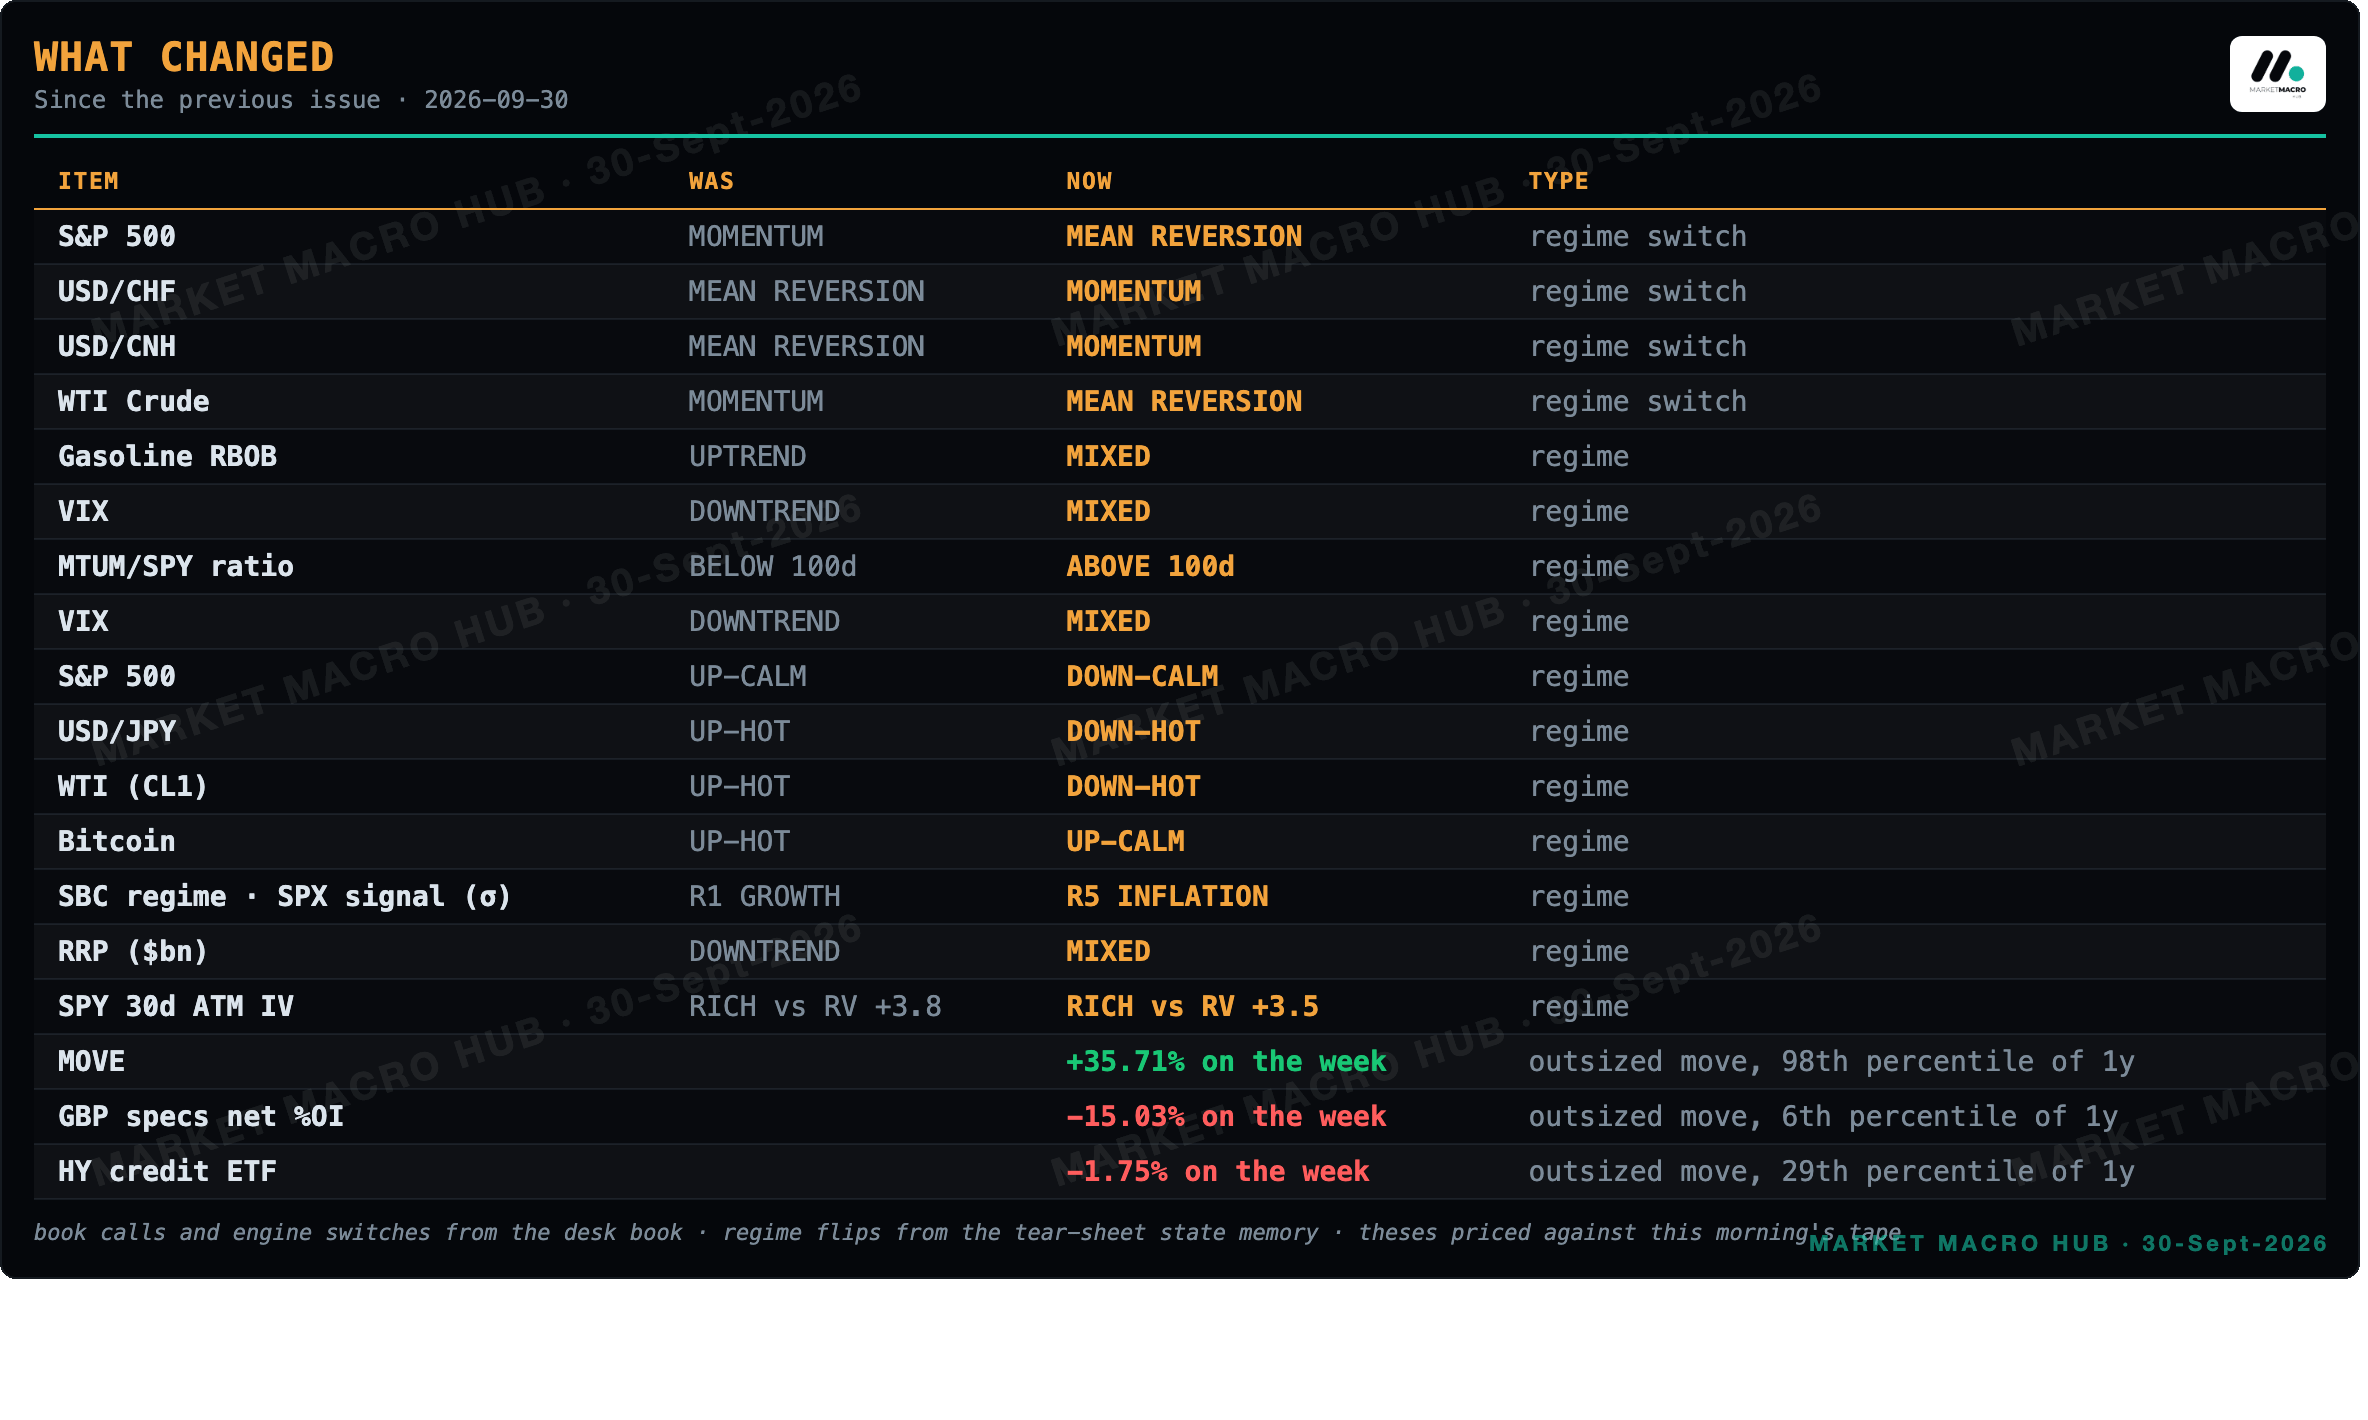
20 model states flipped inside the last five sessions: SPY 30d ATM IV to RICH vs RV +3.5, SBC regime · SPX signal (σ) to R5 INFLATION, Bitcoin to UP-CALM, WTI (CL1) to DOWN-HOT and more.
Measured Books · E1 to E5
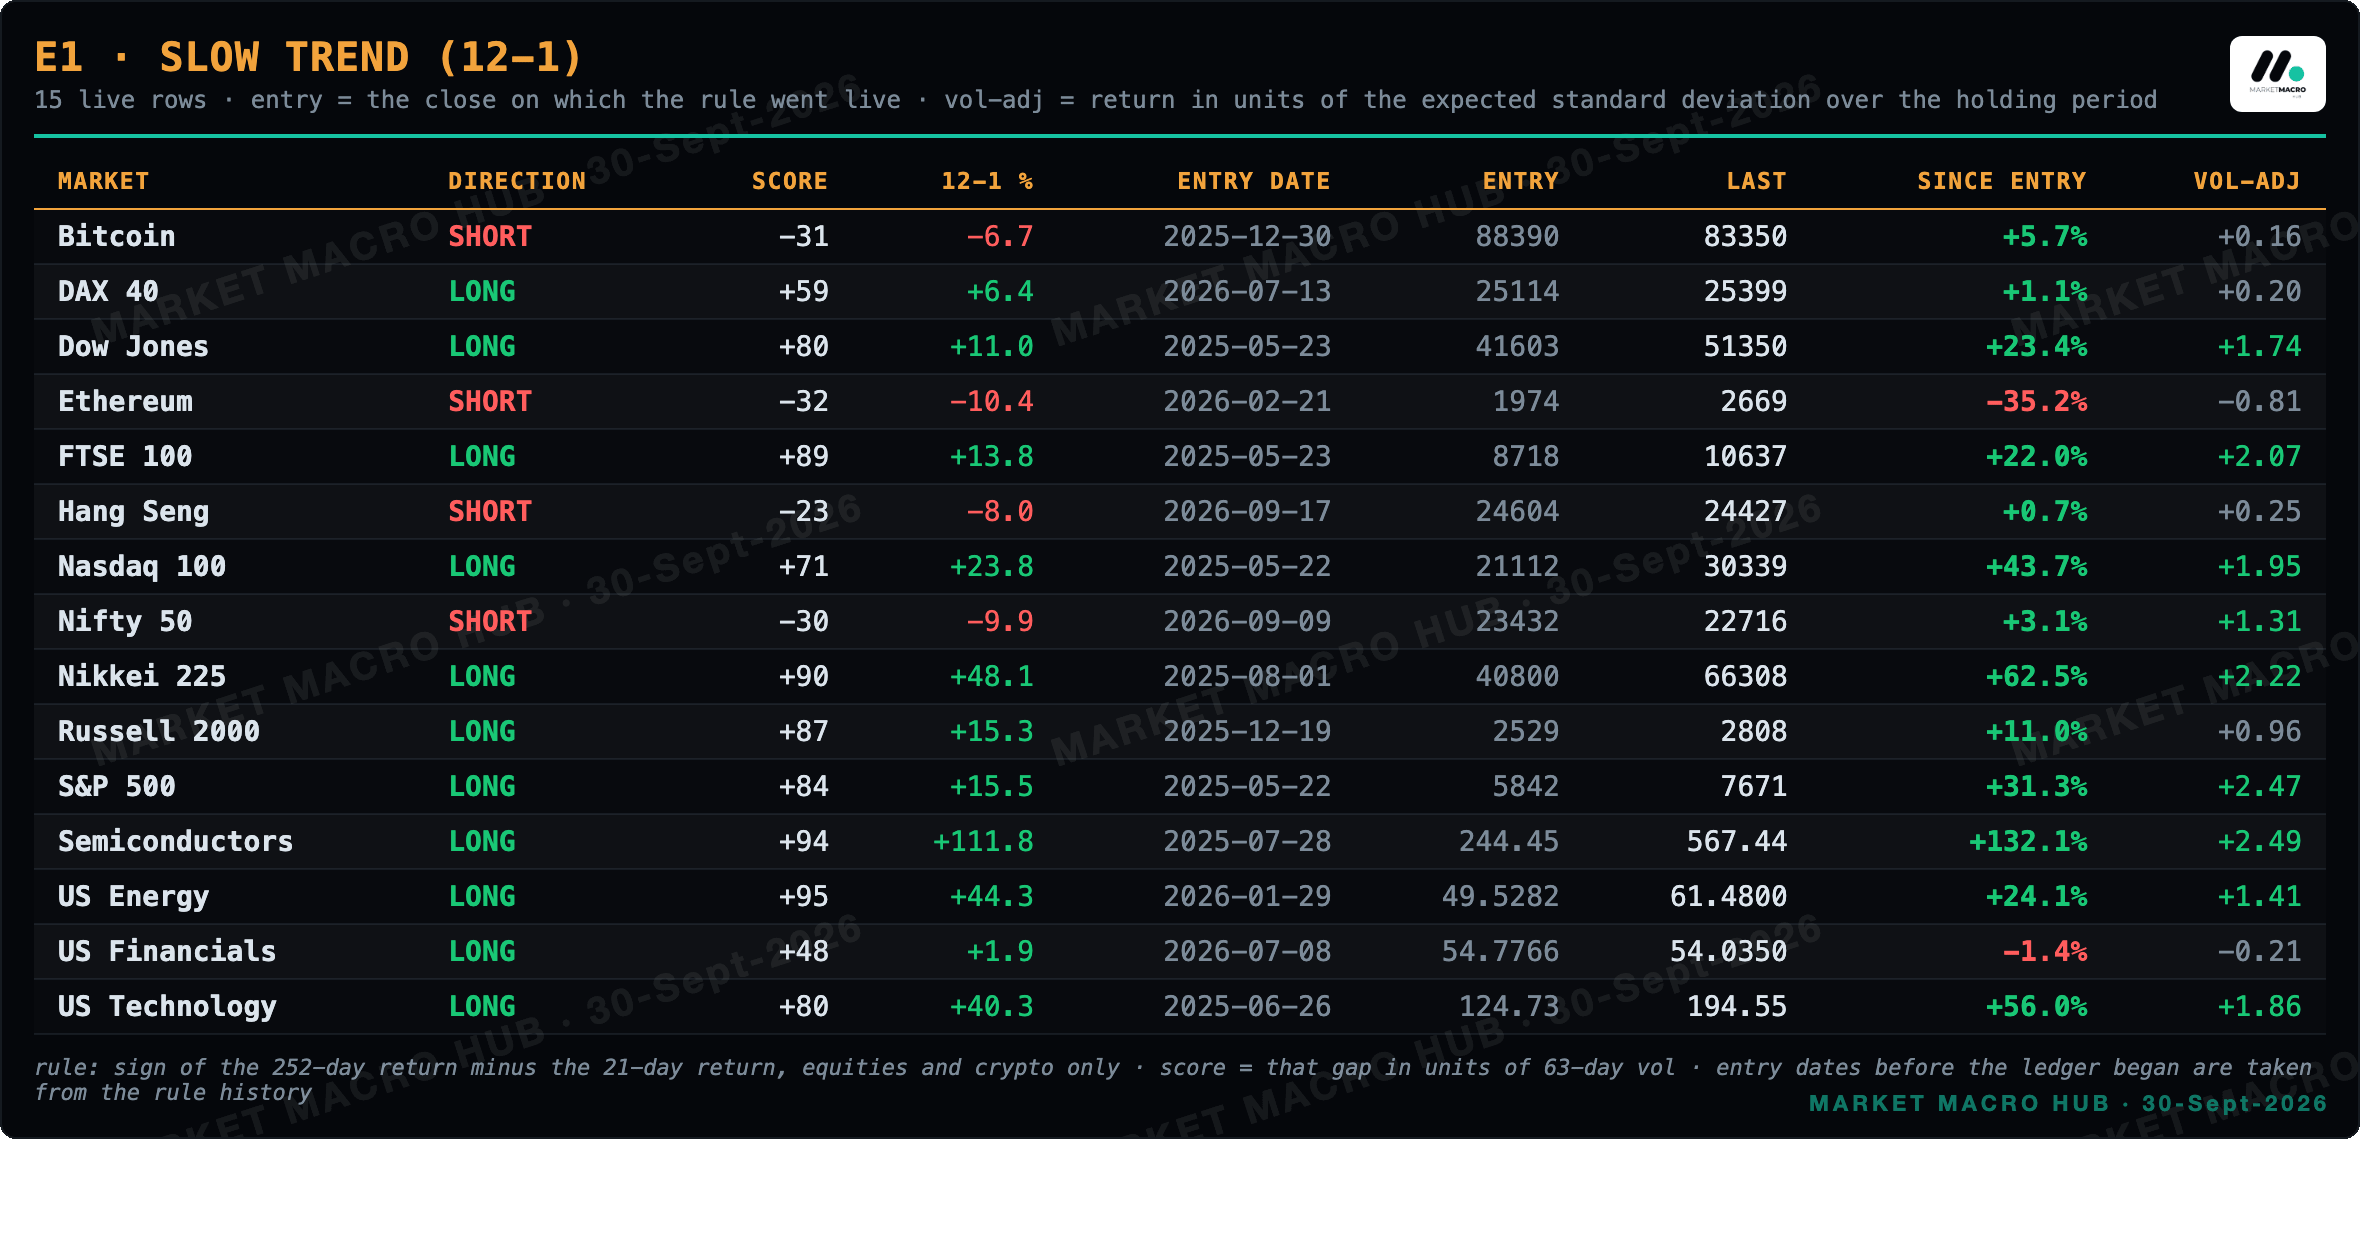
E1 since entry: 15 live rows, 13 positive, average +25.3%, median +1.41 vol-adjusted.
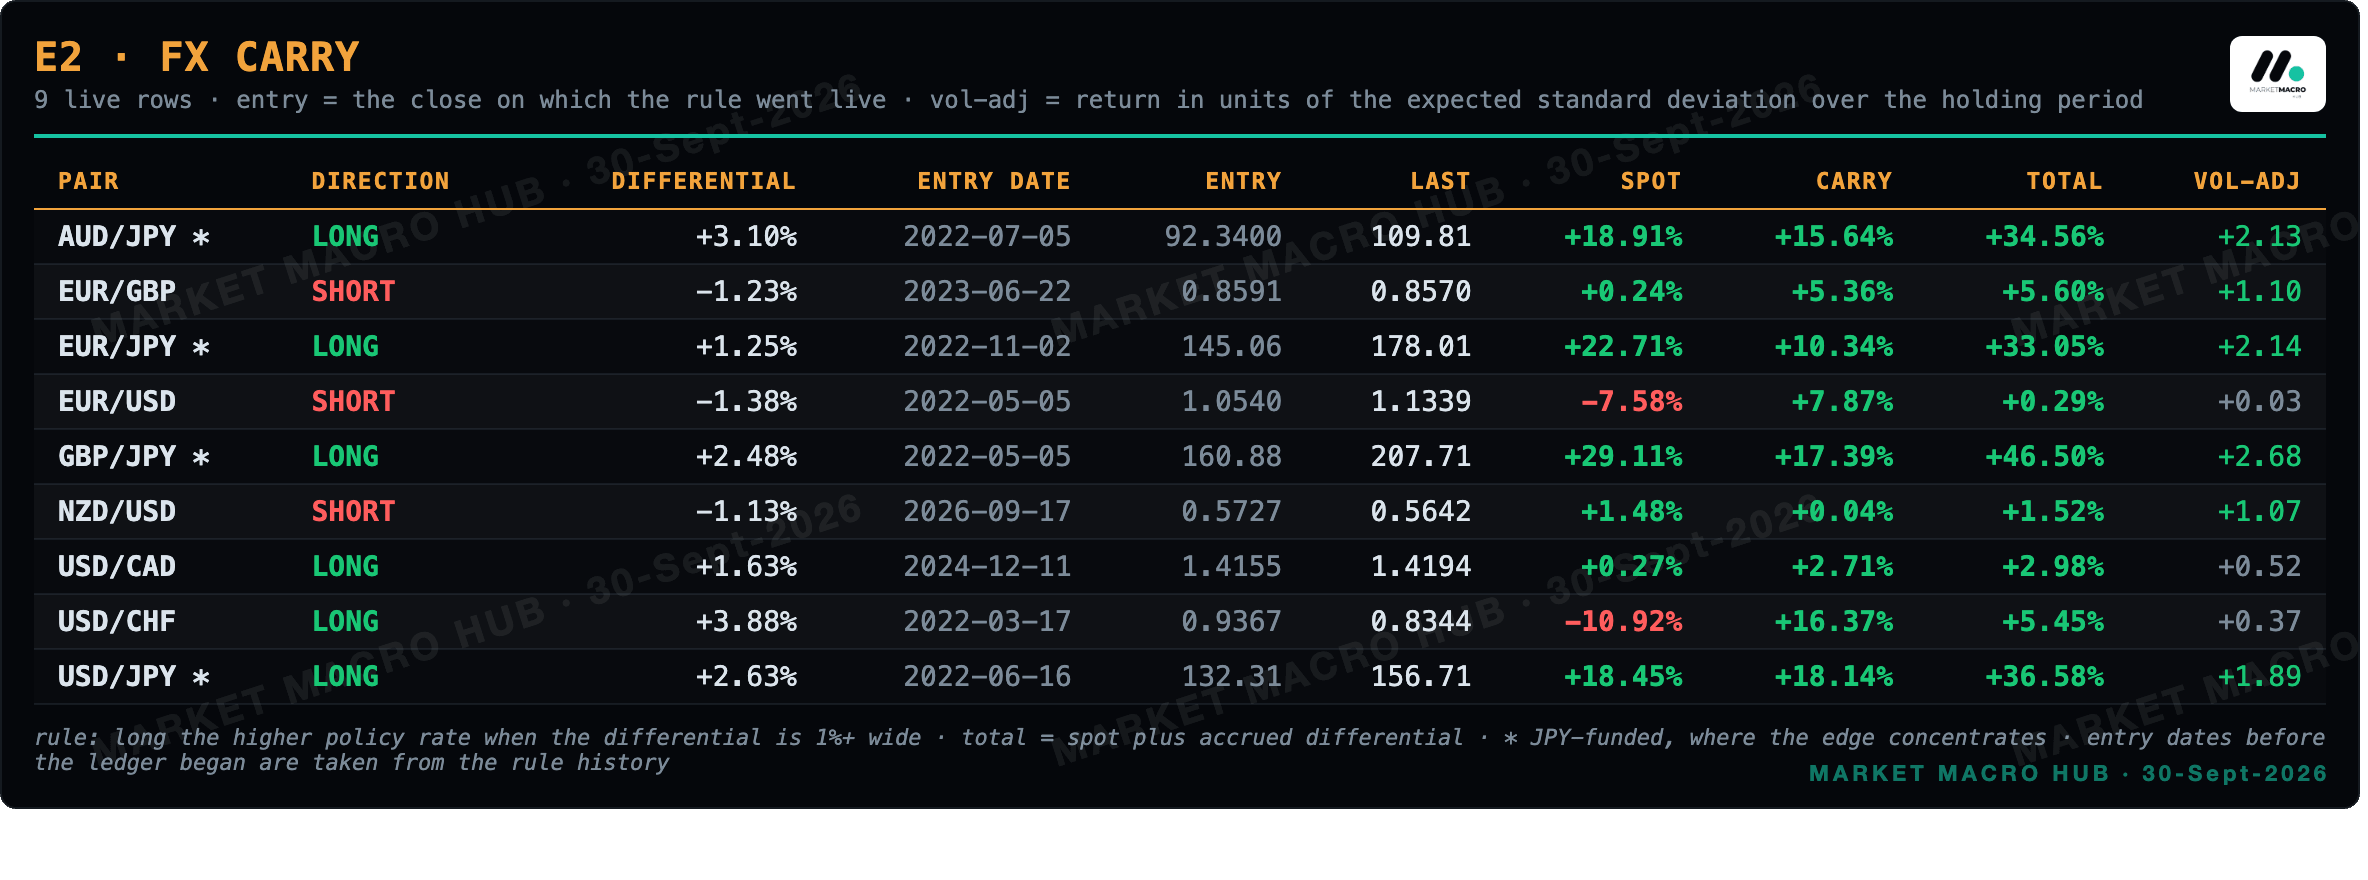
E2 since entry: 9 live rows, 9 positive, average +18.5%, median +1.10 vol-adjusted.
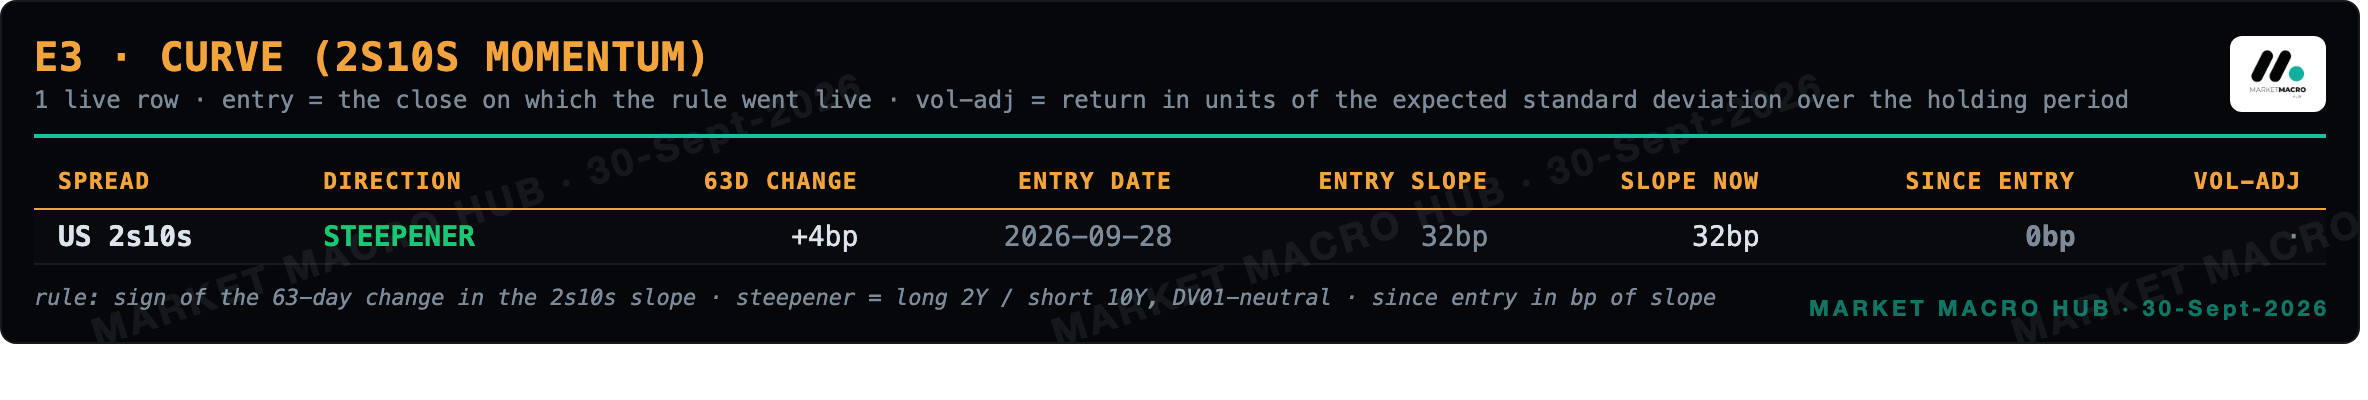
E3 since entry: LONG US 2s10s from 2026-09-28, 0bp over 0 sessions.
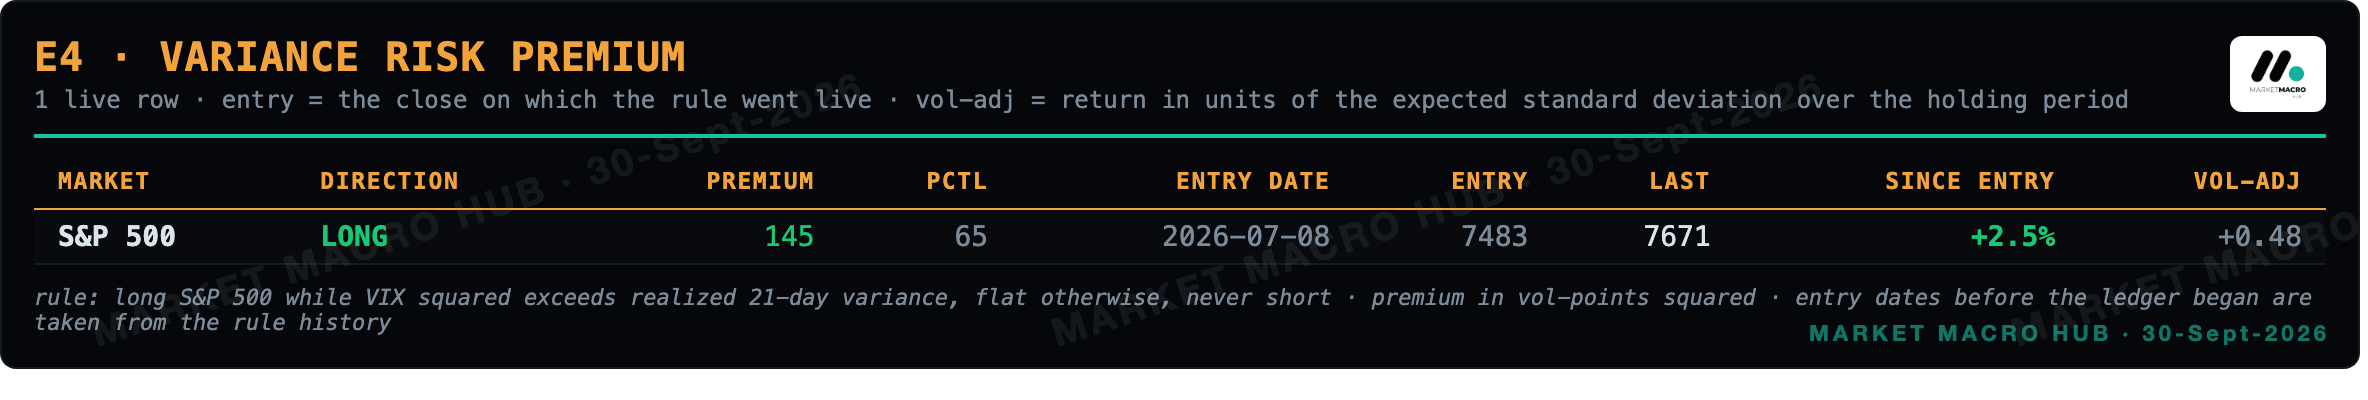
E4 since entry: LONG S&P 500 from 2026-07-08, +2.5% over 58 sessions (+0.48 vol-adjusted).
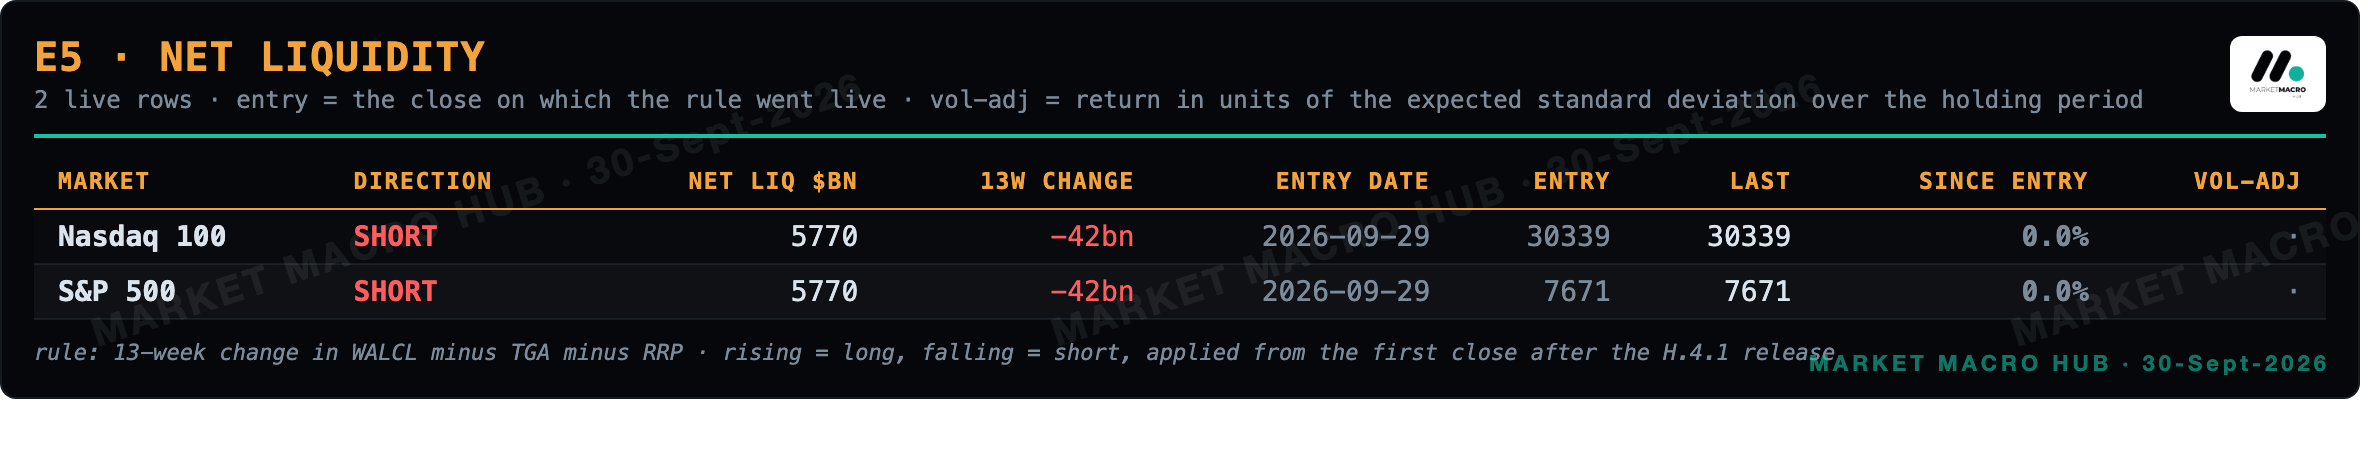
E5 since entry: 2 live rows, 0 positive, average 0.0%.
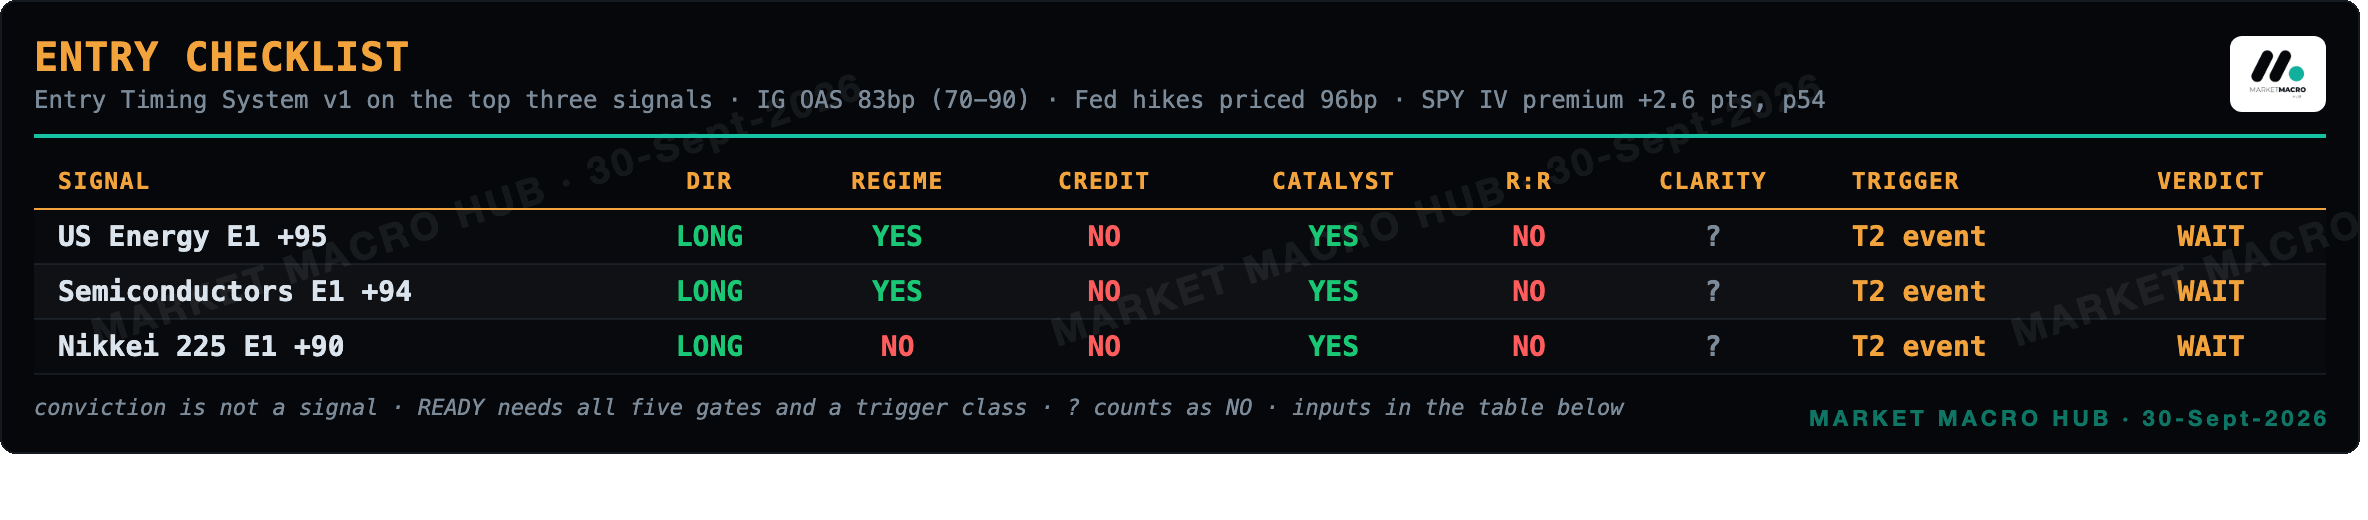
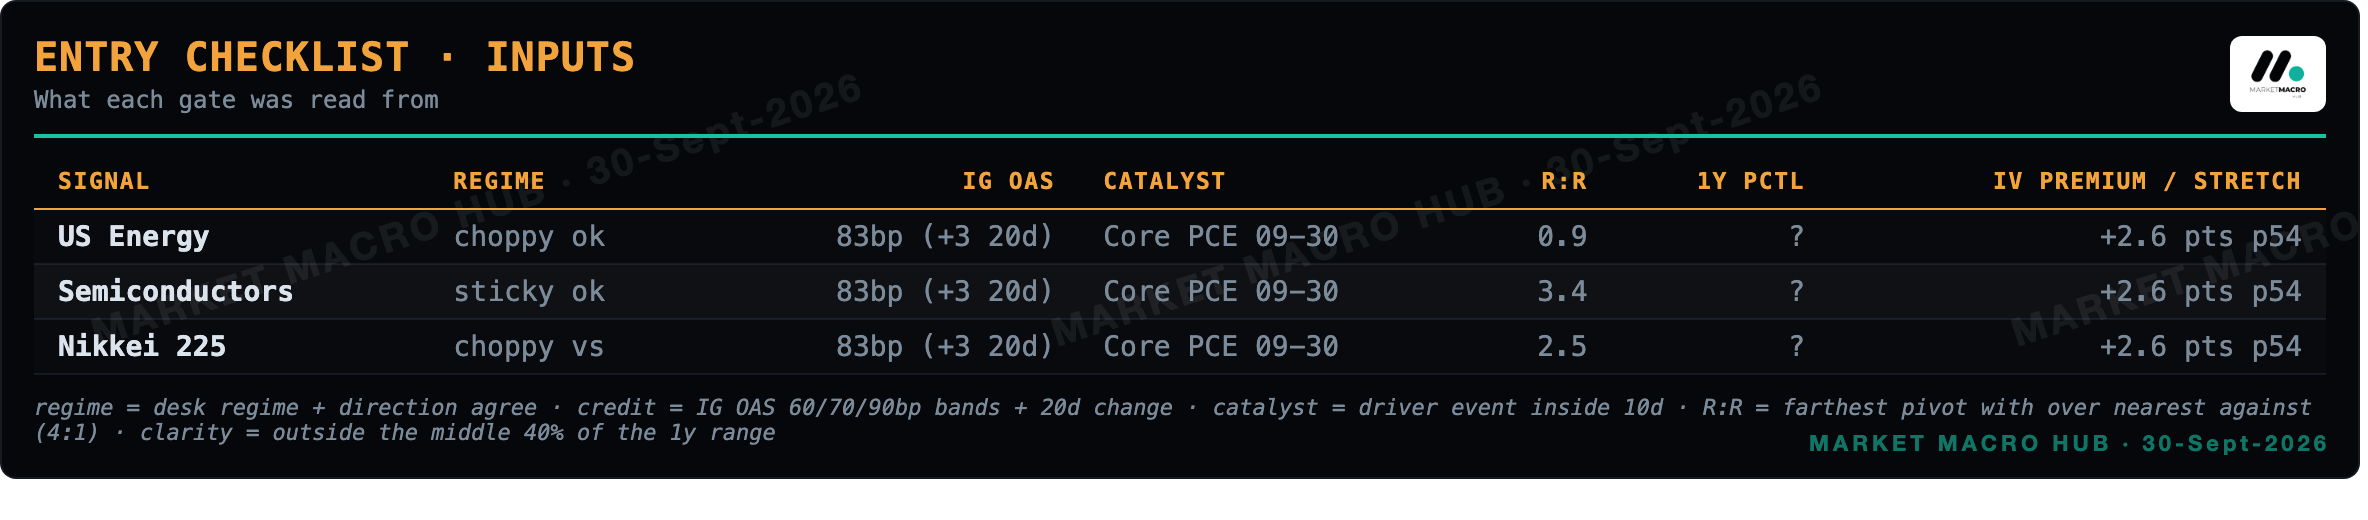
Entry Checklist
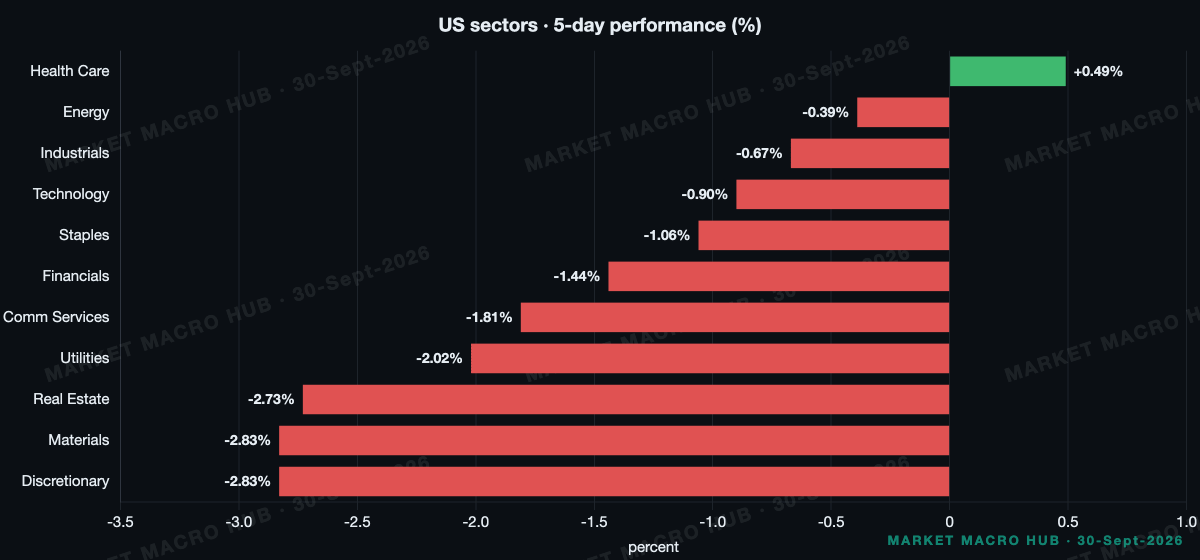
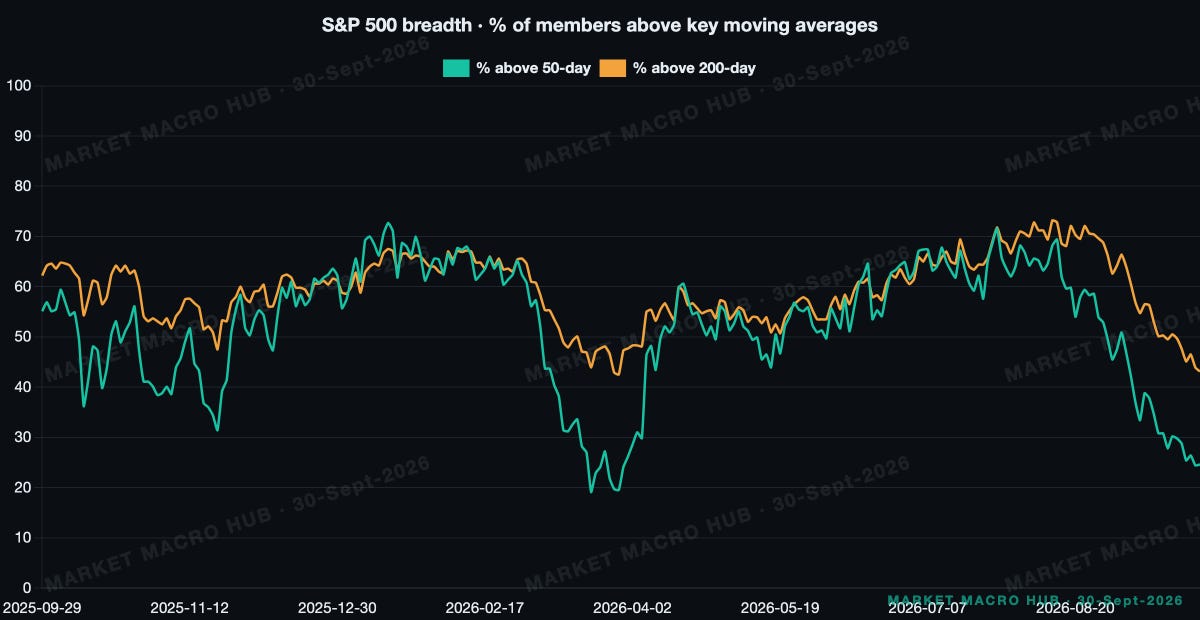
Sector Snapshot & Breadth
Stock-Bond Correlation
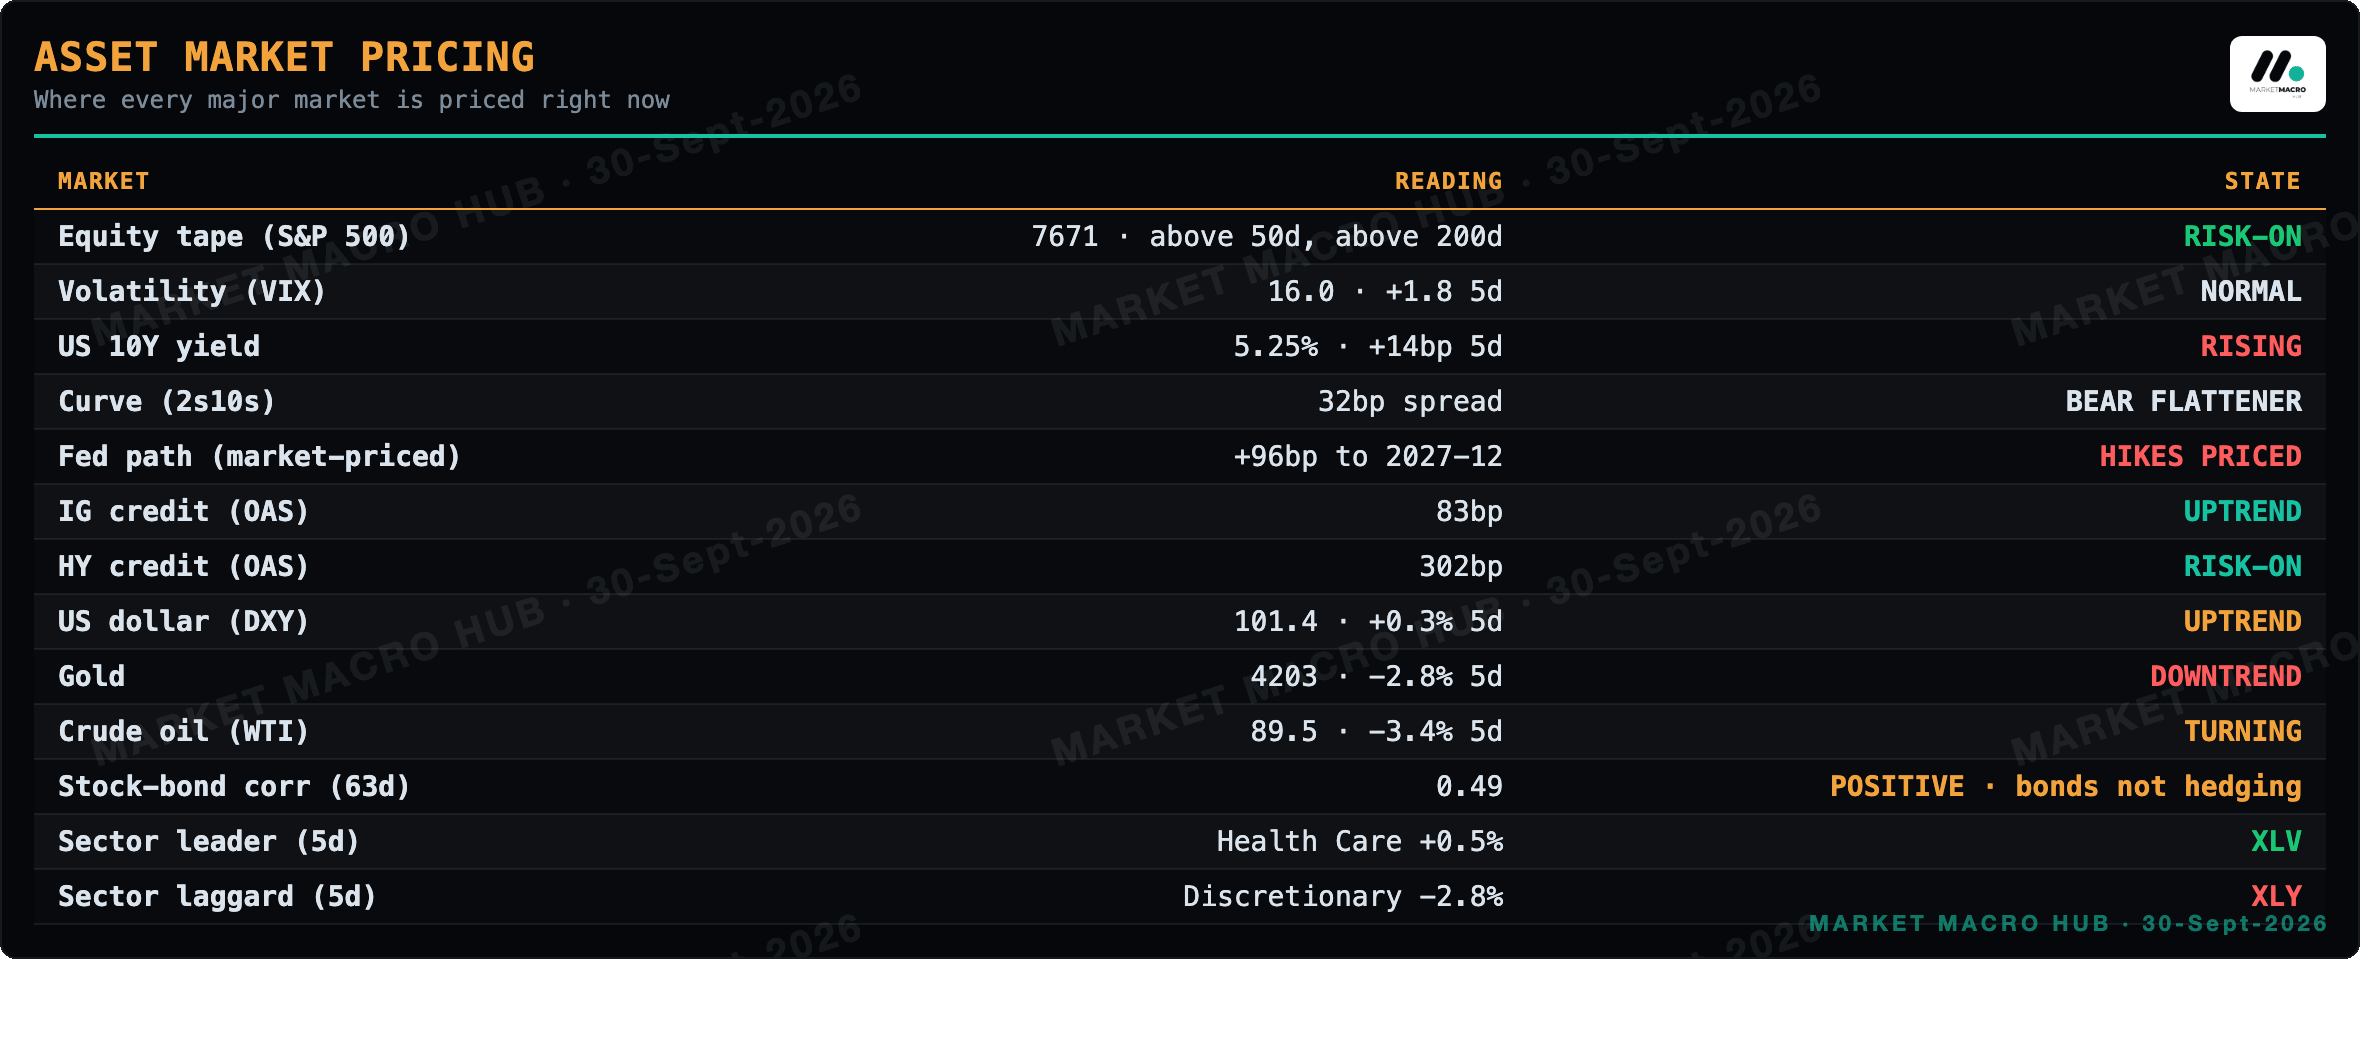
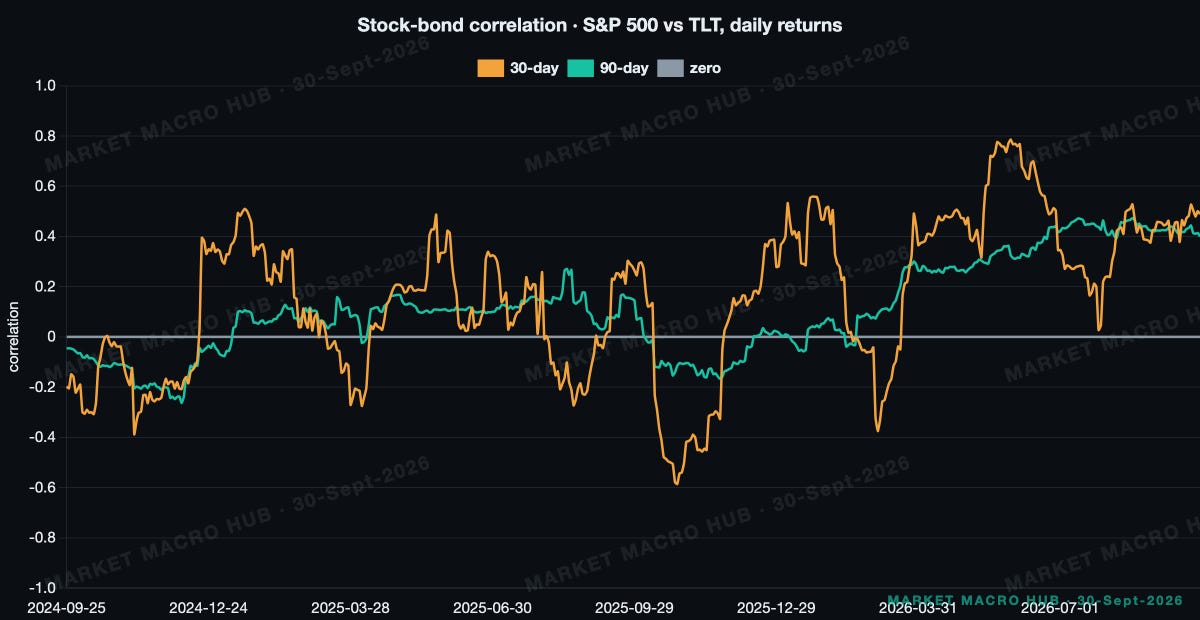
S&P 500 vs TLT, daily returns: 30-day 0.49, 90-day 0.40, positive, so bonds are not hedging equity risk.
Scenarios for the Week
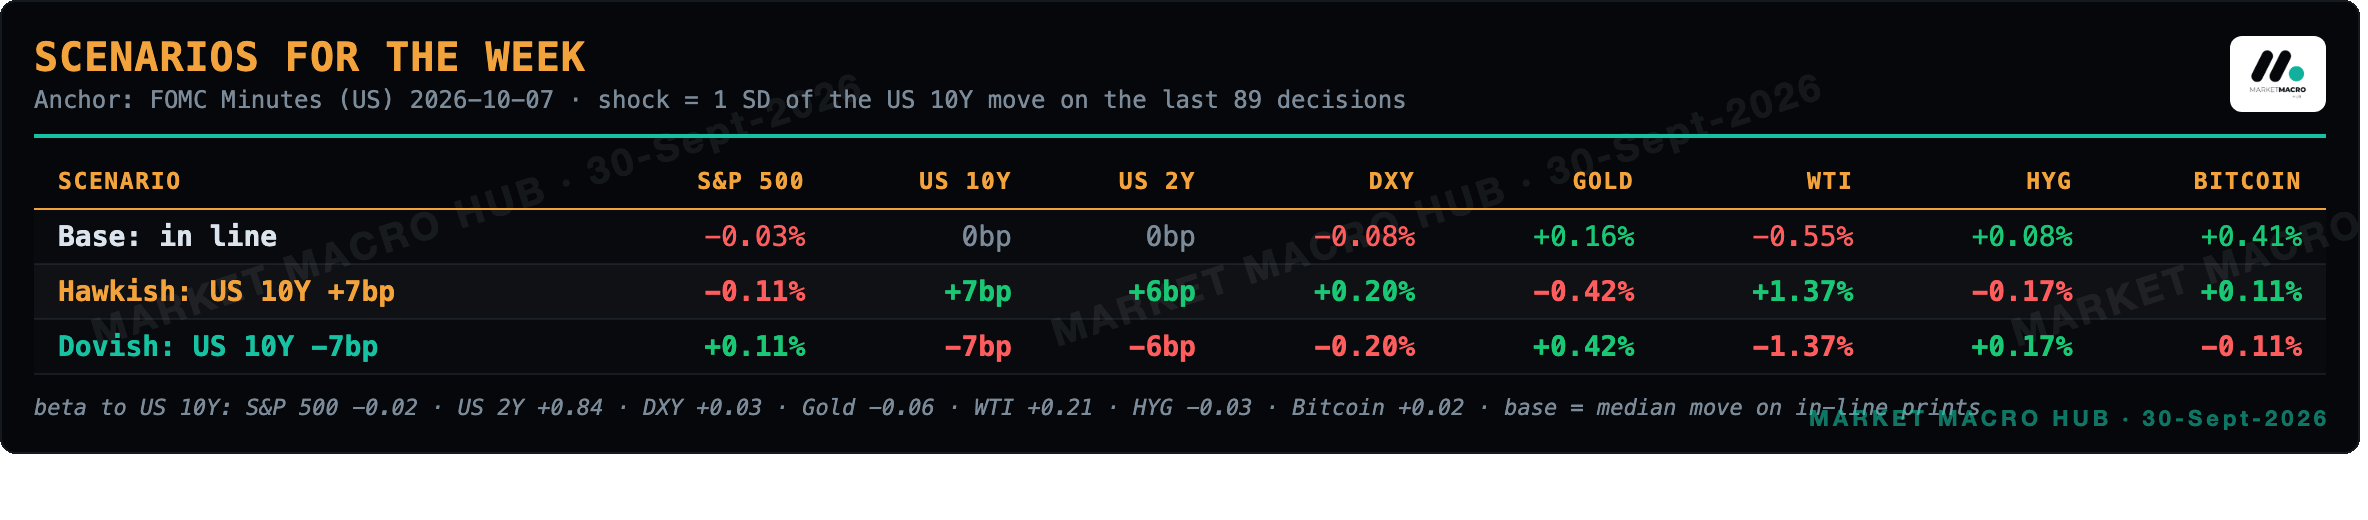
Expected moves are conditional means from 2-year betas to the anchor times a 1-standard-deviation event-day shock, not forecasts.
Release Playbook
Main Developments in Macro
FED'S BARR SAYS FURTHER POLICY ADJUSTMENTS LIKELY NEEDED, INFLATION RISKS HAVE INCREASED, LABOUR RISKS REDUCED
FED'S WILLIAMS SEES NO NEED FOR URGENCY AFTER SEPTEMBER HIKE, MOMENTUM STRONG AND MAY BE STRENGTHENING
FED'S GOOLSBEE WARNS AI PRODUCTIVITY EXPECTATIONS CREATE HIGH DANGER OF OVERHEATING NOW
US PCE, CORE PCE AND GDP FINAL ALL DUE TODAY; ATLANTA FED GDP ALSO ON DECK
CHINA OFFICIAL MANUFACTURING PMI MATCHES AT 50.1, NON-MANUFACTURING BEATS AT 50.2
OIL SOFTER ON US/IRAN RHETORIC, TRUMP BACKING RUSSIA SANCTIONS RELIEF, DOE OFFERS UP TO 40MLN SPR BARRELS
PBOC CUTS PLEDGED SUPPLEMENTARY LENDING RATE 25BP TO 1.50%
The recent prints lean soft on demand, firm on housing. CB Consumer Confidence came in at 81.9 against 89.2 expected and JOLTs openings at 7.079 against 7.23, both misses, yet Case-Shiller home prices ran 2.5% against 2.2%. That mix keeps the Fed's inflation worry intact while growth cools at the edges, which is exactly why today's core PCE at 0.3% consensus matters so much.
Cross-Asset Read
Nothing led the tape yesterday. Utilities and Communication Services carried the only meaningful positive contributions, roughly +0.03pp and +0.02pp, while financials dragged at -0.04pp. The sector split explained less than half the -0.17% index move, so I read the day as noise around a flat close.
The real action is in rates. US 10Y added +7bp on the day and +28bp on the week, and the long UST ETF had its worst week in the sample. That bond rout is the story equities are ignoring.
One correlation shift matters for hedges. SPX versus Bitcoin flipped to +0.48 from near zero, so crypto no longer diversifies the equity book. Credit gives me no alarm, IG at 83bp sits mid-range against its 89bp mean and HY at 302bp says the same.
Rates & Fed Pricing
No month on the strip has a cut half-priced, so this is entirely a tightening conversation. December is the first fully-priced hike at roughly 100% odds. Cumulatively the strip builds +27bp by December and peaks at 4.84% in December 2027, +96.5bp over an EFFR of 3.88%.
The terminal repriced +19bp this week, and Barr's line that inflation risks have risen while labour risks have fallen is the fuel. What changes my mind on the stretched-hikes call is bear flattening in 2s10s from here; the curve slipping to 32bp is the early warning.
The Week Ahead
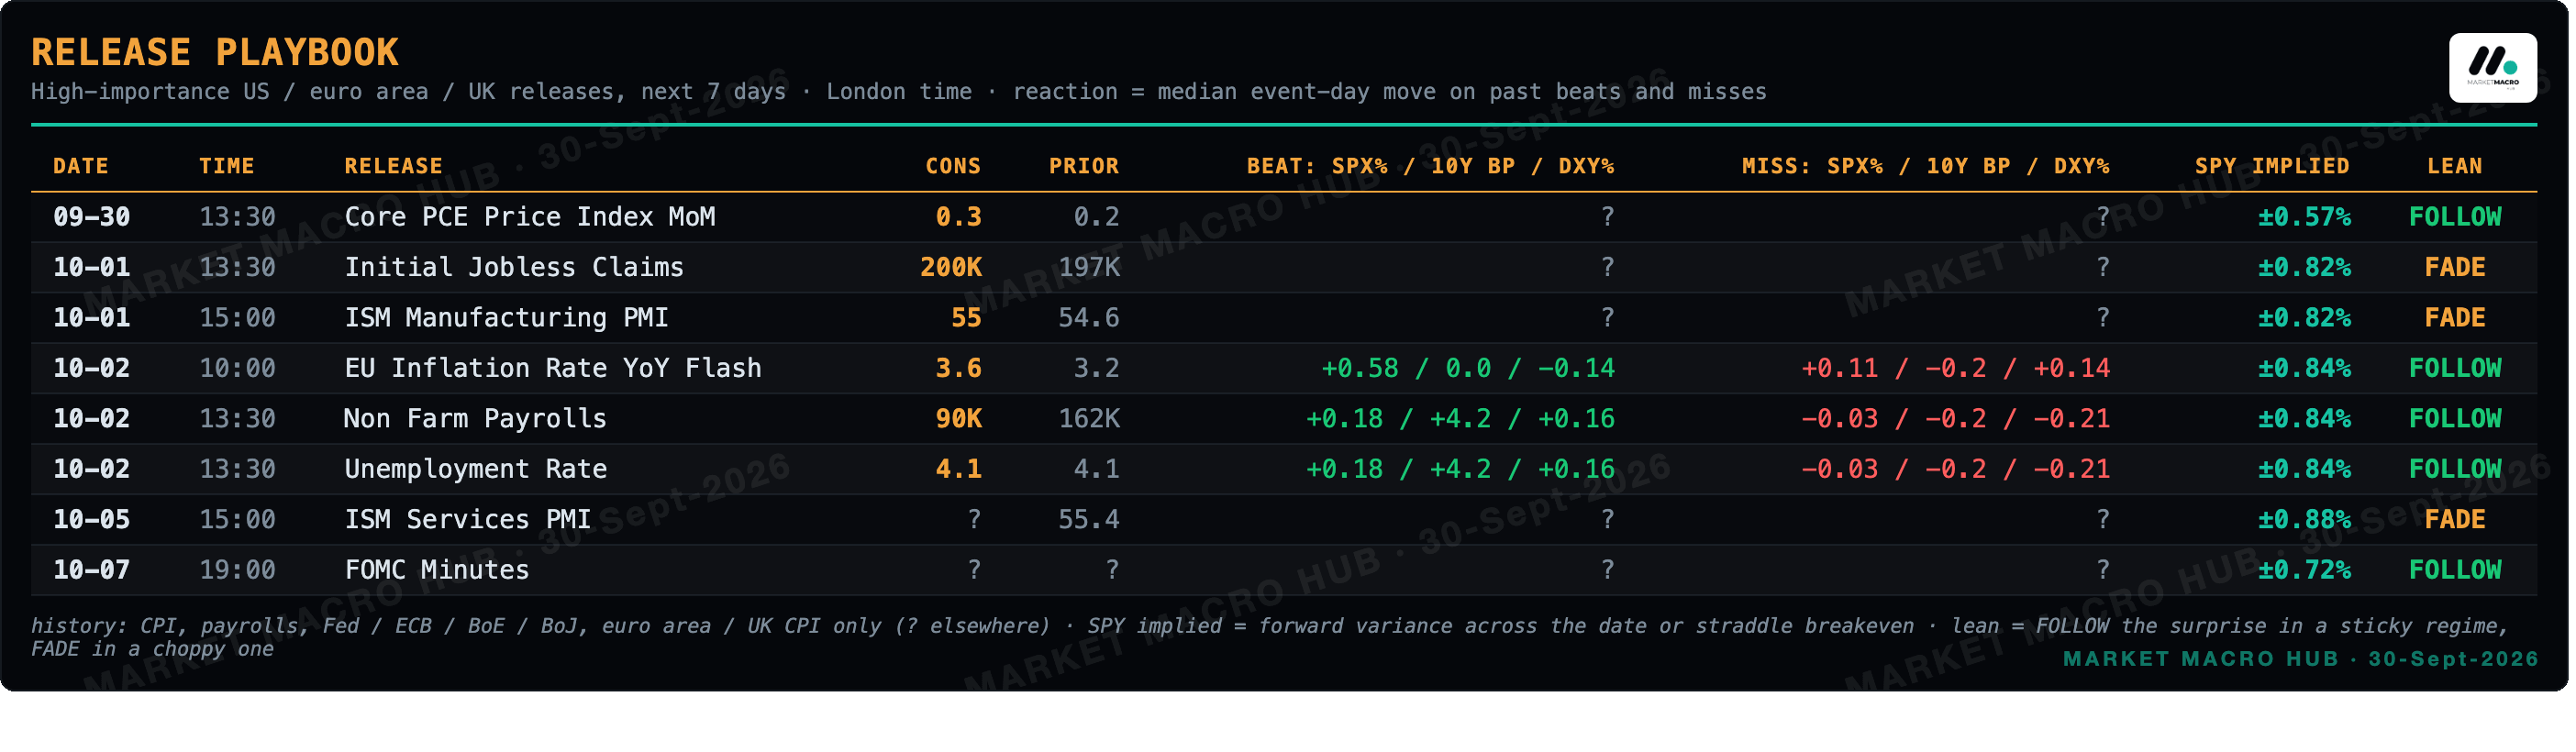
Wednesday: Core PCE MoM, the print that decides how hard December sits; a hot number hardens my hike lean.
Wednesday: GDP Growth Rate QoQ Final at 1.5% consensus, watch for confirmation that growth is cooling under the tightening.
Wednesday: ADP Employment Change at 70 consensus, a labour read that feeds Barr's "risks reduced" case.
Wednesday: Personal Income and Spending, spending at 0.8% consensus tells me whether demand is still funding the inflation worry.
Thursday: Initial Jobless Claims, still my cleanest weekly labour tell into the December path.
Tradeable Levels
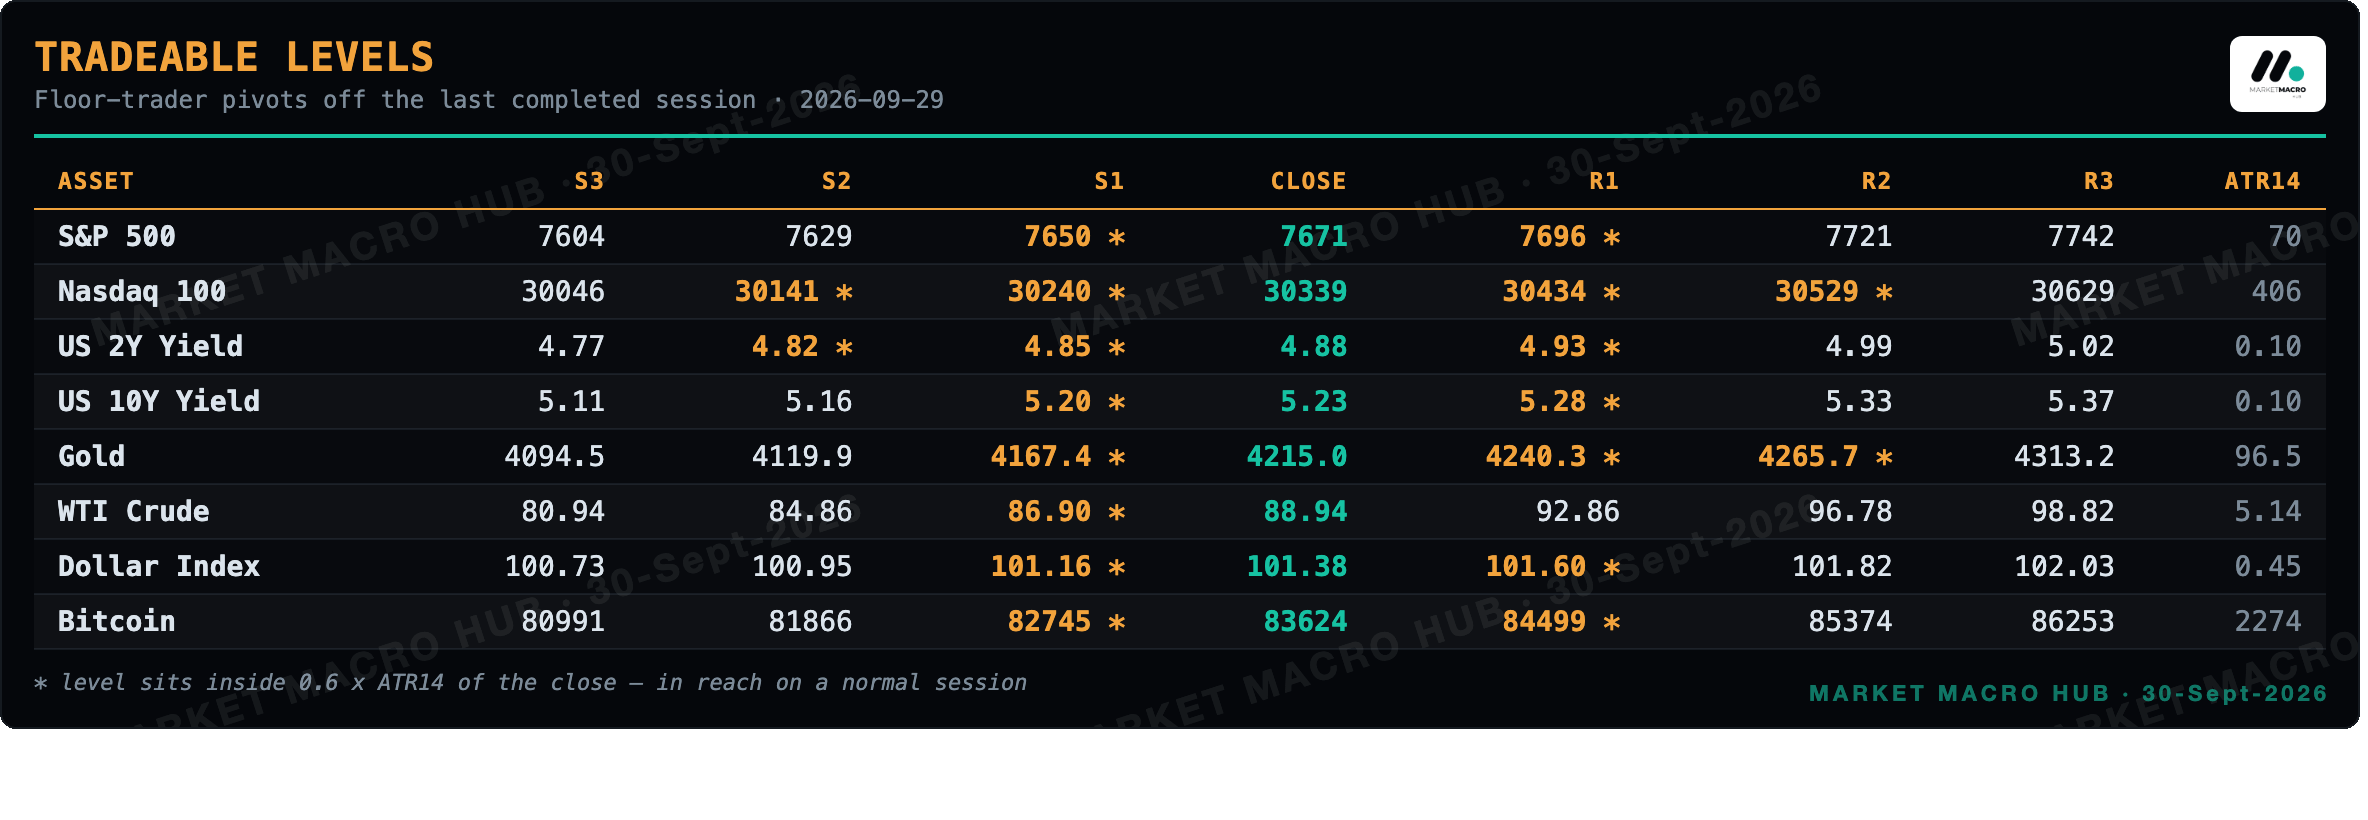
Pivots off the last completed session (2026-09-29). Levels marked * sit within 0.6 x ATR14 of the close.
Vol Screen · Rich and Cheap Implied Vol
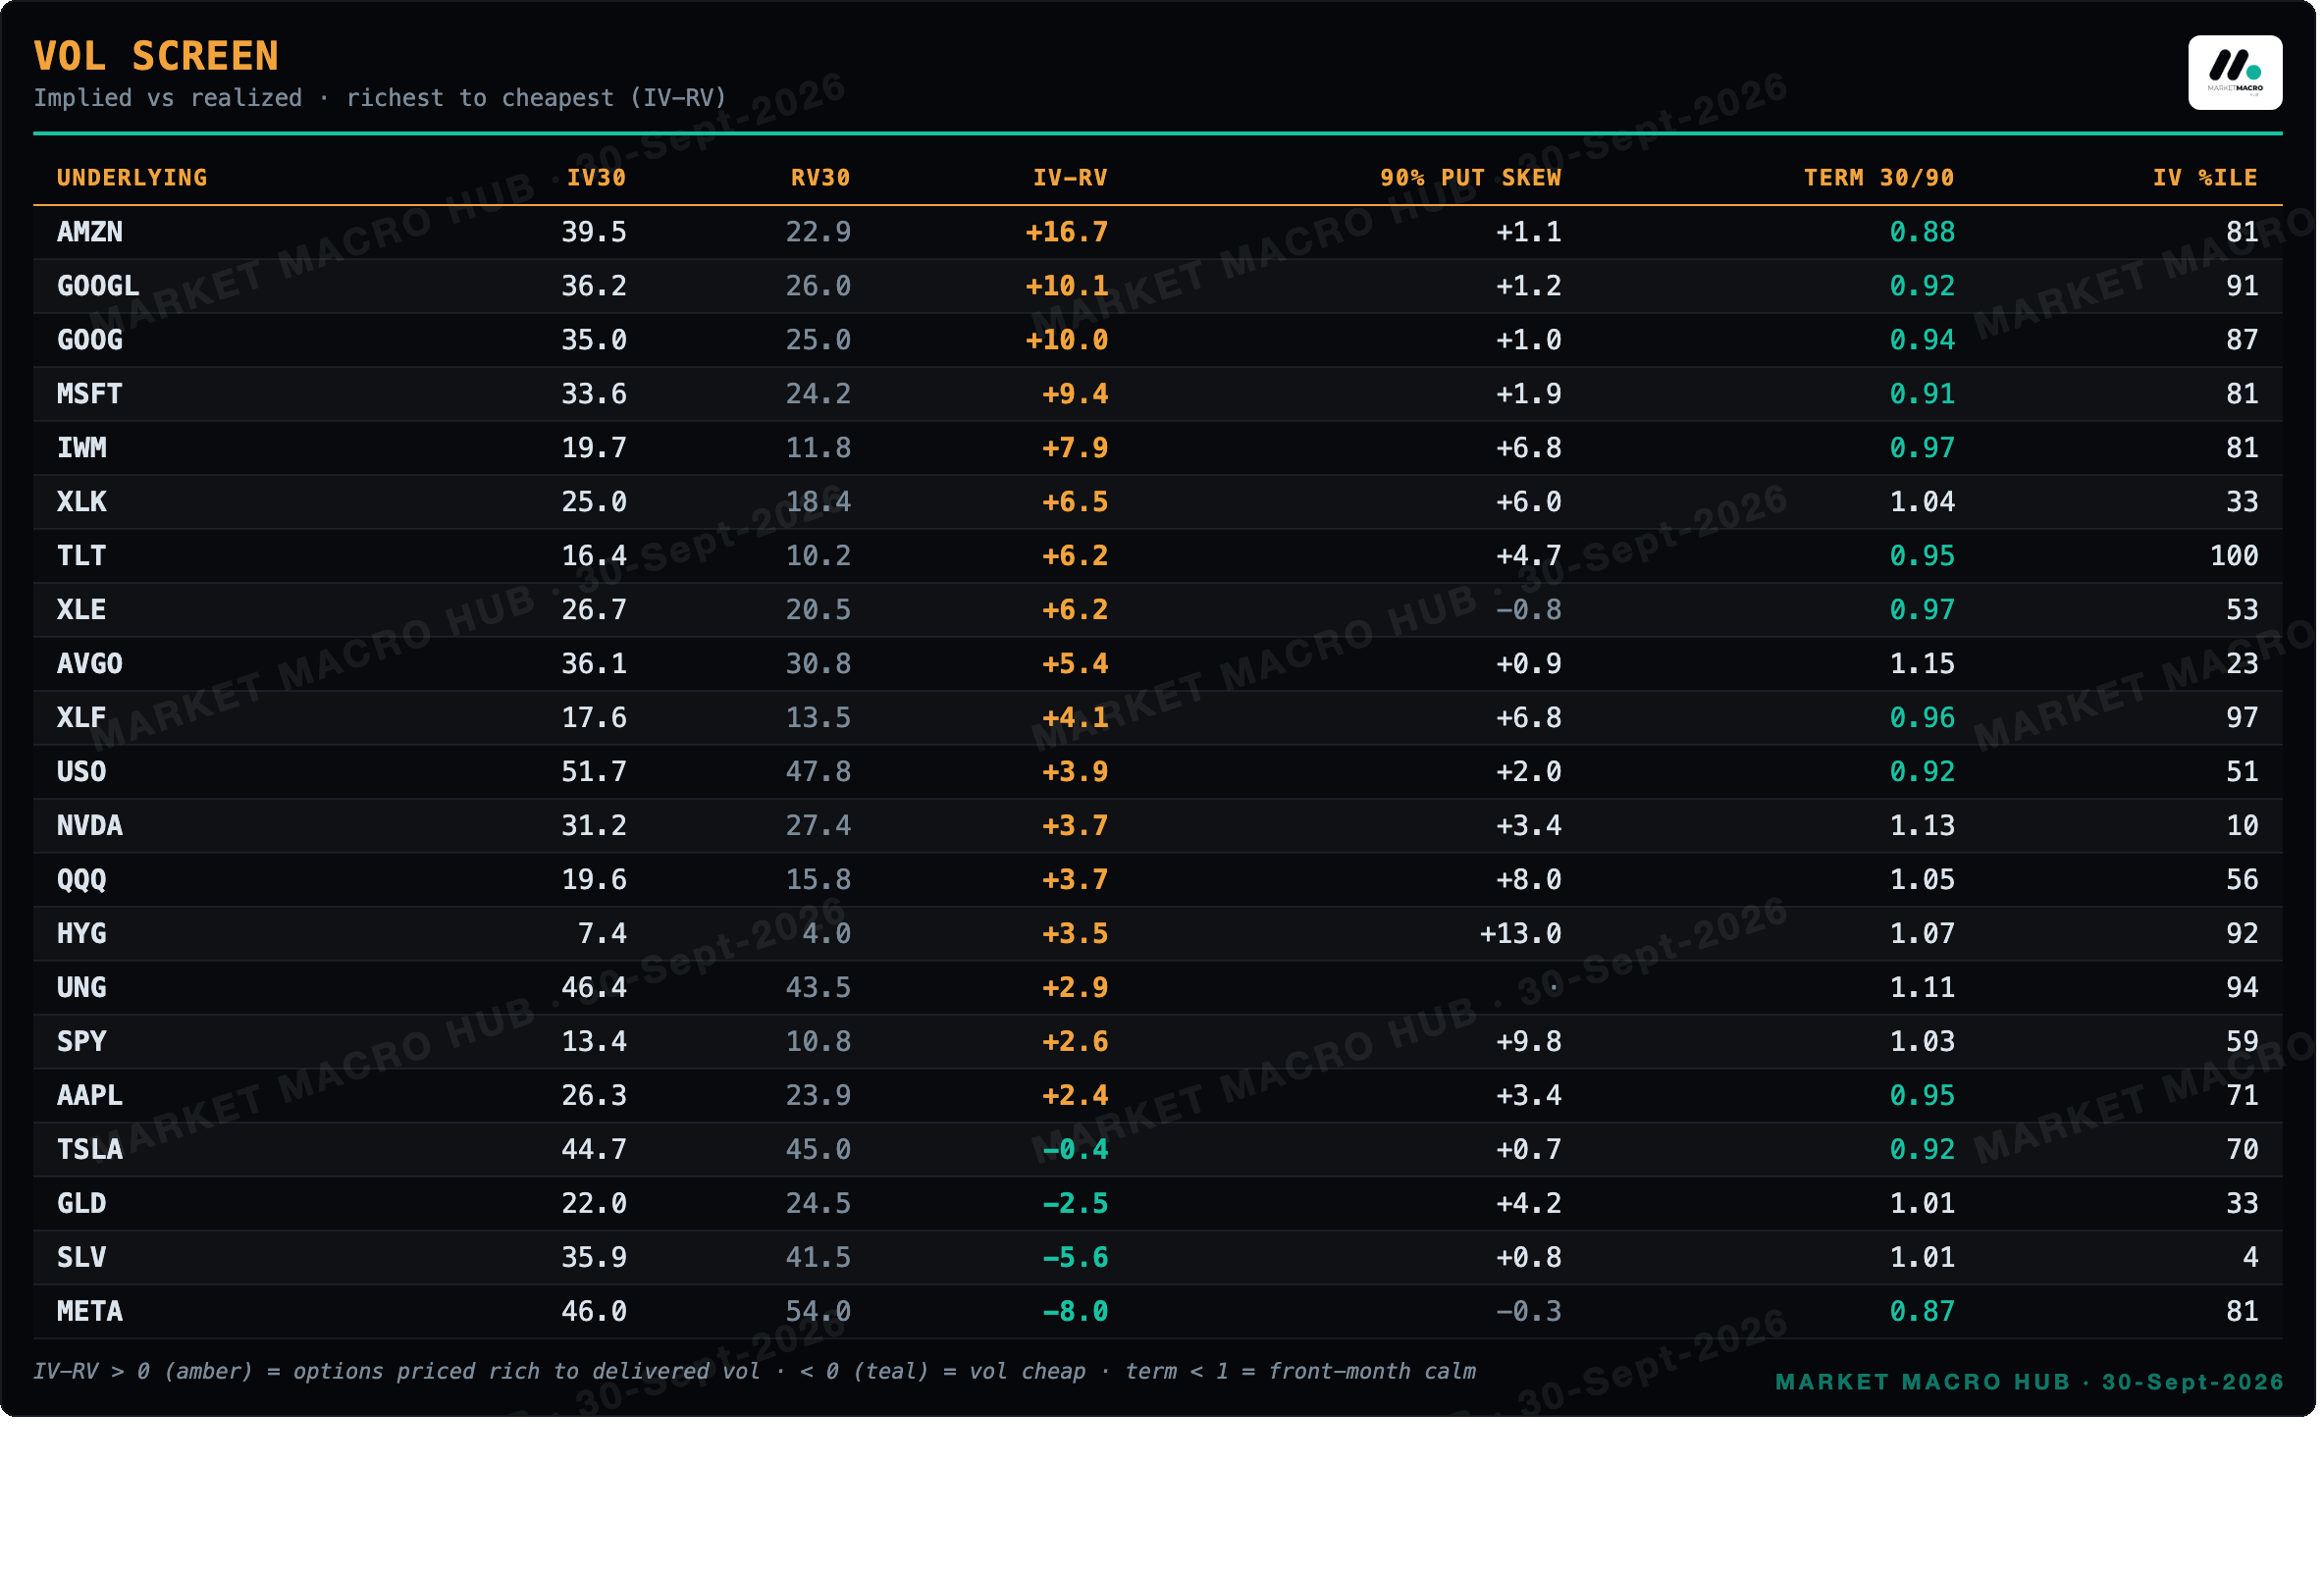
Positive IV-RV = options priced rich to what the tape is delivering (AMZN and GOOGL richest today); negative = vol going cheap (META and SLV). Percentiles are each name's own archive history.
Positioning
Disclaimer
The information in this publication is provided for informational and educational purposes only and is believed to be reliable, but its accuracy and completeness are not guaranteed. Nothing herein constitutes investment advice, an offer, or a solicitation to buy or sell any security, derivative, digital asset, or other financial instrument, nor a recommendation suited to any specific reader. All figures are drawn from the day's computed data set at the time of generation and may be delayed, revised, or superseded. Markets involve risk, including the possible loss of principal; past performance and historical relationships do not guarantee future results. Readers should conduct their own research and consult a qualified financial adviser before making any investment decision. The author may hold positions in instruments discussed. This publication is licensed for the personal use of the subscriber only: redistribution, reproduction, or resale in any form is prohibited. © 2026 MARKET MACRO HUB. All rights reserved.