


Today's Tear Sheets
The full daily pack is attached below · six PDFs generated from the same computed data set as this note:
Macro Regime · curve regimes, growth x inflation quadrant, breadth, credit, vol term structure, liquidity, stock-bond correlation, crypto cross-asset, housing
Fixed Income · UST complex, global curves, Fed/ECB/BoE/BoJ implied policy paths, global 2Y and 10Y panels
Equities · index pages, relatives, vol suite, global relatives, Mag7+ quant sheet, options surfaces
FX · majors dashboards, correlations, COT positioning, crosses
Commodities · energy, metals, agriculture, COT crowding, term structure
Crypto · BTC ladders, ETH, macro correlations, ETF flow proxy

Where We Stand
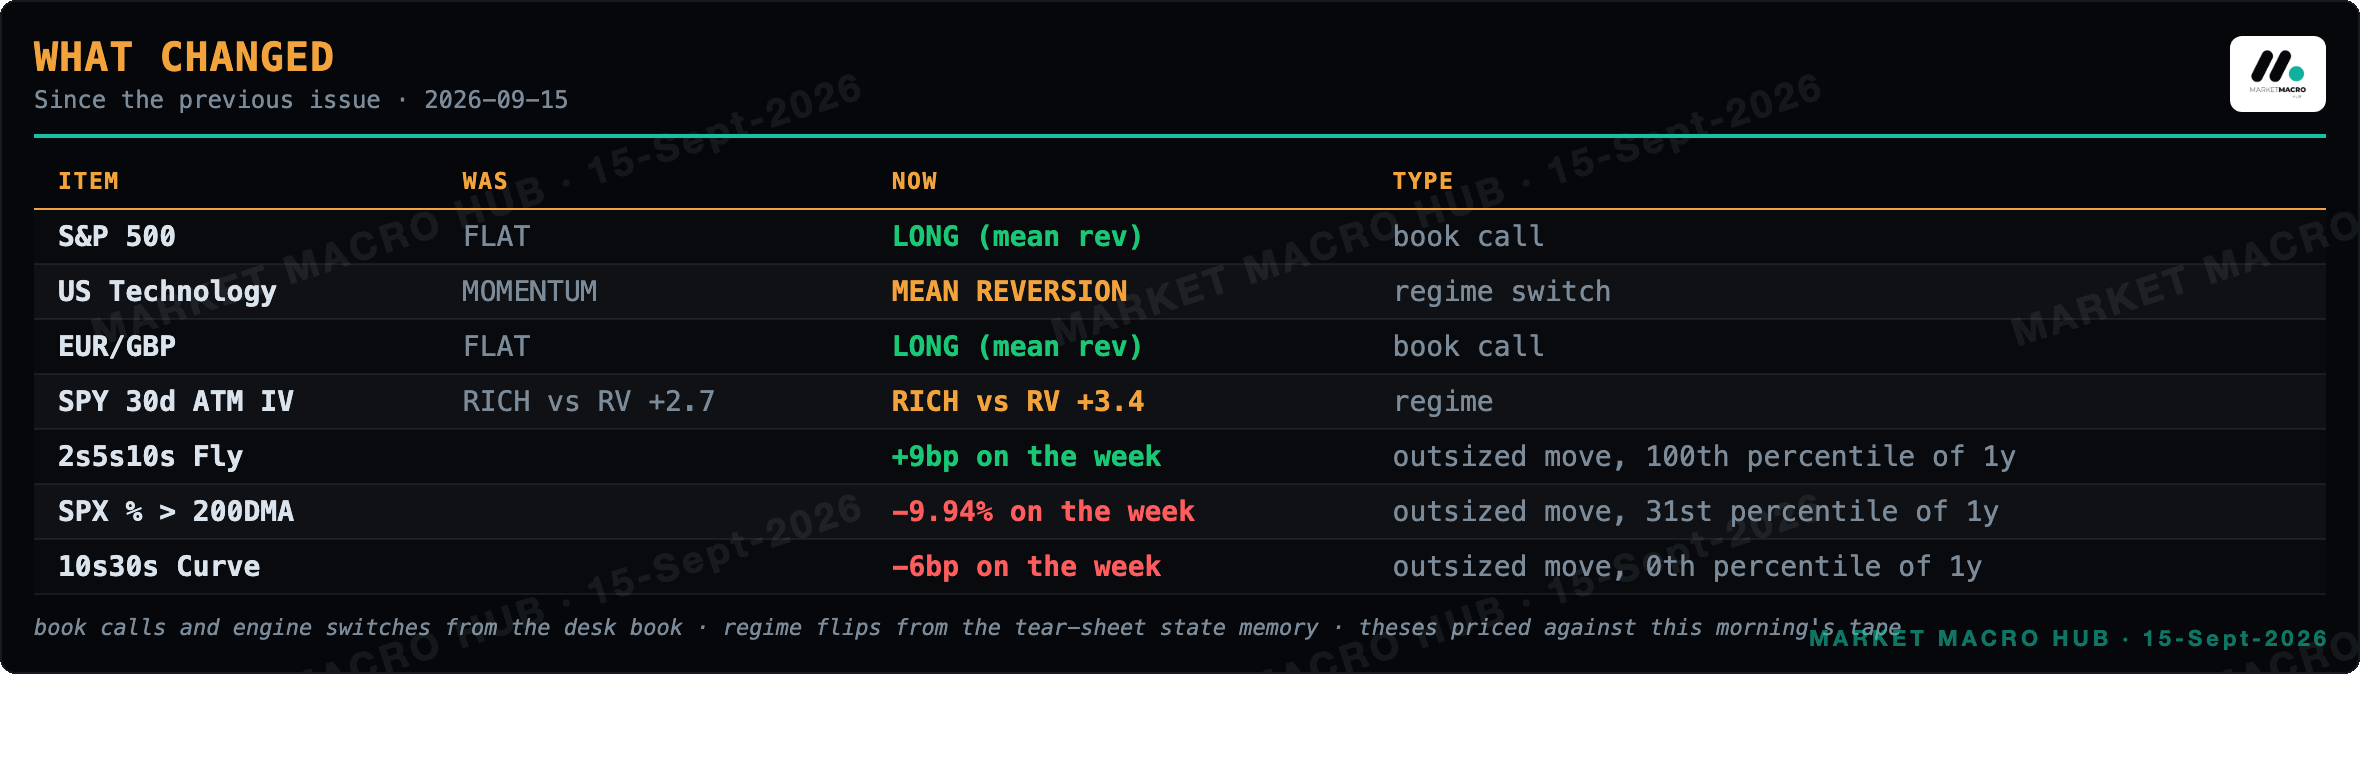
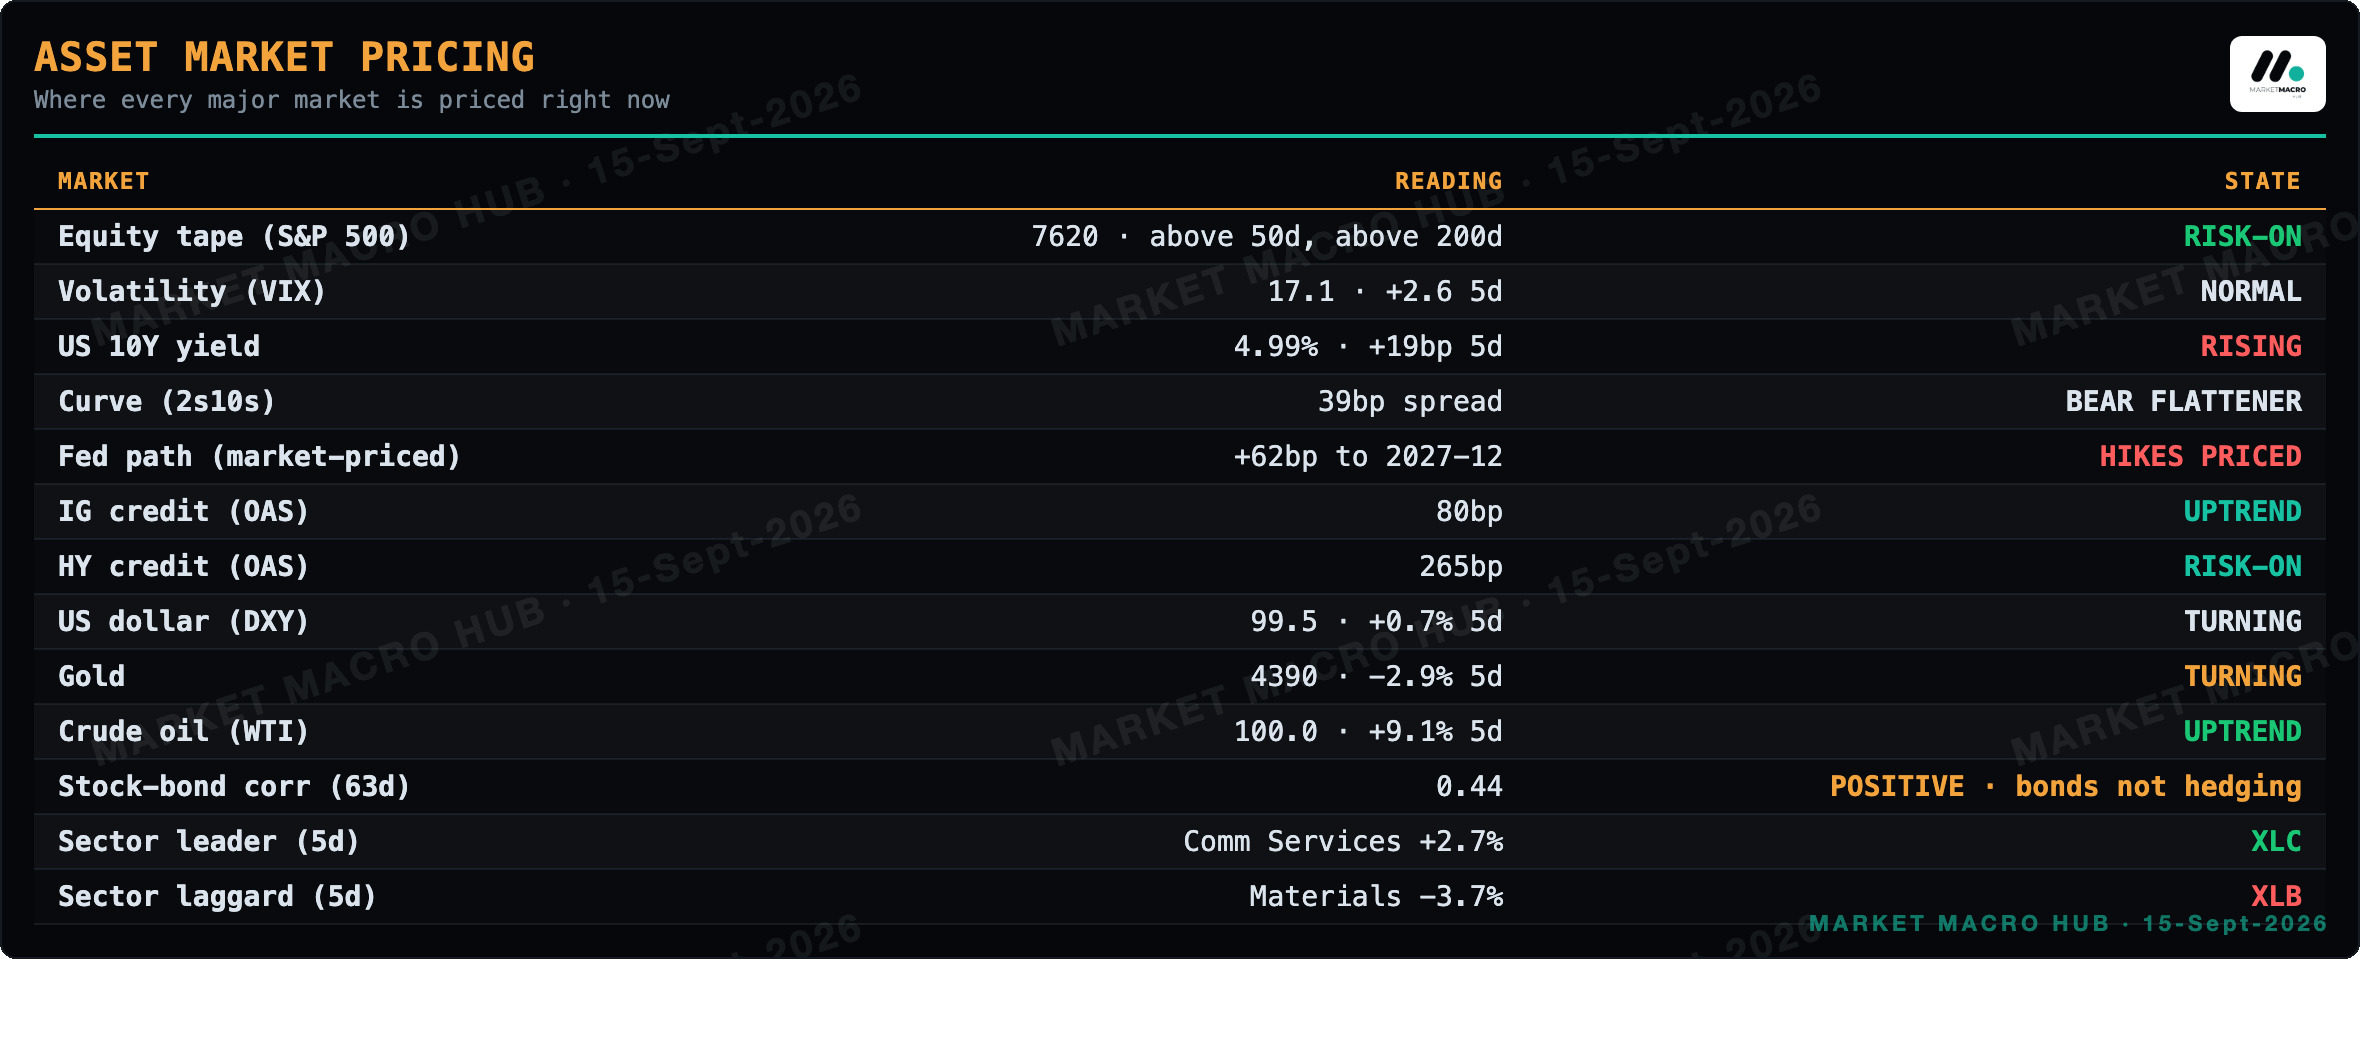
Yesterday I said core CPI at 0.3% held my pre-FOMC stance into Wednesday, and this morning's tape backs it. DXY marginally extended on recent gains amid higher oil prices and with the US 10yr yield breaching 5% for the first time since 2023, while participants await key central bank rate decisions beginning with the FOMC on Wednesday, with money markets pricing an 84% chance of the Fed hiking rates. The 2Y leads the front-end again at +13bp and I still do not chase it. My oldest open thesis, WTI over equities on supply risk, opened 8 September, stays intact with crude bid hard on the tape even as it printed a soft day yesterday. The IG carry call at 80bp holds with invalidation pinned at 90, and I'm not moving it.
What Changed
Asset Market Pricing
Sector Attribution
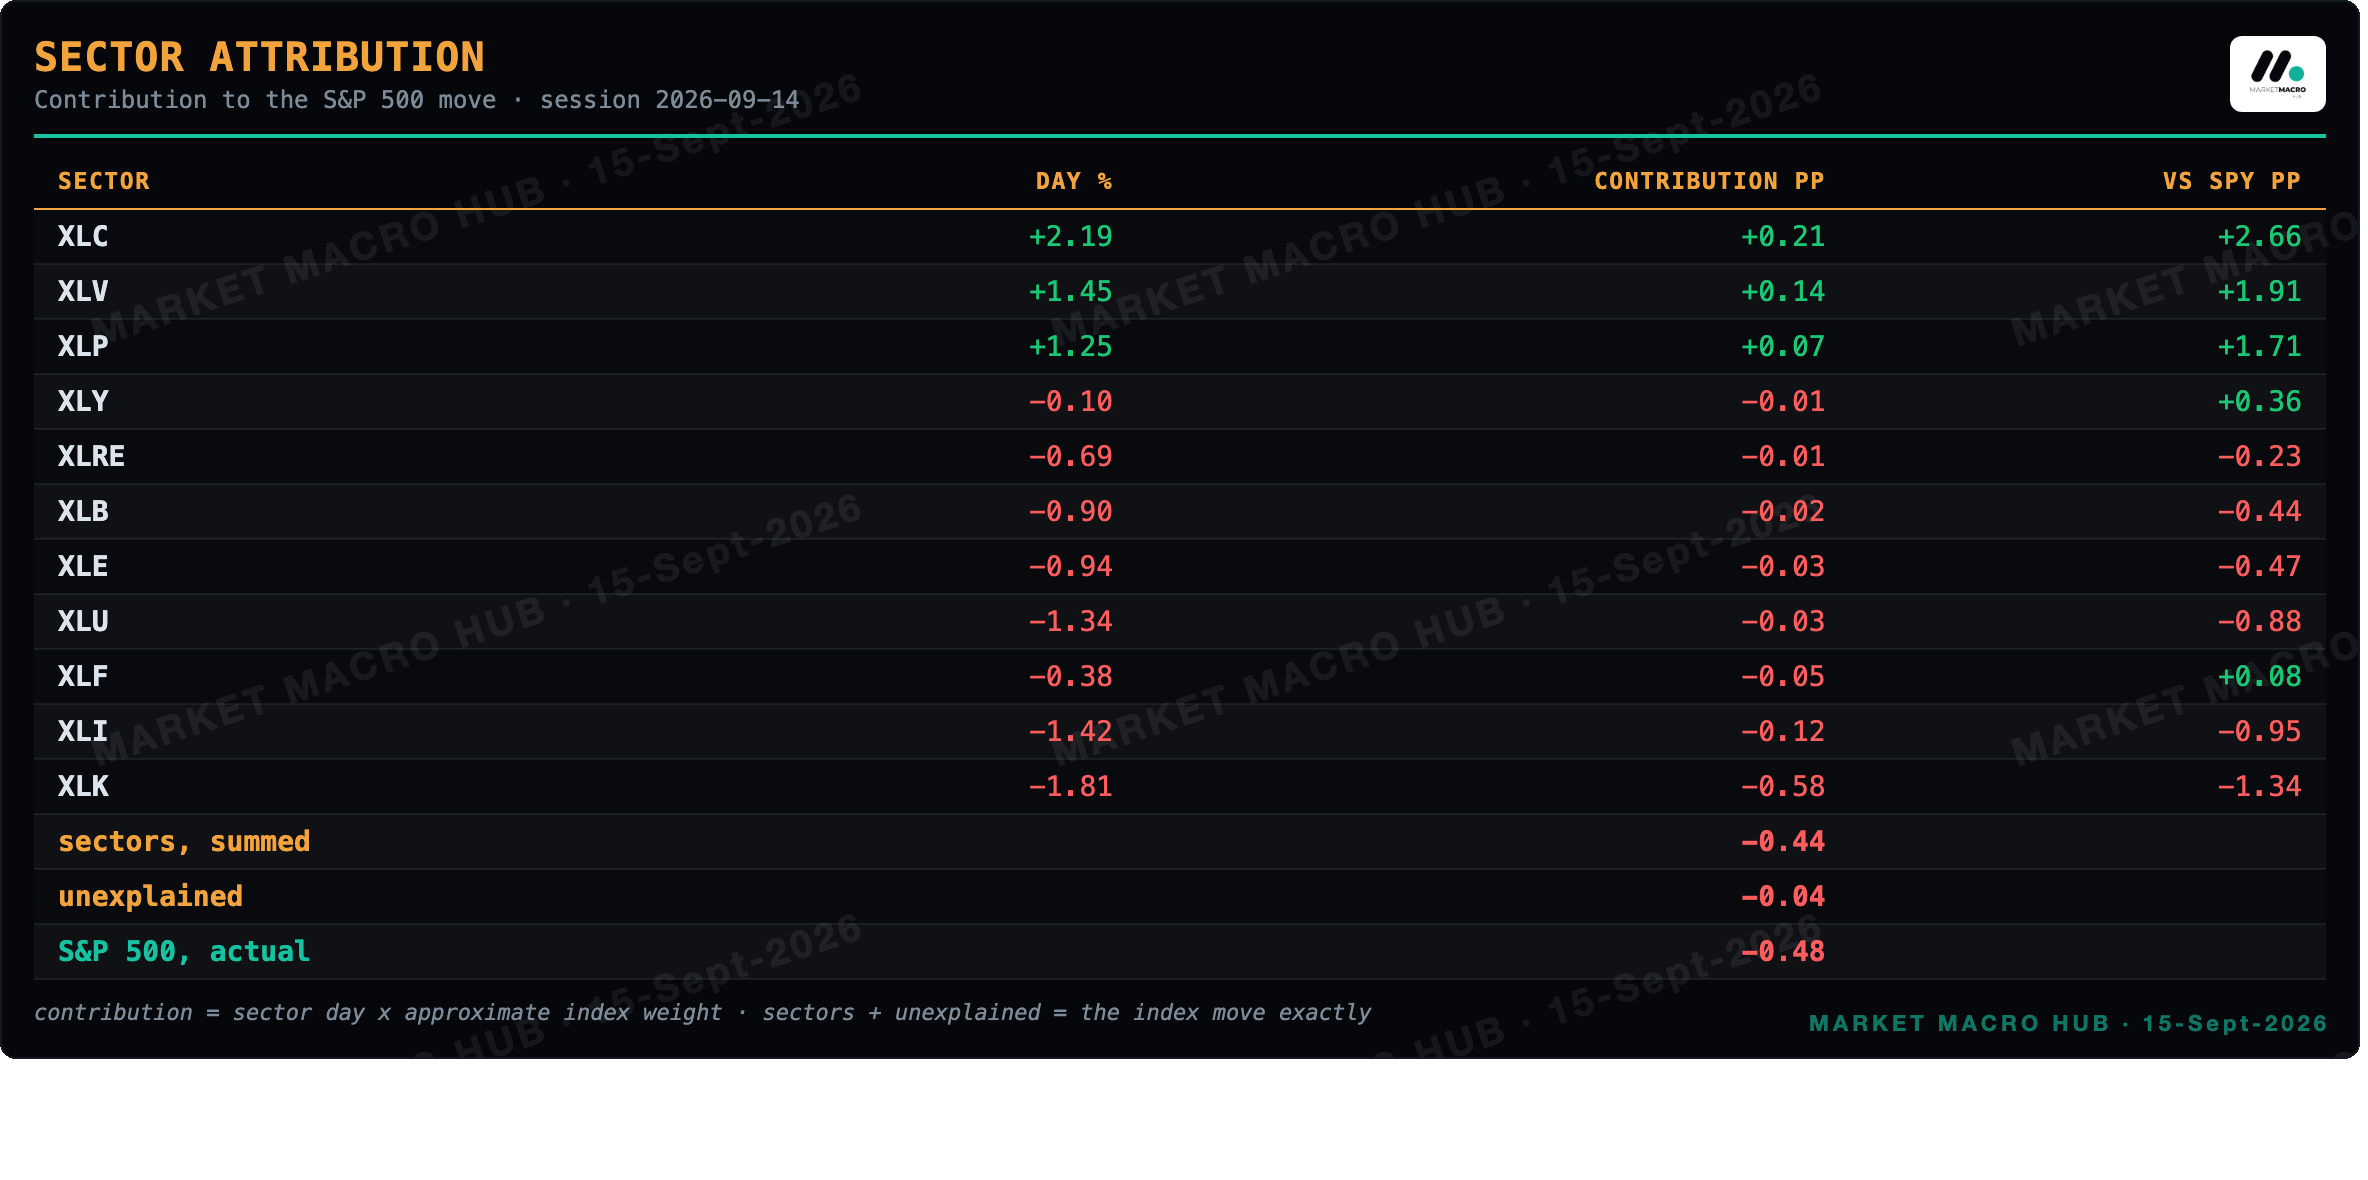
Session 2026-09-14. Sectors plus the unexplained remainder sum to the index move, and the sector split accounts for 91% of it.
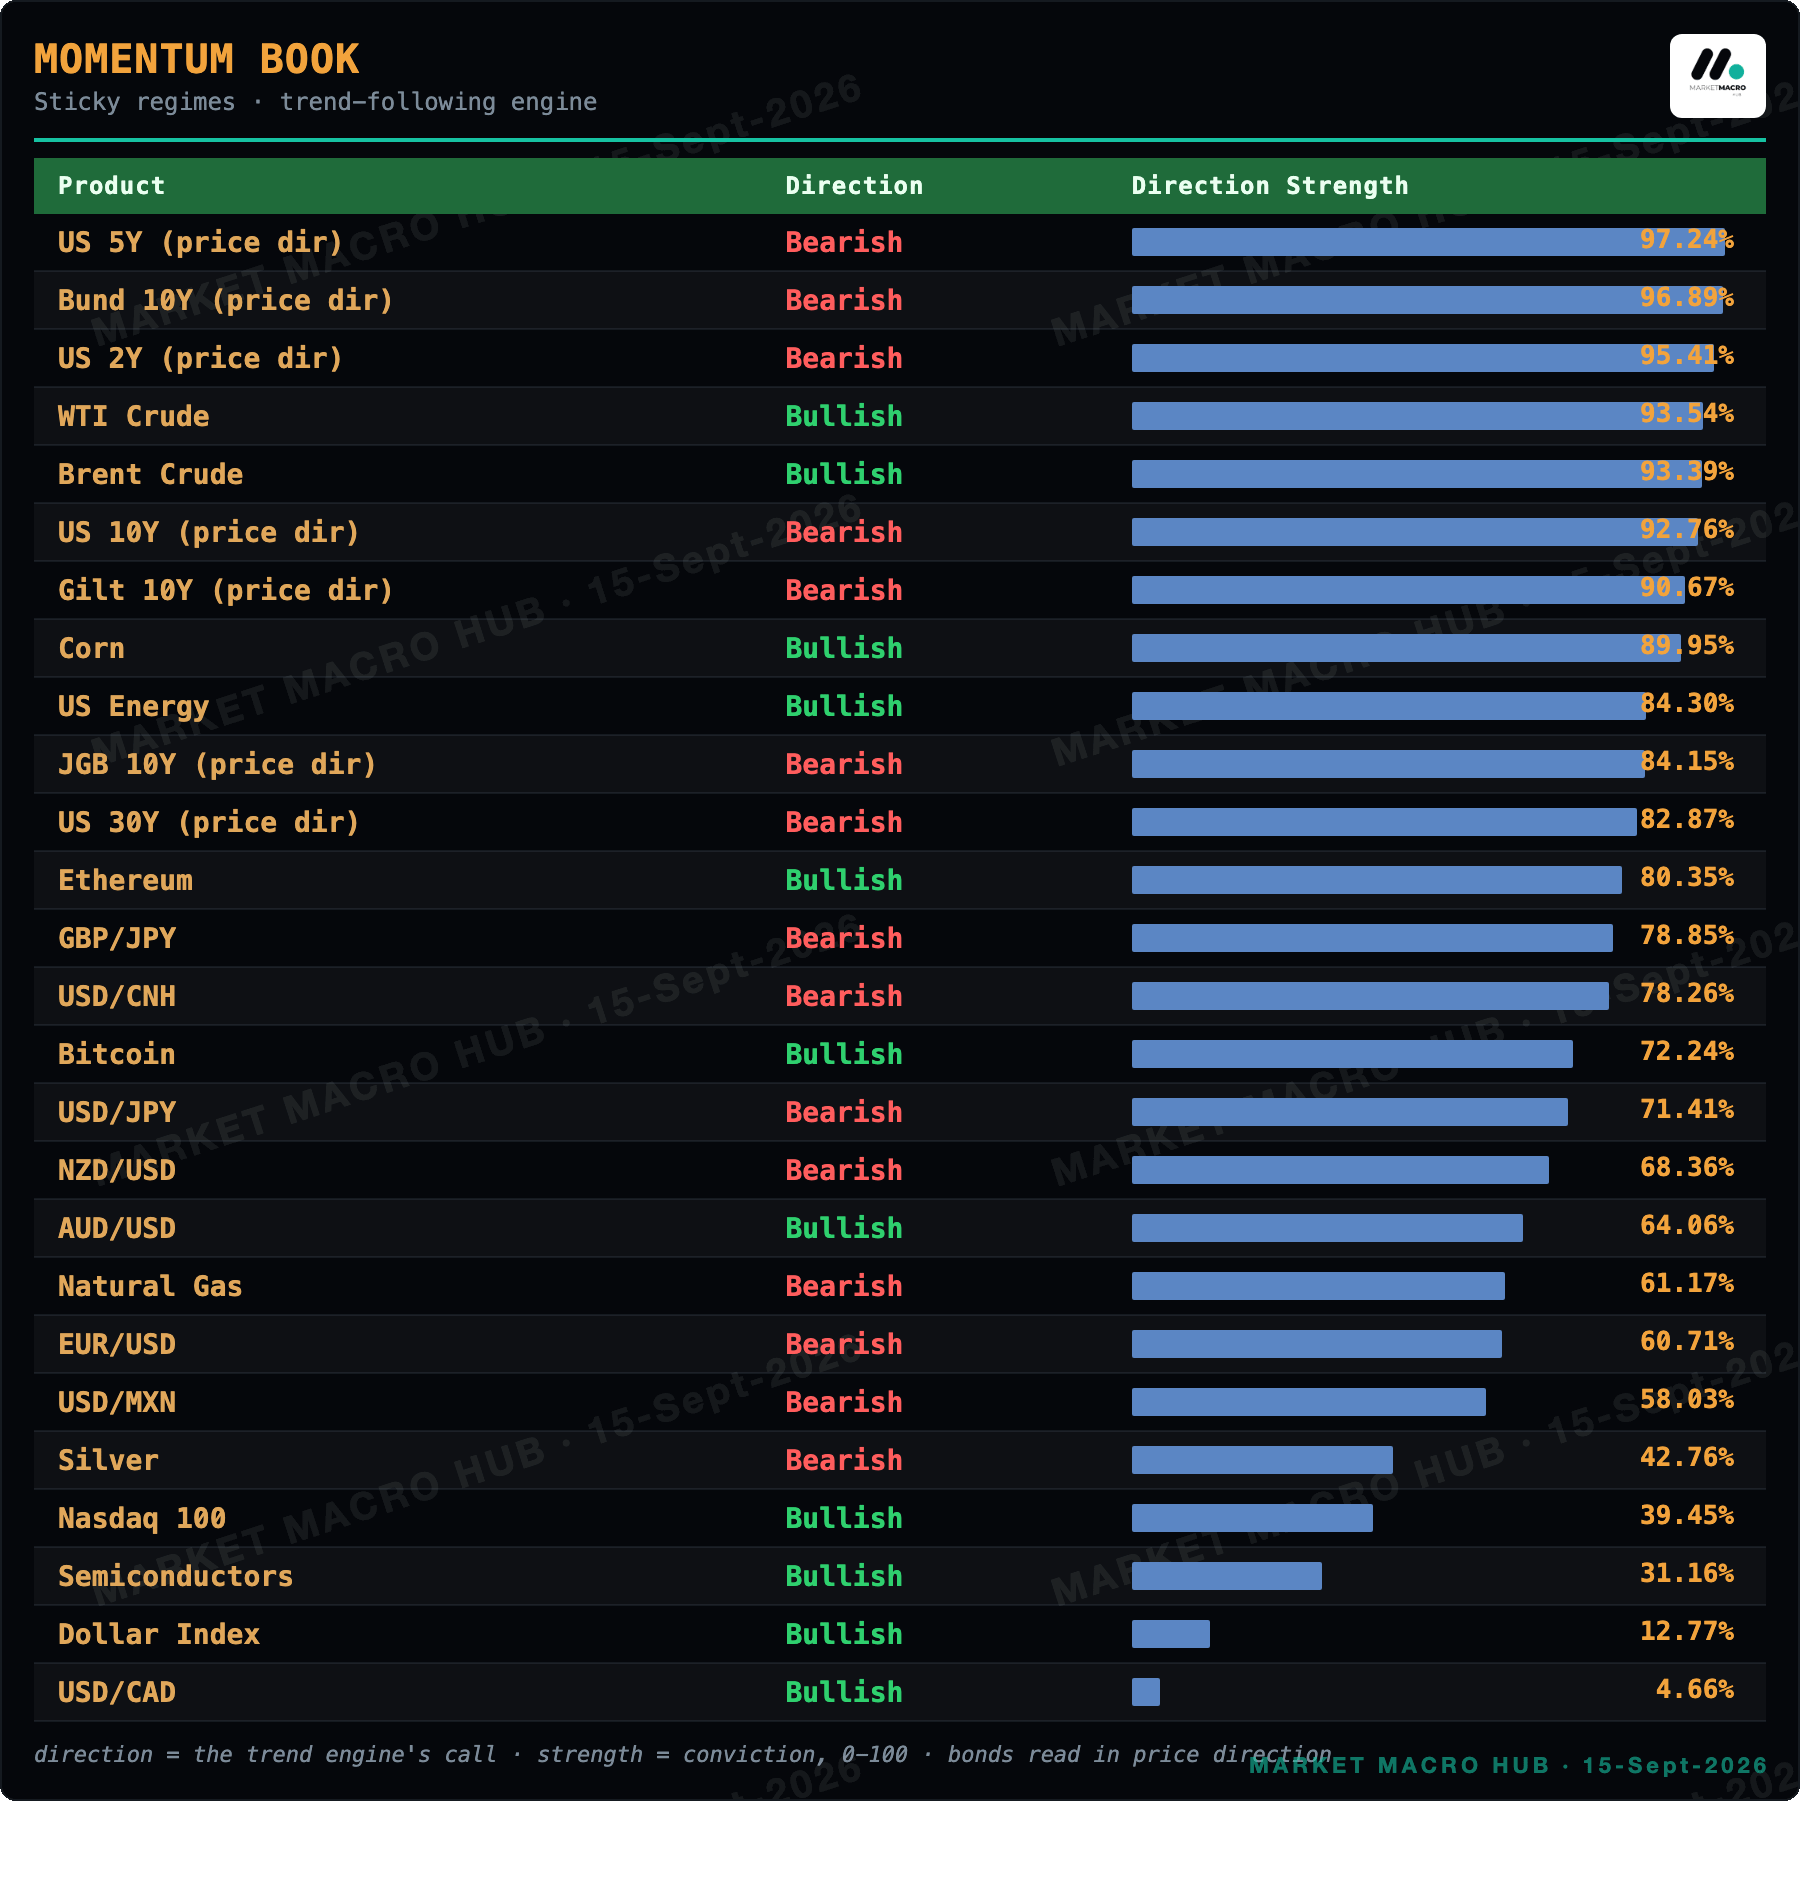
Momentum Book · Sticky Regimes
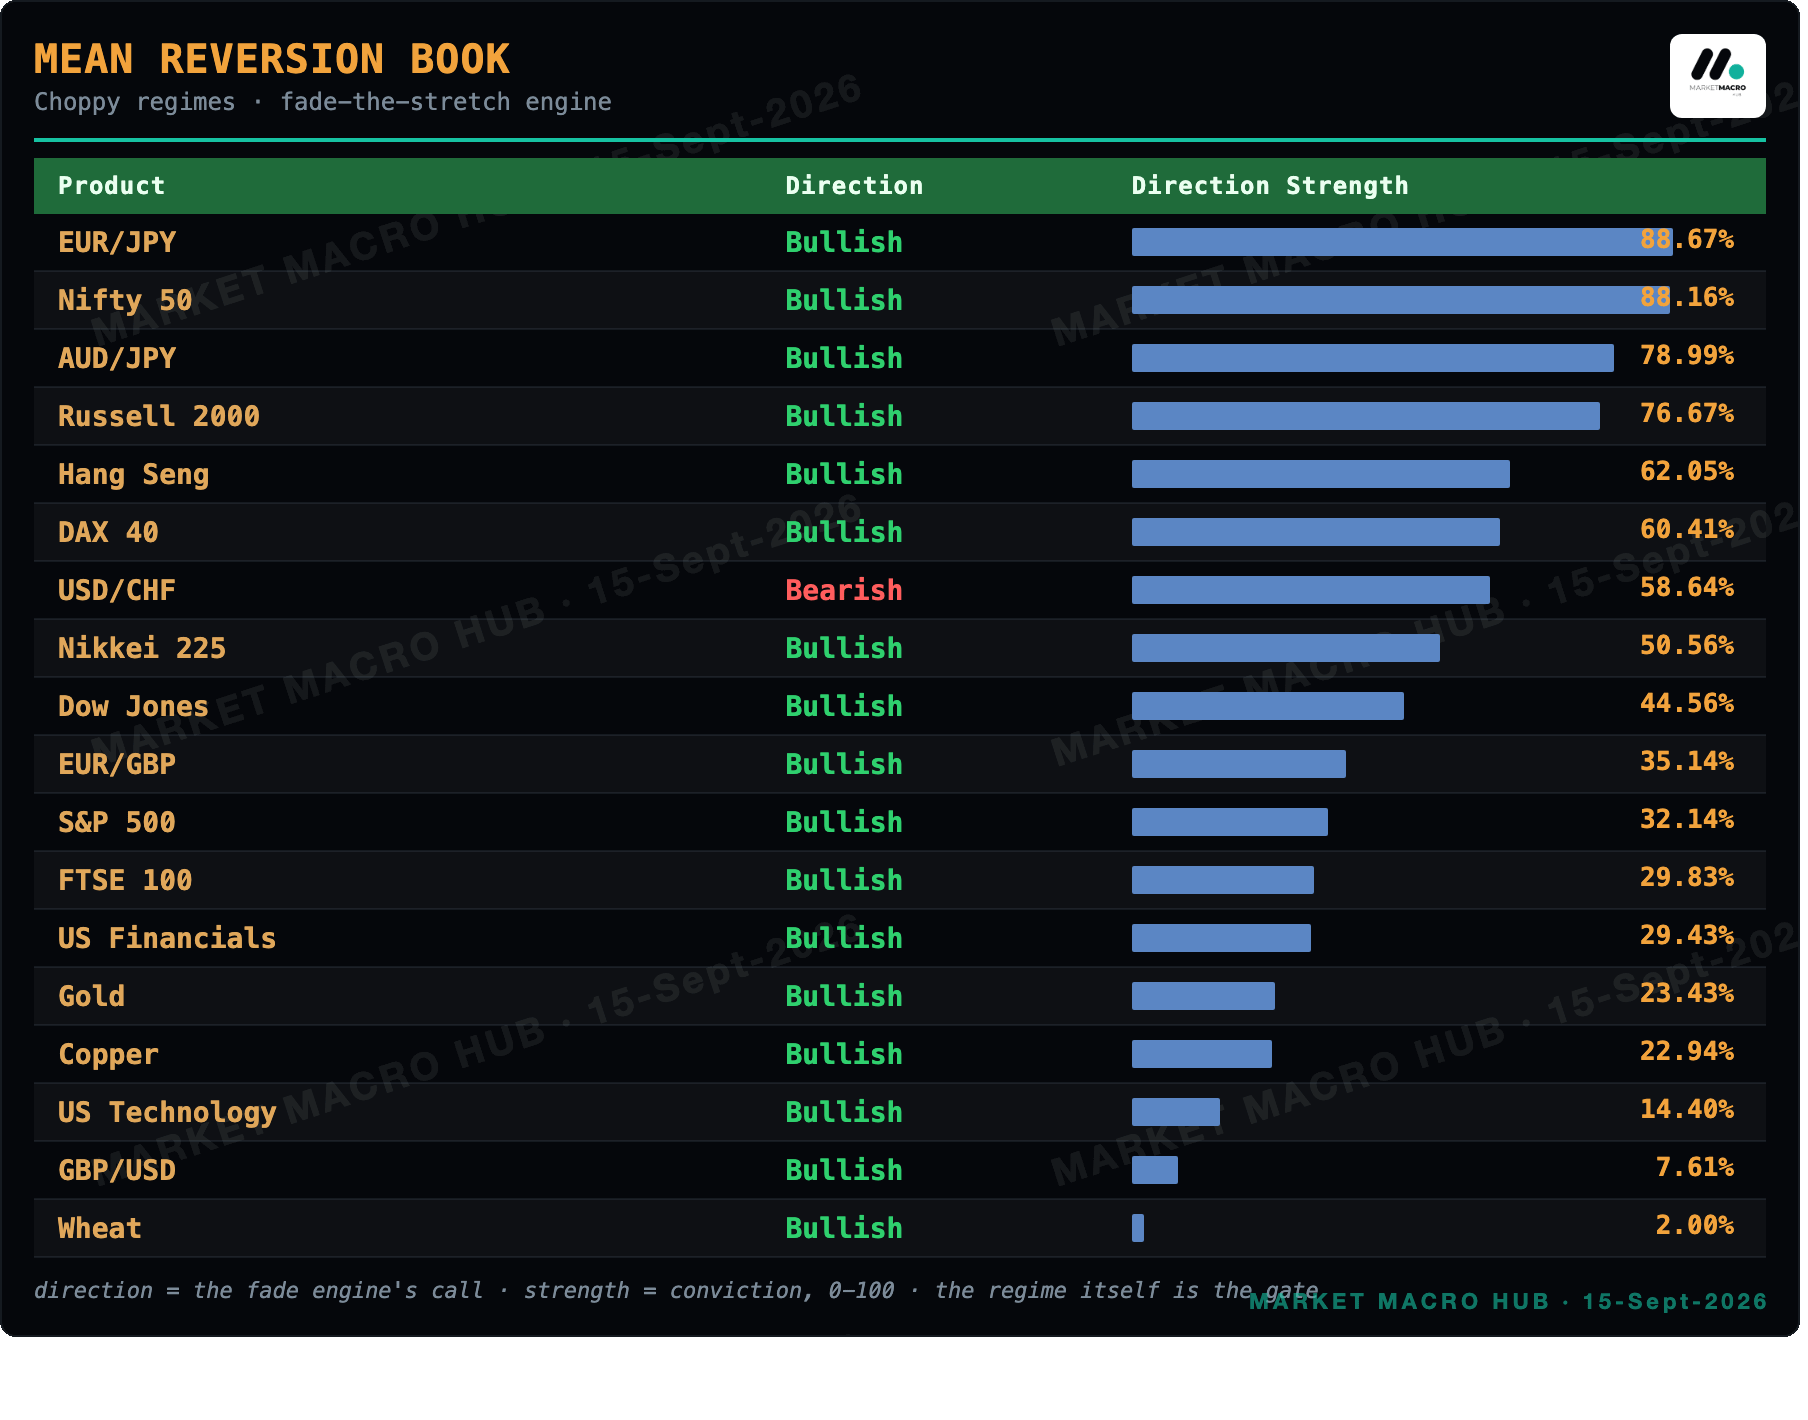
Mean Reversion Book · Choppy Regimes
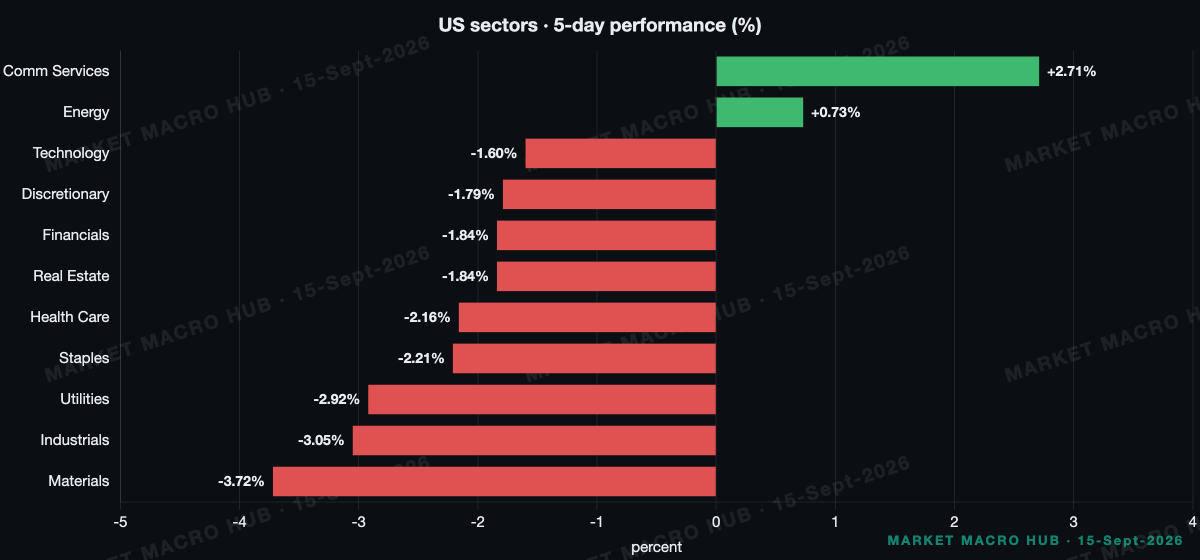
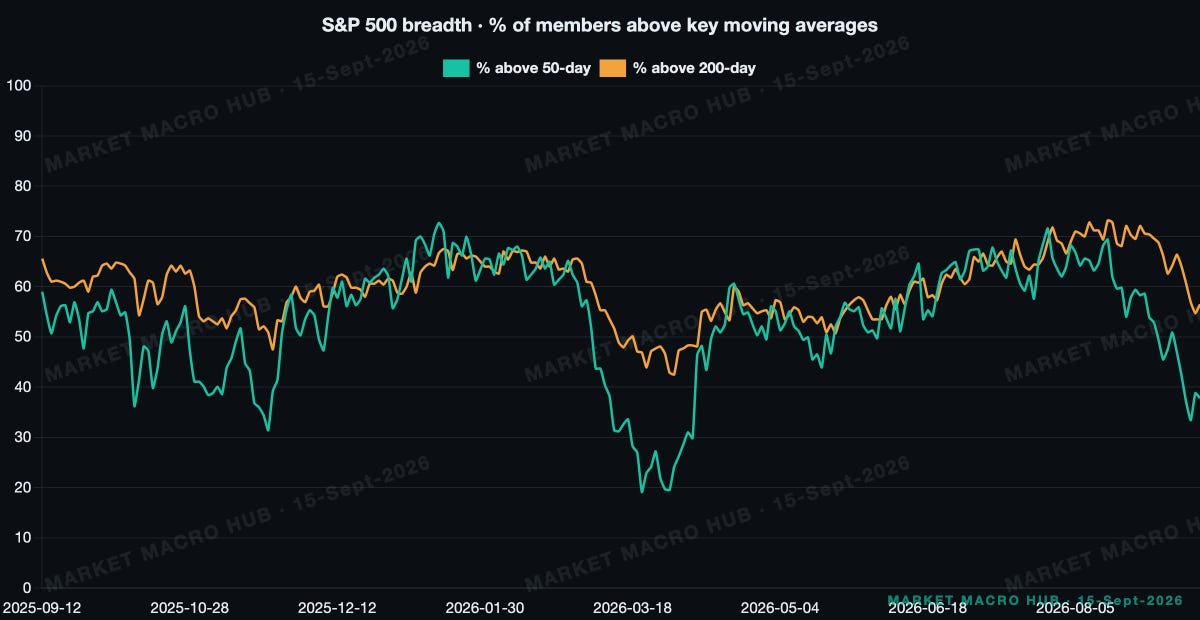
Sector Snapshot & Breadth
Event Watch · FOMC decision tomorrow
reference     events  avg move  median  closed higher  avg abs move
-------------------------------------------------------------------
S&P 500           37    +0.02%  -0.03%            41%         1.01%
US 10Y yield      37    -2.1bp  -2.2bp            41%         7.0bp
Dollar (DXY)      37    -0.10%  -0.12%            43%         0.49%
Gold              37    +0.10%  +0.25%            57%         0.99%
Into the print the book is long equity beta, short duration, long gold .
Main Developments in Macro
US 10Y YIELD BREACHES 5% FIRST TIME SINCE 2023 AHEAD OF WEDNESDAY FOMC
MONEY MARKETS PRICE 84% CHANCE OF FED HIKE THIS WEEK
IRGC SAYS STRAIT OF HORMUZ CLOSED, CENTCOM DENIES TANKER MINE STRIKE
CRUDE BID: WTI +1.9%, BRENT +1.7% ON MIDDLE EAST SUPPLY RISK
US CHIPS AND MEMORY SOLD AFTER AI CEOS CALL FOR DEVELOPMENT SLOWDOWN
TRUMP PUSHES BACK, CALLS AI TAKEOVER FEARS A HOAX
CHINA DATA MIXED: IP TOPS, RETAIL SALES DISAPPOINT, HOUSE PRICES CONTRACT
The recent prints tell a growth-cooling, inflation-sticky story. Core Inflation Rate MoM came in at 0.3% versus consensus 0.2%, while headline Inflation Rate MoM landed in line at 0.4%. Against that, Michigan sentiment collapsed to 47.8 from 51.7. Sticky core with a wobbling consumer is exactly the mix the Fed hikes into and equities pretend not to see.
Cross-Asset Read
Leadership yesterday was defensive. XLC added +0.21pp and XLV +0.14pp, while XLK dragged -0.58pp as the AI-safety headlines hit chips. That is defensive money hiding, and it looks nothing like a risk-on rotation.
The correlation that matters keeps deepening. Crude futures remained firmer amid the ongoing conflict in the Middle East as Yemeni Houthis continued to target areas in Saudi Arabia, while Iran reiterated an unwillingness to negotiate, and Trump commented that oil is flowing through the Hormuz Strait. SPX versus crude sits at -0.65 now against -0.57 a month ago, which keeps my oil-over-equities thesis clean.
Credit refuses to corroborate any anxiety. IG OAS at 80bp sits at the tight end of range against a 90bp mean, and HY at 265bp is priced as if default risk vanished.
Rates & Fed Pricing
No cut is anywhere on the strip, so forget easing. September is a near-lock hike at roughly 92% odds, and the strip runs to a 4.55% peak in September 2027, +92bp cumulative over EFFR. Terminal repriced +14.5bp on the week but was flat on the day. The 10Y broke 5% because supply, oil and a hawkish FOMC all lean the same way. What changes my mind is the front-end: if the 2Y stalls here with equities holding, the strip is telling me three-plus more of tightening won't get realised.
Bottom Line
Sticky core plus a 92% hike keeps me leaning short duration into Wednesday.
Crude over equities stays my cleanest expression on a -0.65 correlation.
IG carry holds at 80bp, invalidation still 90.
Copper crowding flag is live at the 100th percentile, so I stay clear of longs.
Watching whether equities blink now that the 10Y prints a 5-handle.
The Week Ahead
Monday, ADP weekly and NY Empire (cons 14.75 vs 20.6), a soft Empire tilts my growth read lower.
Tuesday, UK jobs and German ZEW colour the European open, marginal for my book.
Wednesday, FOMC, the whole note pivots here.
Wednesday, Retail Sales Ex Autos (cons 0.6% vs prev -0.3%); a strong print hardens the hawkish tape.
Wednesday, Retail Control Group and headline Retail Sales; the consumer read that either confirms or breaks the Michigan slump.
Tradeable Levels
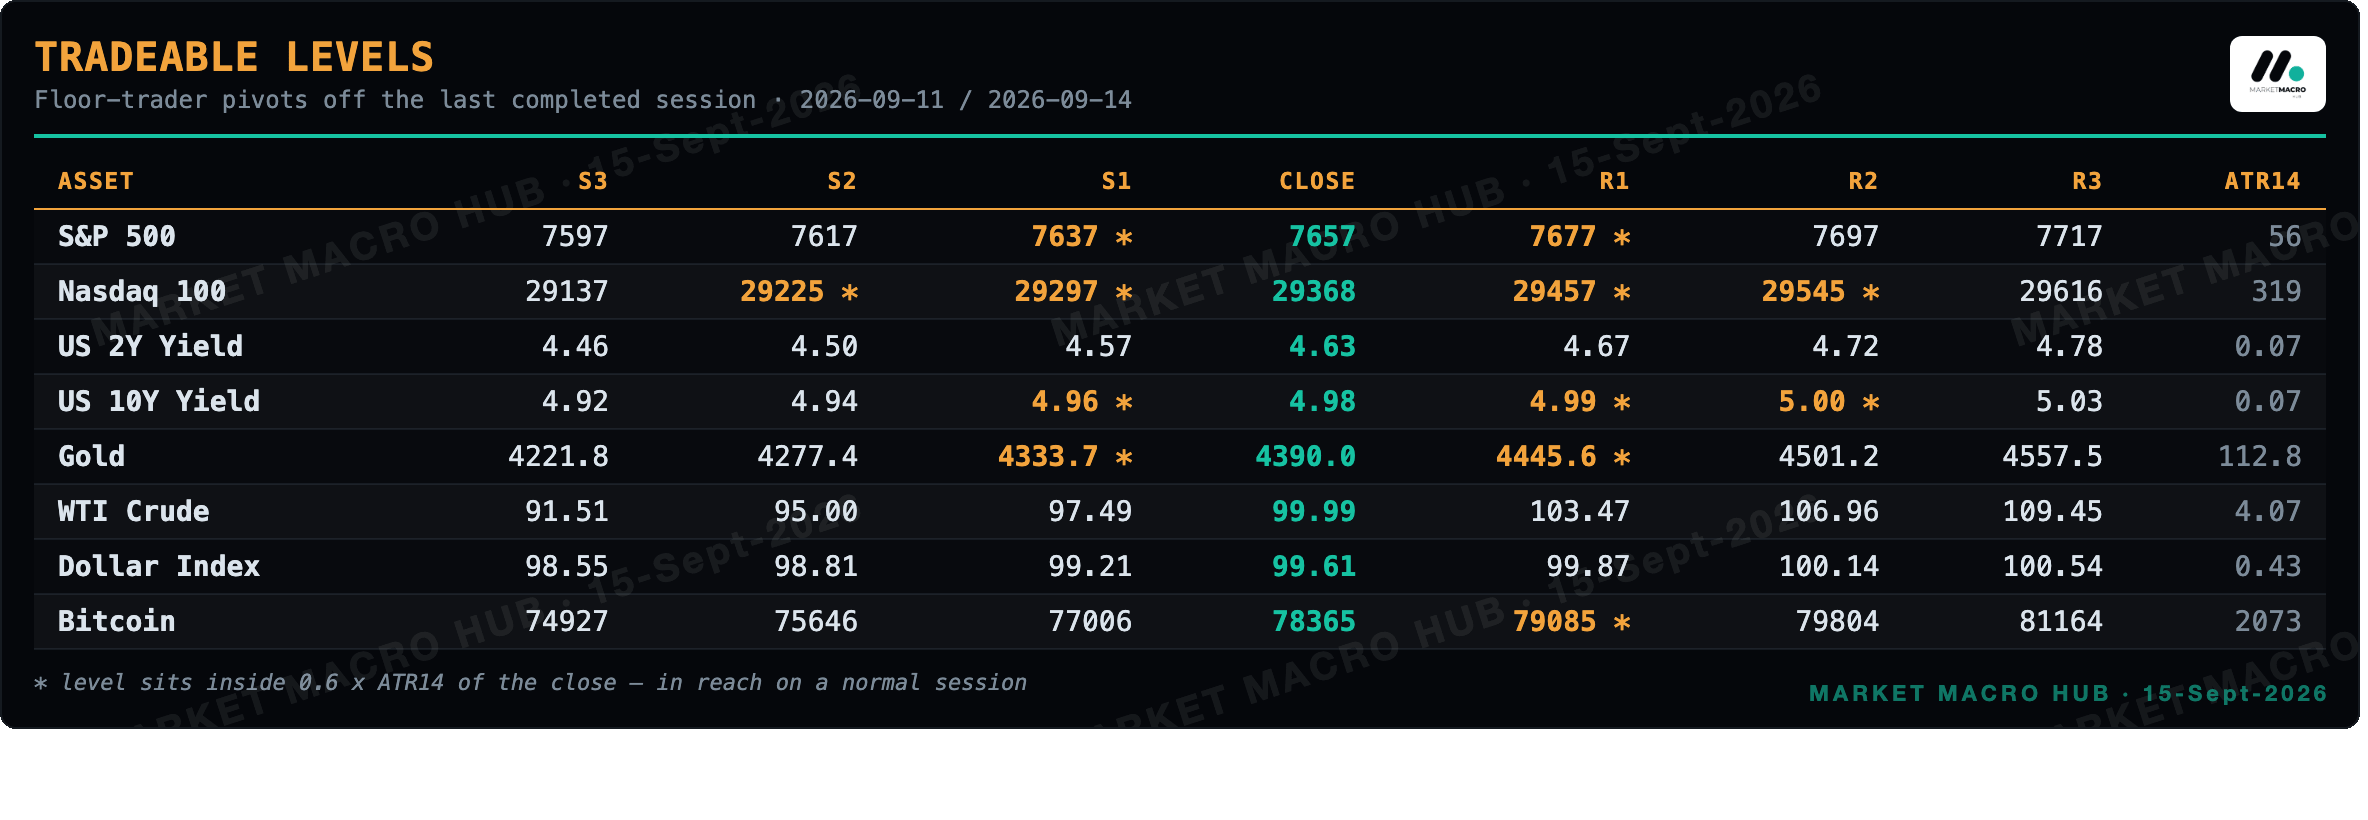
Pivots off the last completed session (2026-09-11 / 2026-09-14). Levels marked * sit within 0.6 x ATR14 of the close.
Vol Screen · Rich and Cheap Implied Vol
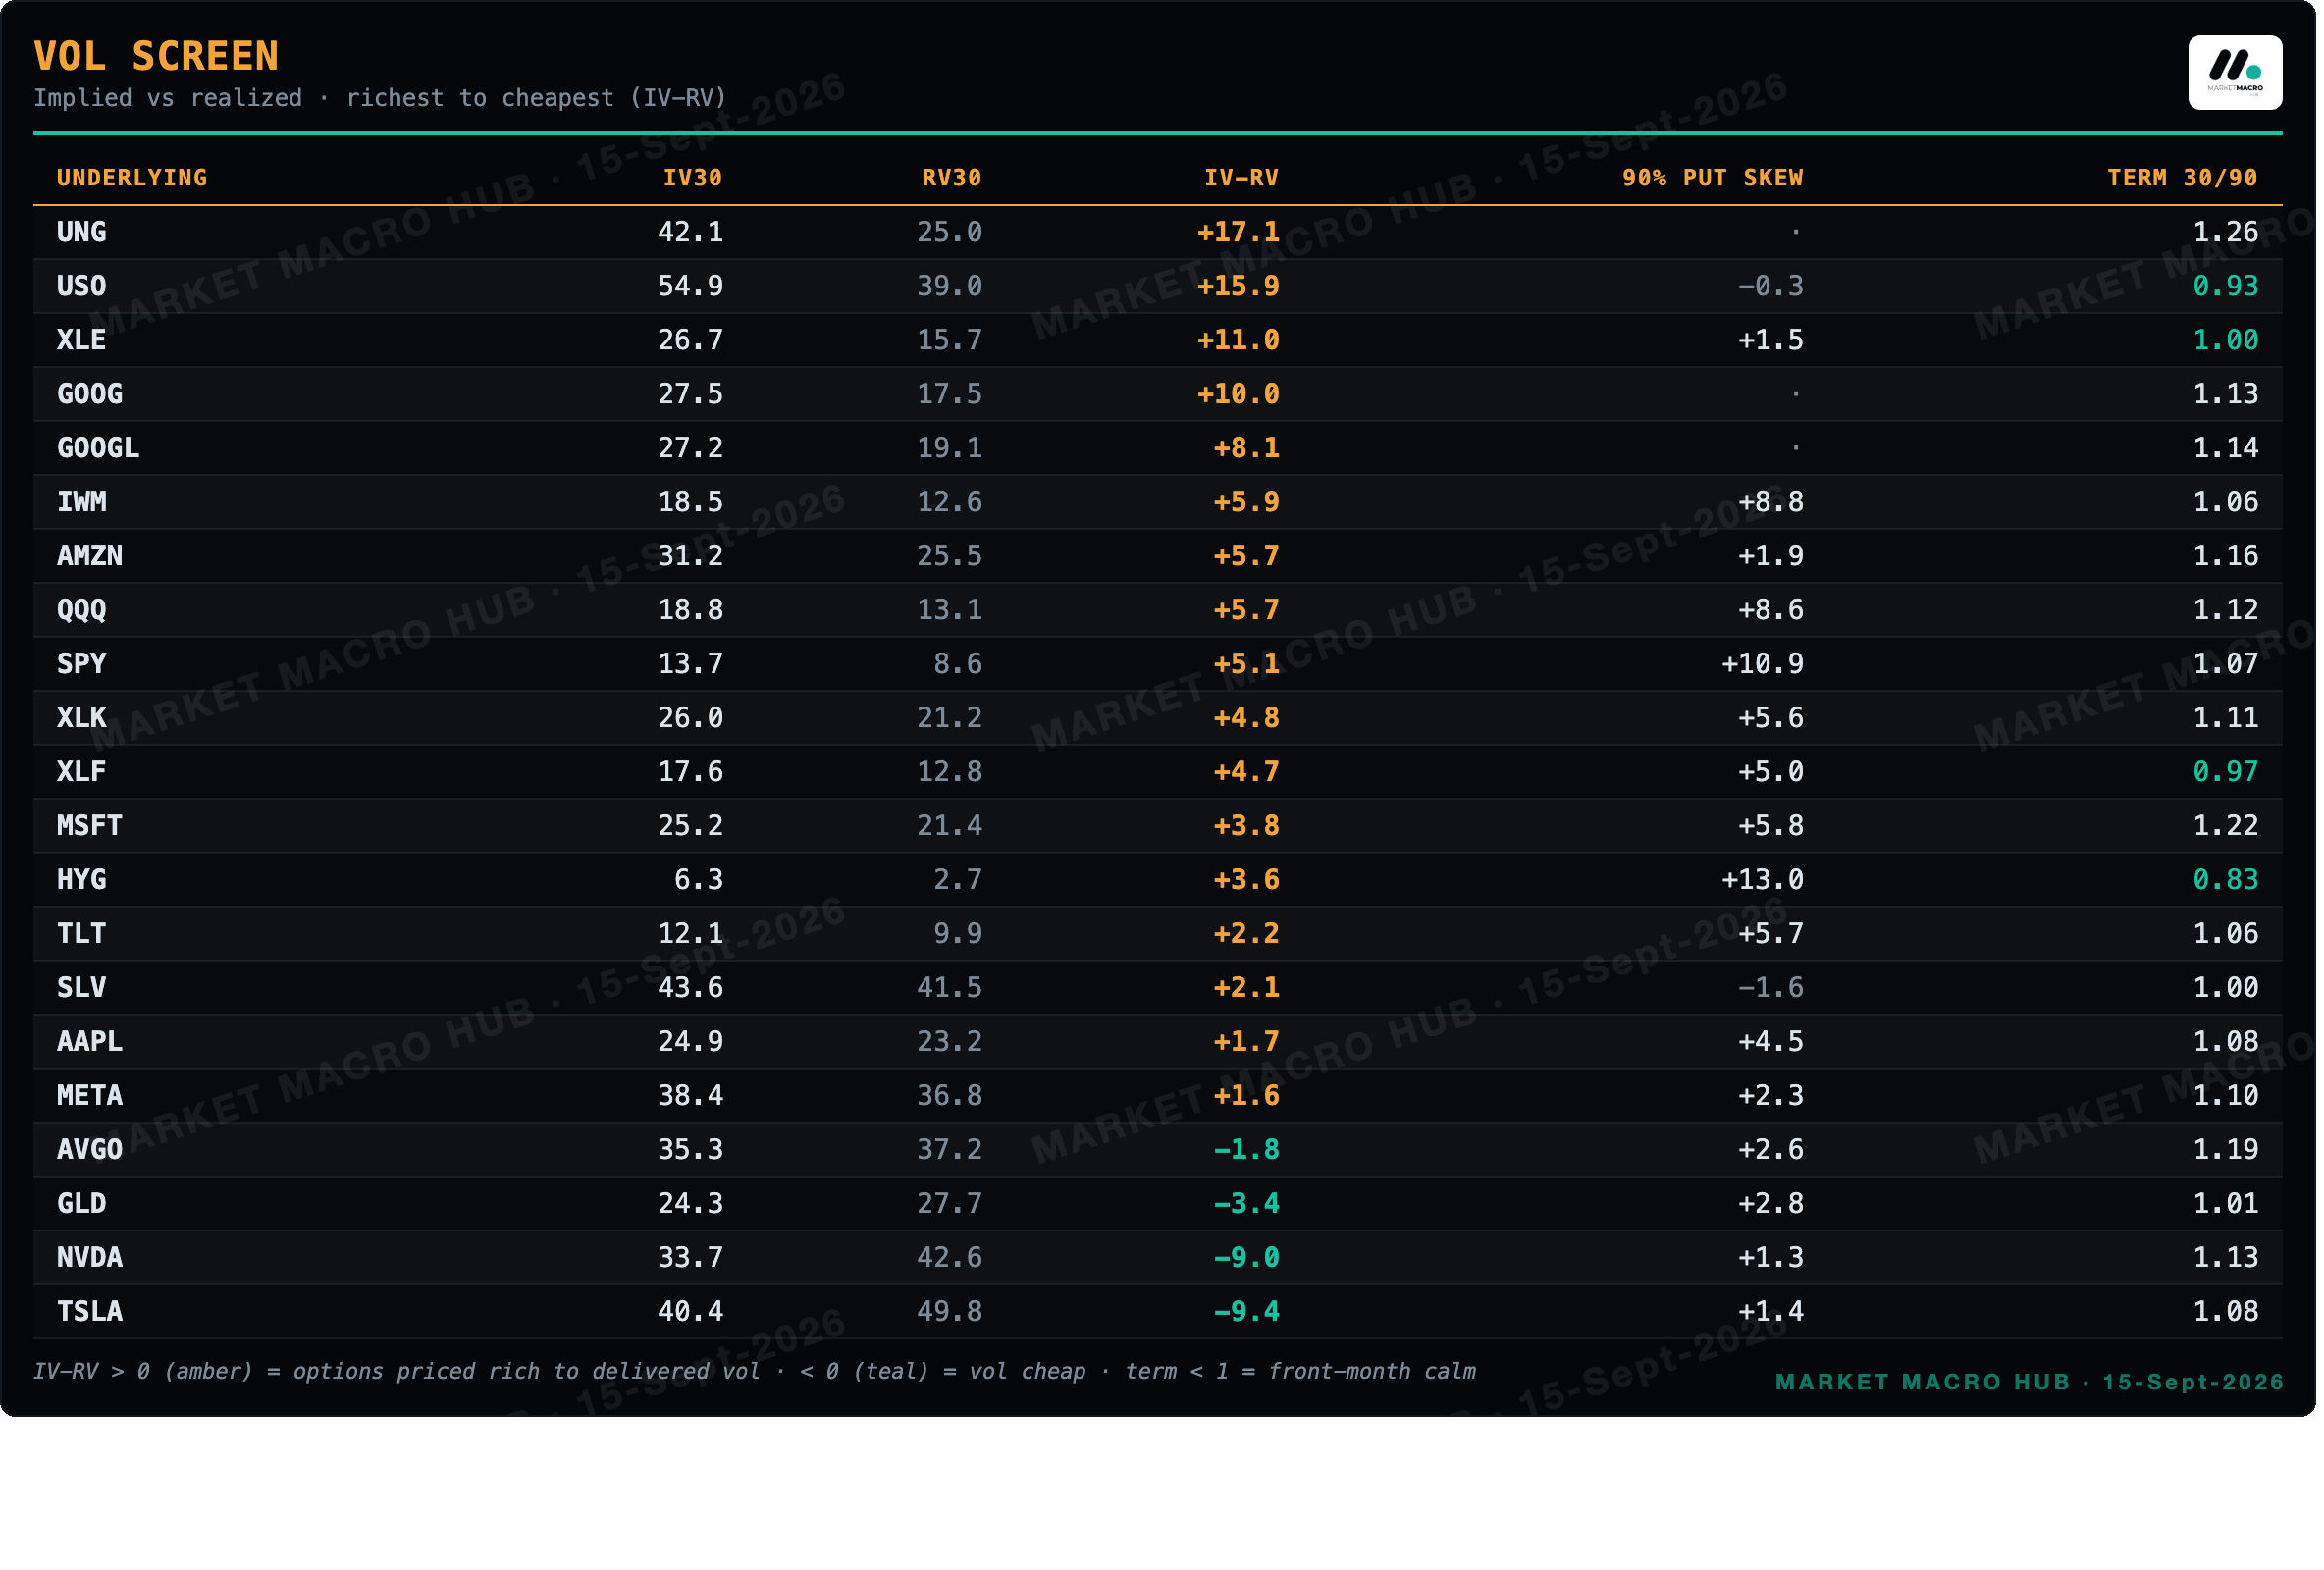
Positive IV-RV = options priced rich to what the tape is delivering (UNG and USO richest today); negative = vol going cheap (TSLA and NVDA).
Disclaimer
The information in this publication is provided for informational and educational purposes only and is believed to be reliable, but its accuracy and completeness are not guaranteed. Nothing herein constitutes investment advice, an offer, or a solicitation to buy or sell any security, derivative, digital asset, or other financial instrument, nor a recommendation suited to any specific reader. All figures are drawn from the day's computed data set at the time of generation and may be delayed, revised, or superseded. Markets involve risk, including the possible loss of principal; past performance and historical relationships do not guarantee future results. Readers should conduct their own research and consult a qualified financial adviser before making any investment decision. The author may hold positions in instruments discussed. This publication is licensed for the personal use of the subscriber only: redistribution, reproduction, or resale in any form is prohibited. © 2026 MARKET MACRO HUB. All rights reserved.