


Today's Tear Sheets
The full daily pack is attached below · six PDFs generated from the same computed data set as this note:
Macro Regime · curve regimes, growth x inflation quadrant, breadth, credit, vol term structure, liquidity, stock-bond correlation, crypto cross-asset, housing
Fixed Income · UST complex, global curves, Fed/ECB/BoE/BoJ implied policy paths, global 2Y and 10Y panels
Equities · index pages, relatives, vol suite, global relatives, Mag7+ quant sheet, options surfaces
FX · majors dashboards, correlations, COT positioning, crosses
Commodities · energy, metals, agriculture, COT crowding, term structure
Crypto · BTC ladders, ETH, macro correlations, ETF flow proxy

TL;DR
Long the hike story, November at around 54% is the first hike half-priced and no cut sits on the strip.
Terminal repriced +42.5bp on the week and I still don't think 79bp gets fully realised, the 2s10s tells me when.
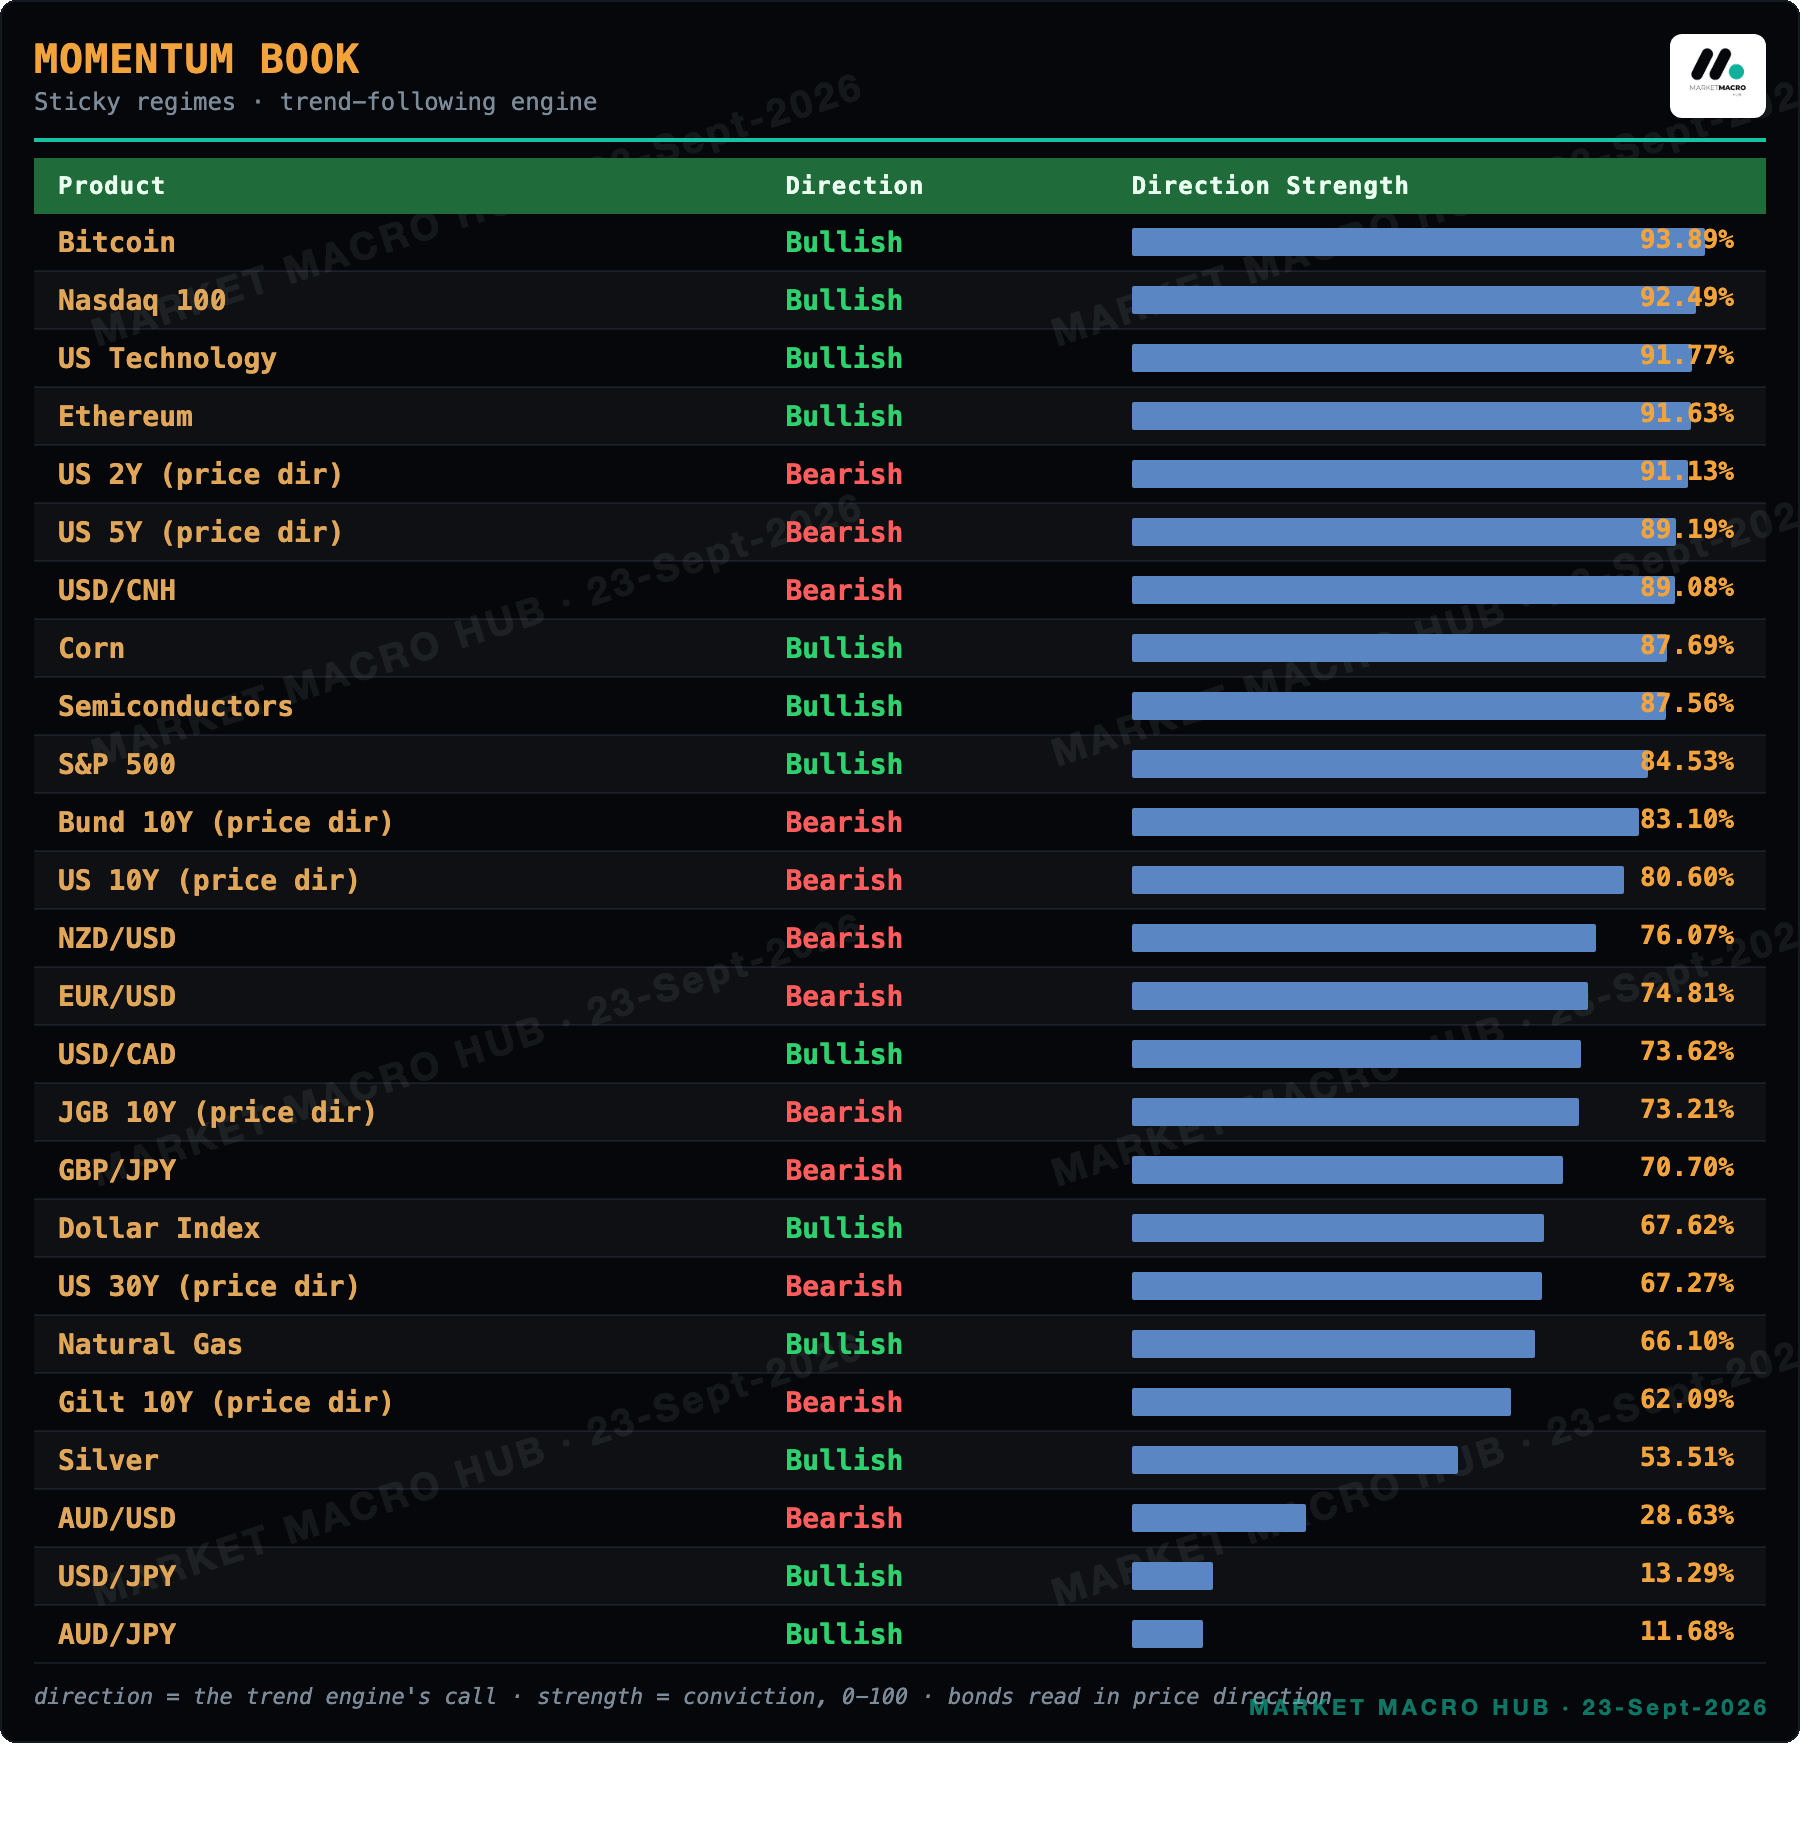
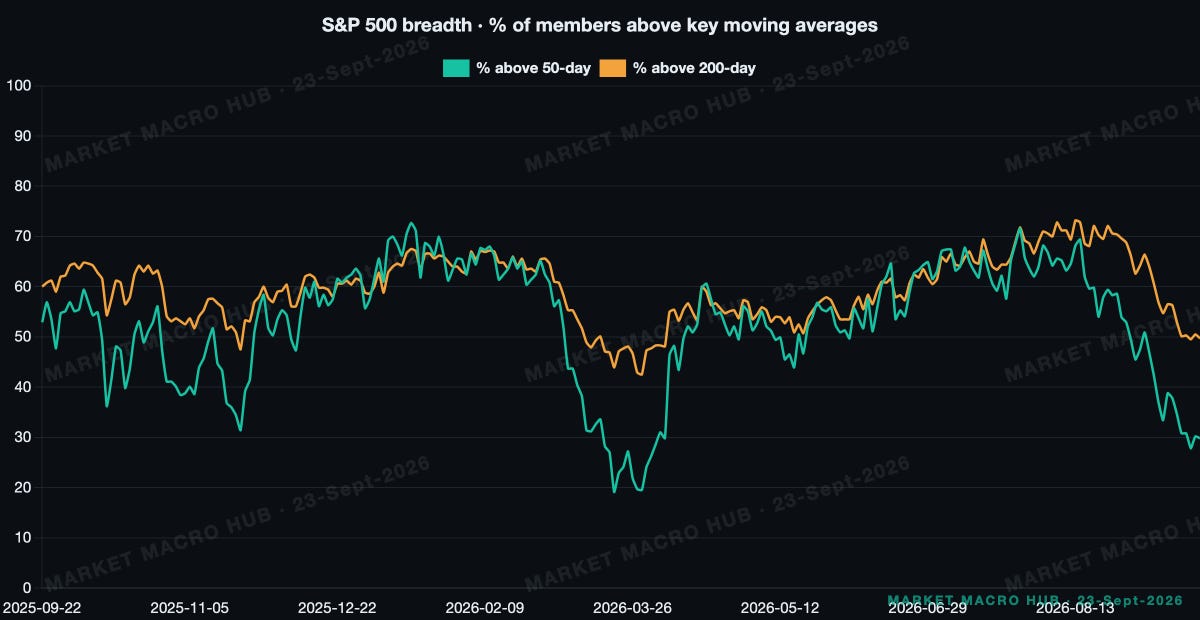
SPX call stays gated at 85 conviction, NDX printed an all-time high but the breadth is narrow.
IG at 77bp flags no stress, invalidation 90bp, credit is not corroborating any equity worry.
Watching the Bitcoin correlation flip to 0.42, it dents my equity hedges.
Where We Stand
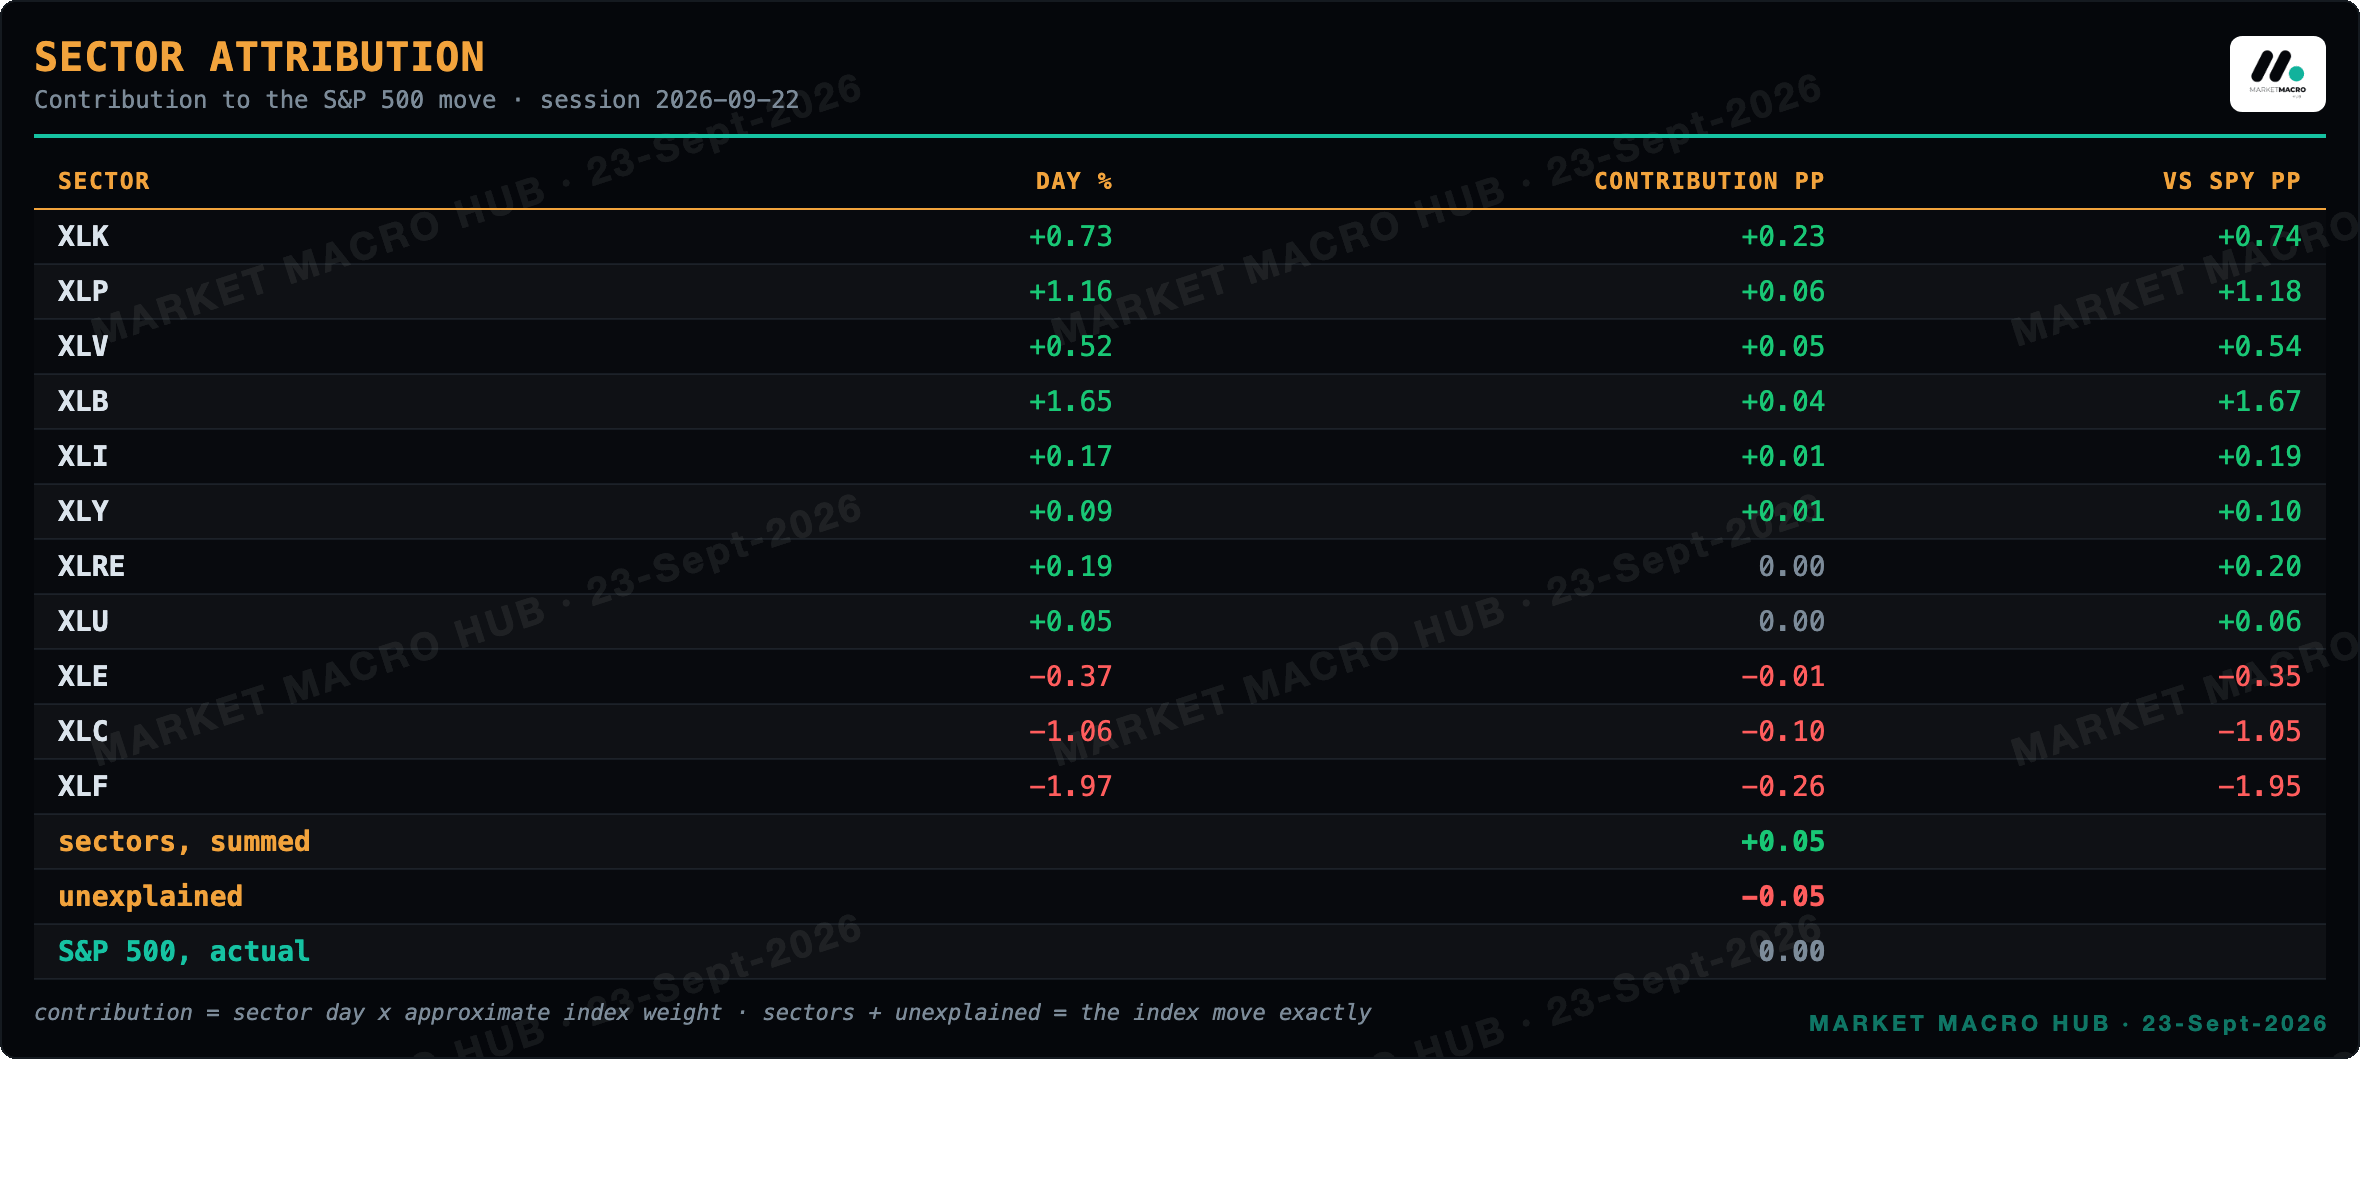
Yesterday I said I was long the hike story, with November the first hike half-priced and no cut anywhere on the strip. This morning's tape confirms it. November is the first month with a hike at least half-priced at around 54% odds, and no month reaches a 25bp cut. But my oldest open thesis from the 20th, that the Fed will not deliver the full SEP path and the terminal reprices lower, is under real pressure. The 2s10s flattened another 5bp today and the terminal pushed higher, so I'm defending it on the read that a 79bp strip is more than I think gets realised while the tape has not started doing my work yet. The copper crowding sits alongside a wheat and corn longs flag that is still live.
What Changed
Asset Market Pricing
Sector Attribution
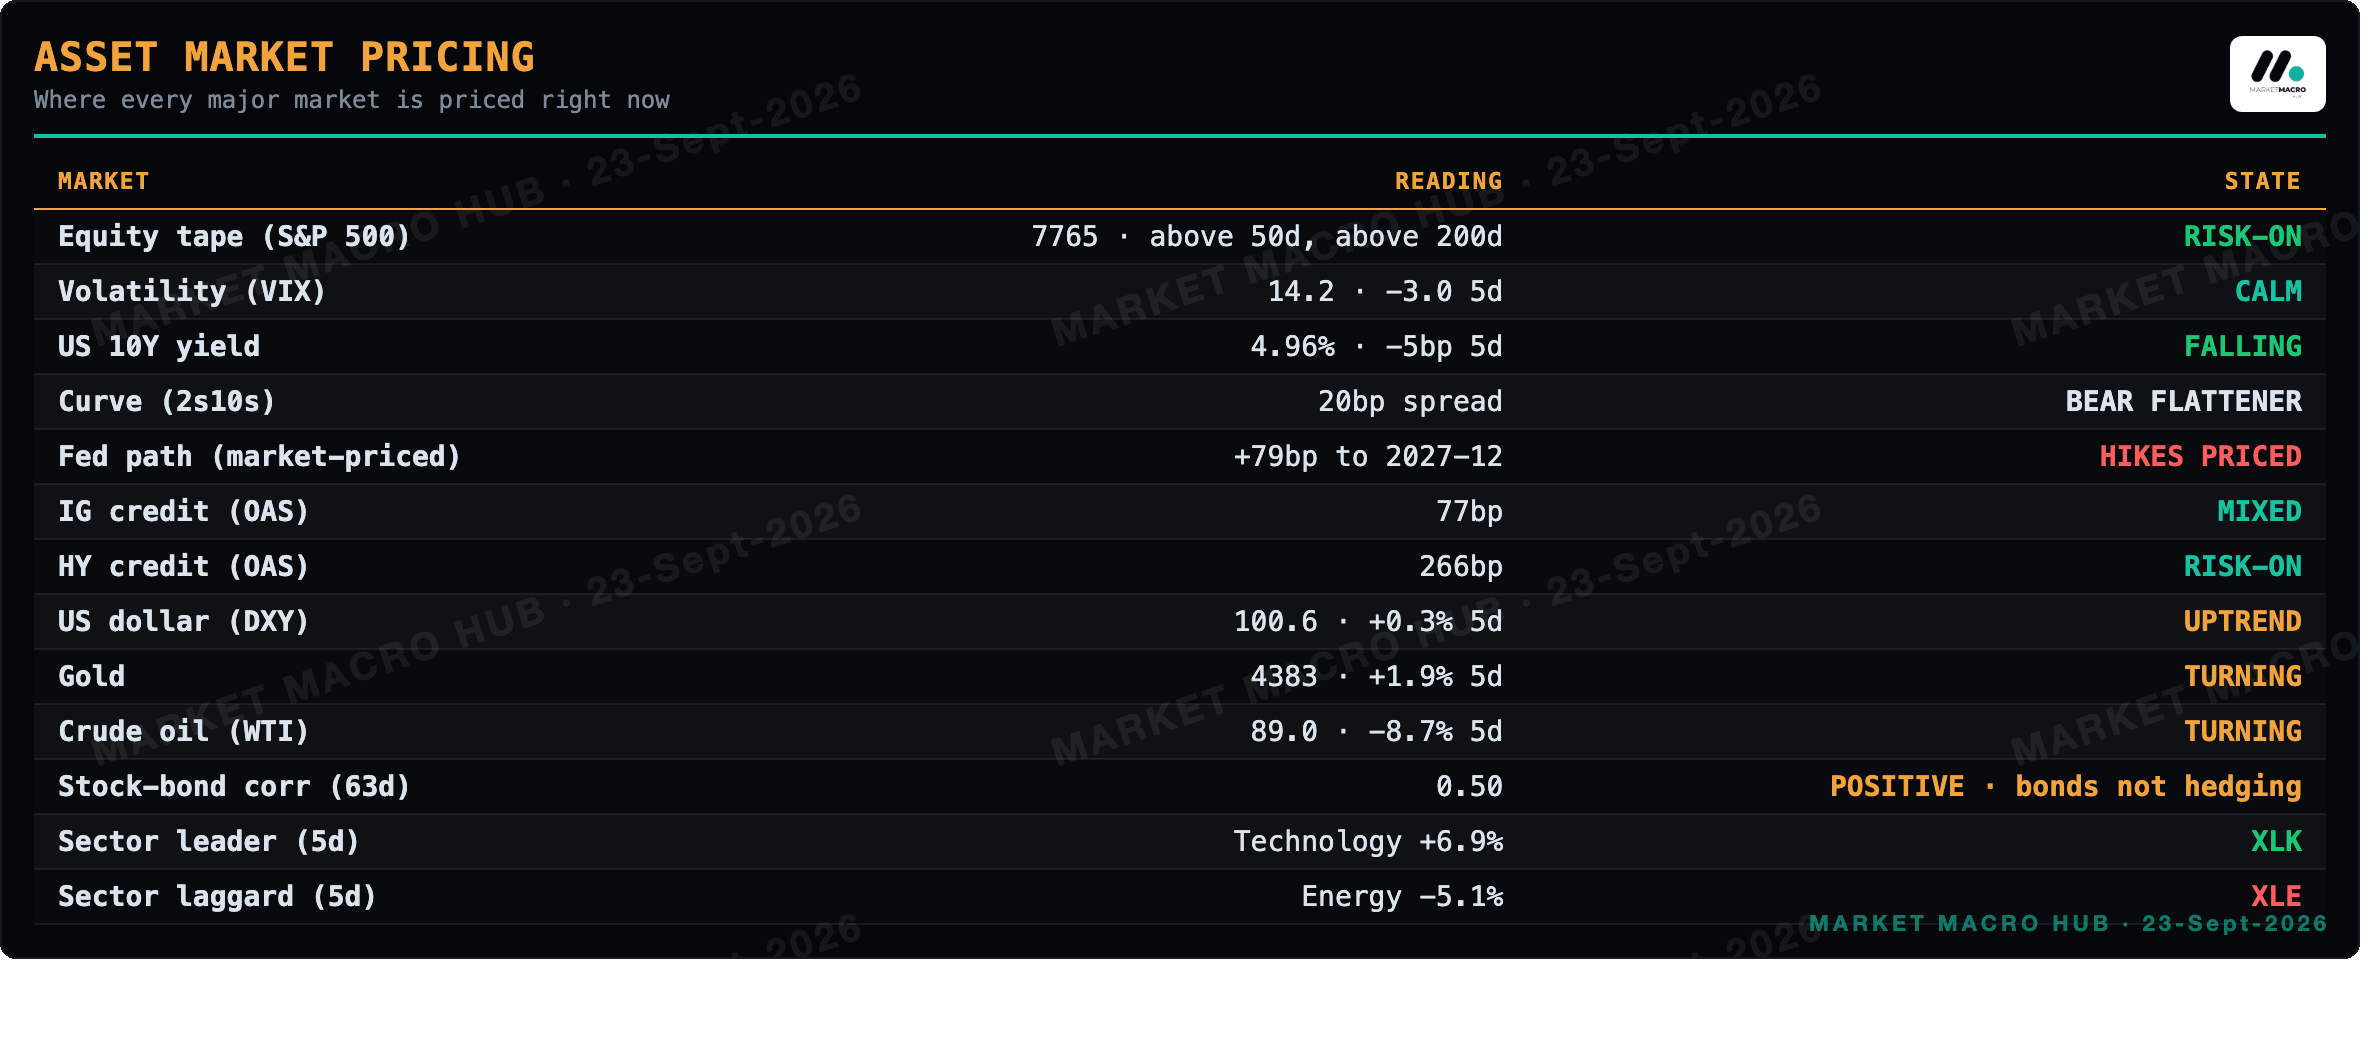
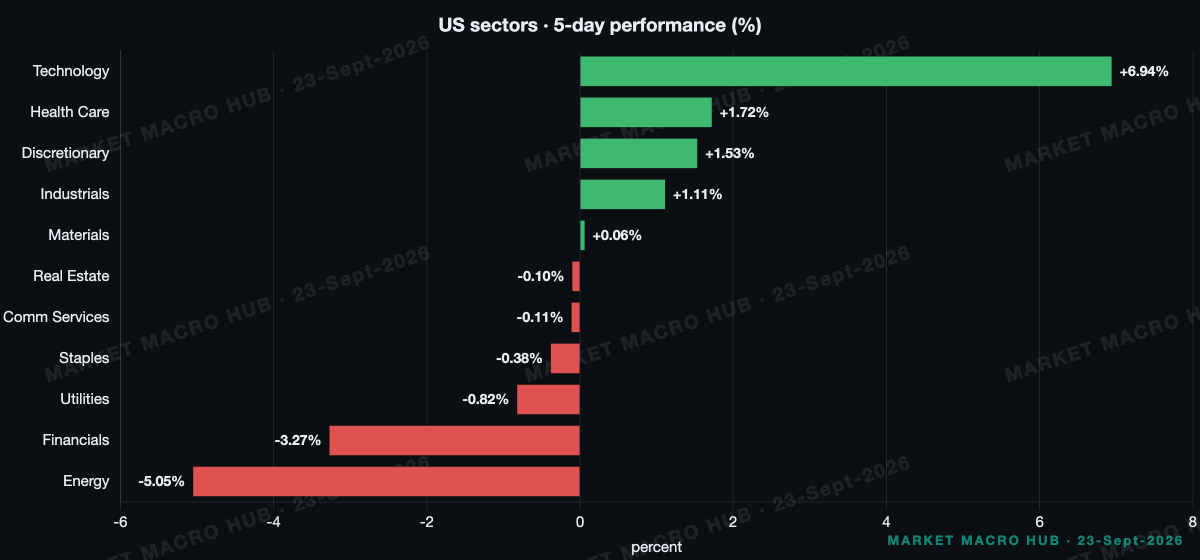
Session 2026-09-22. Sectors plus the unexplained remainder sum to the index move.
Momentum Book · Sticky Regimes
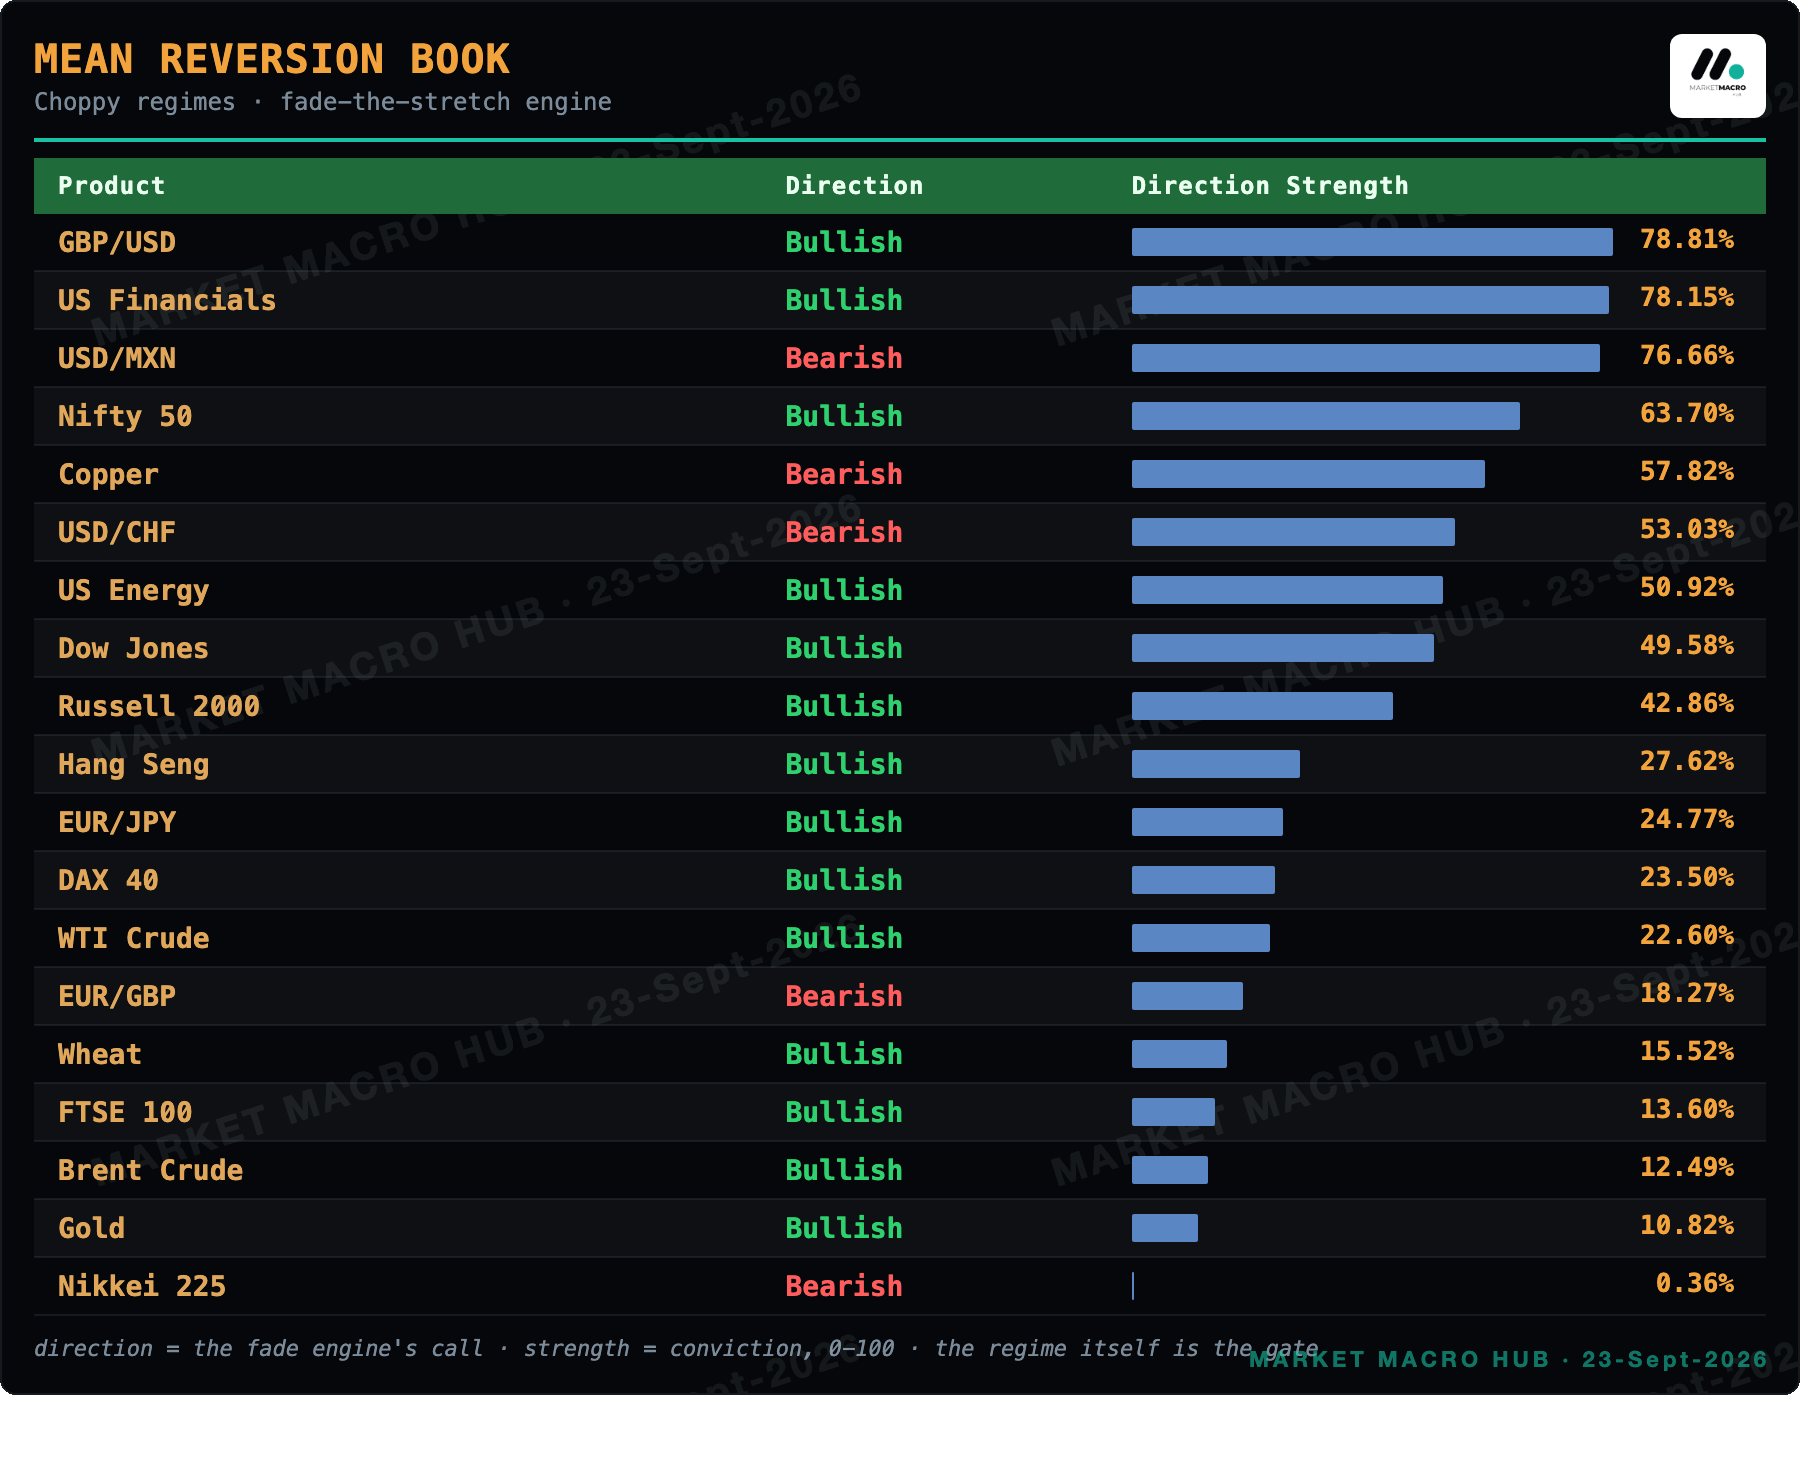
Mean Reversion Book · Choppy Regimes
Sector Snapshot & Breadth
Main Developments in Macro
TRUMP SAYS US-IRAN MEETING "VERY PRODUCTIVE", ANOTHER ROUND SCHEDULED; WARNS ON PICKAXE MOUNTAIN STRIKES
IRANIAN SOURCES SAY POSITION UNCHANGED, HORMUZ STAYS SHUT UNTIL CONDITIONS MET
FED'S BARKIN SAYS HIKE HELPS RESTORE PRICE STABILITY, MUCH OF PCE CLIMBING OVER 3%
NDX PRINTS ALL-TIME HIGH ON SEMIS AND MEMORY; SPX FLAT AS FINANCIALS AND ENERGY LAG
HANG SENG SUBDUED ON PBOC LIQUIDITY DRAIN, XI-TRUMP SUMMIT HOPES TEMPERED
MACRON SAYS FRANCE READY TO JOIN DEFENSIVE HORMUZ NAVIGATION OPERATION
The prints lean firm on inflation risk and soft on the interest-rate-sensitive parts. Philadelphia Fed manufacturing came in at 37.8 against a 30.5 consensus, while housing and industrial production both undershot. Barkin said the Fed hiked because inflation risks outweigh employment risks, and that much of PCE is climbing by more than 3%, while the labour market is not overheated. That is the growth-holds, inflation-sticky mix that keeps the hike bid alive.
Cross-Asset Read
The index went nowhere but the internals split hard. Financials dragged the most at -0.26pp and communications took off another -0.10pp, while tech added +0.23pp. The residual is real here, so the sector split explains none of a flat tape. WTI drifted lower again on Iran diplomacy hopes, down on the day and heavy on the week.
One correlation move matters. SPX versus Bitcoin sits at 0.42 now against 0.16 a month ago, flagged as a big shift. Bitcoin is losing its diversifier value against equity risk, so I trust it less as an offset here.
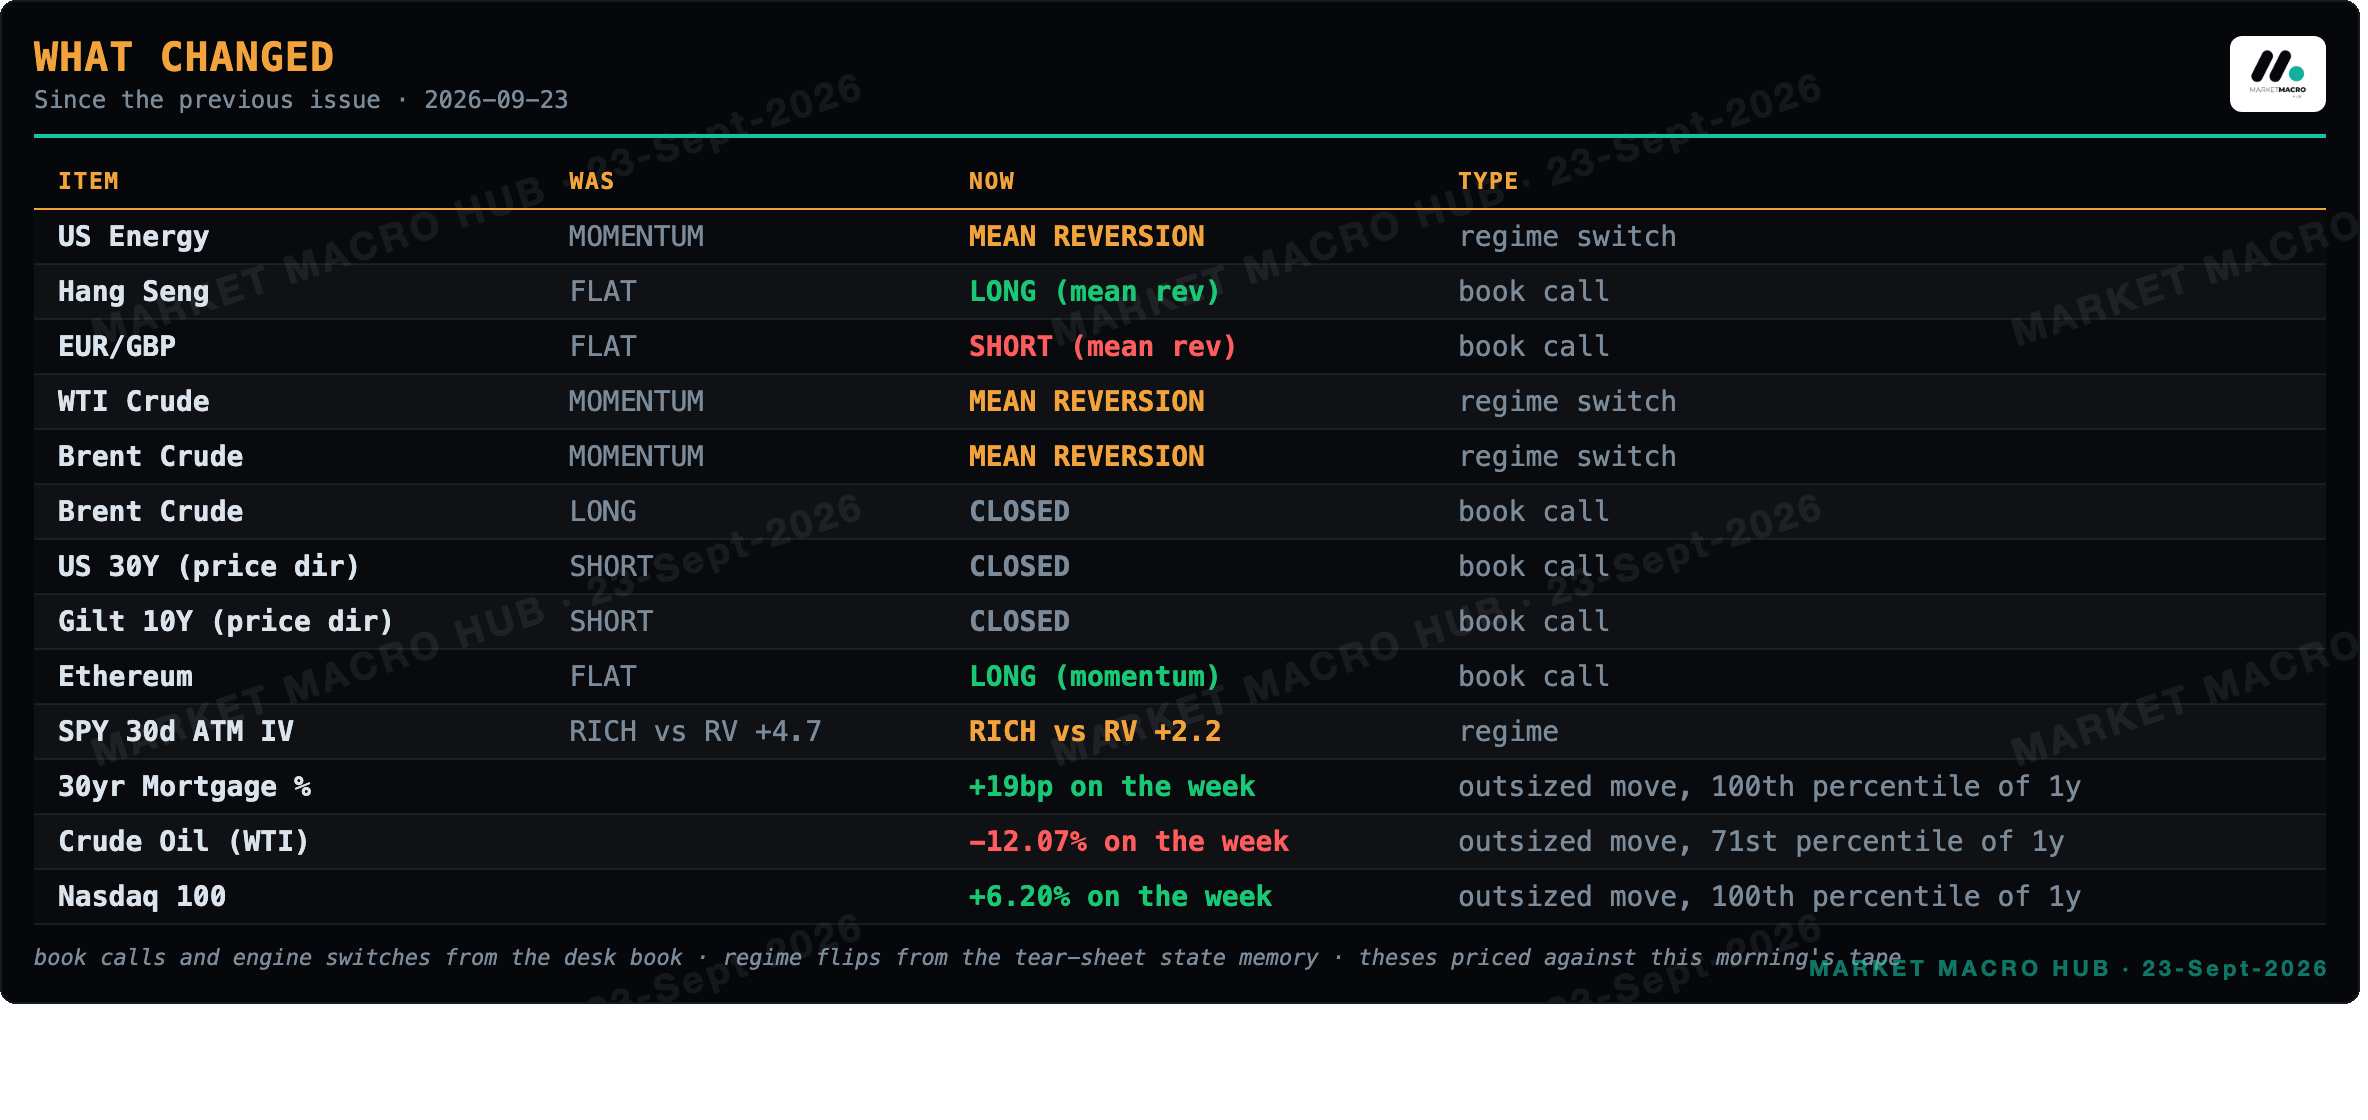
Credit gives me no anxiety. IG at 77bp sits at the tight end of its own range and HY at 266bp is priced as if default risk has vanished. That anchors me long risk against the rates move, invalidation stays 90bp.
Rates & Fed Pricing
No cut is priced anywhere, so this is entirely a hike question. November is half-priced at around 54%, December is effectively certain. The strip peaks at 4.67% in September 2027, +79bp cumulative over EFFR, and the terminal repriced +42.5bp on the week. That is a big weekly build and the 2s10s flattened 12bp over the same stretch, which tells me the front-end is doing the repricing while the long-end sits still.
What changes my mind is the 2s10s reversing its flattening. That would confirm the market doubts the full path and vindicate my terminal call. Until then I respect the flattener and hold the read.
The Week Ahead
Wednesday: S&P Global flash PMIs, a soft services print below 56 would ease my inflation-sticky read, a beat hardens the hike bid.
Wednesday: Fed Barr speech and EIA crude stocks, watching Barr for any push against the front-end pricing.
Thursday: Trump-Xi summit, headline risk for Hang Seng and copper more than US rates.
Thursday: UN General Assembly and Fed Williams, Williams is the one that moves the strip if he leans.
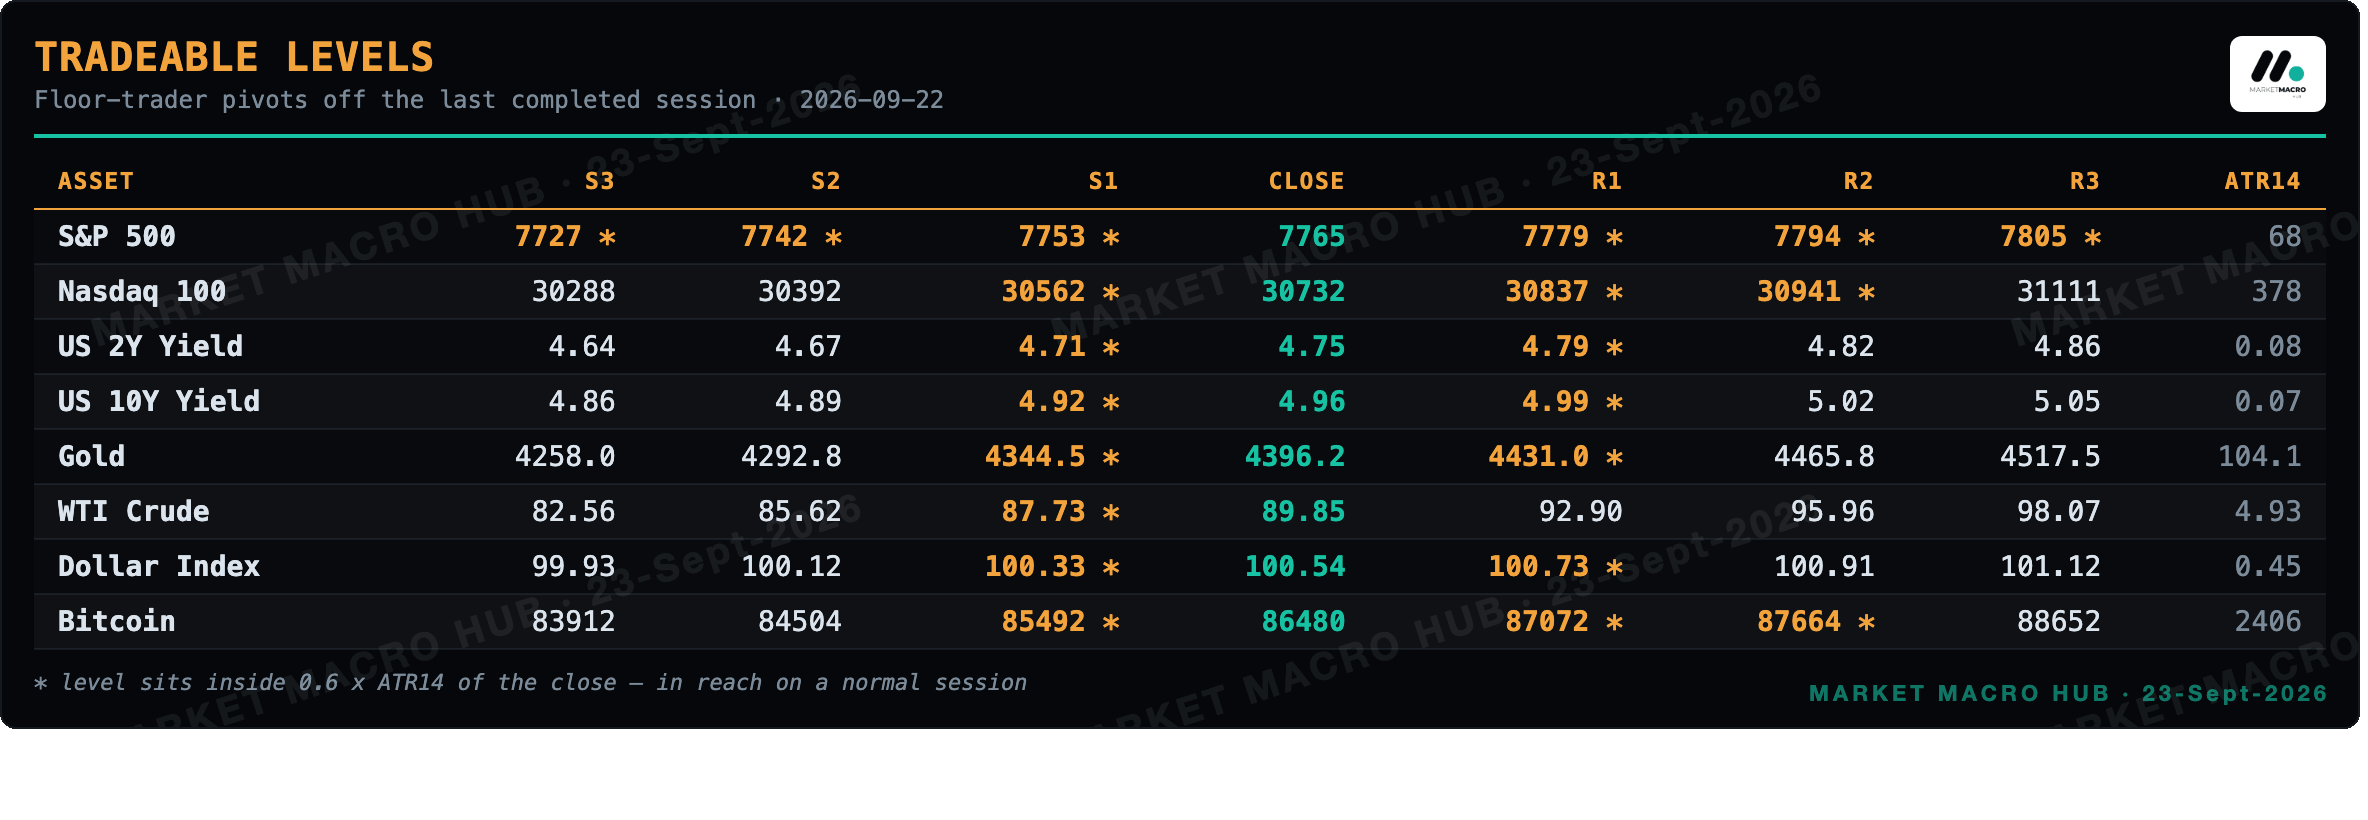
Tradeable Levels
Pivots off the last completed session (2026-09-22). Levels marked * sit within 0.6 x ATR14 of the close.
Vol Screen · Rich and Cheap Implied Vol
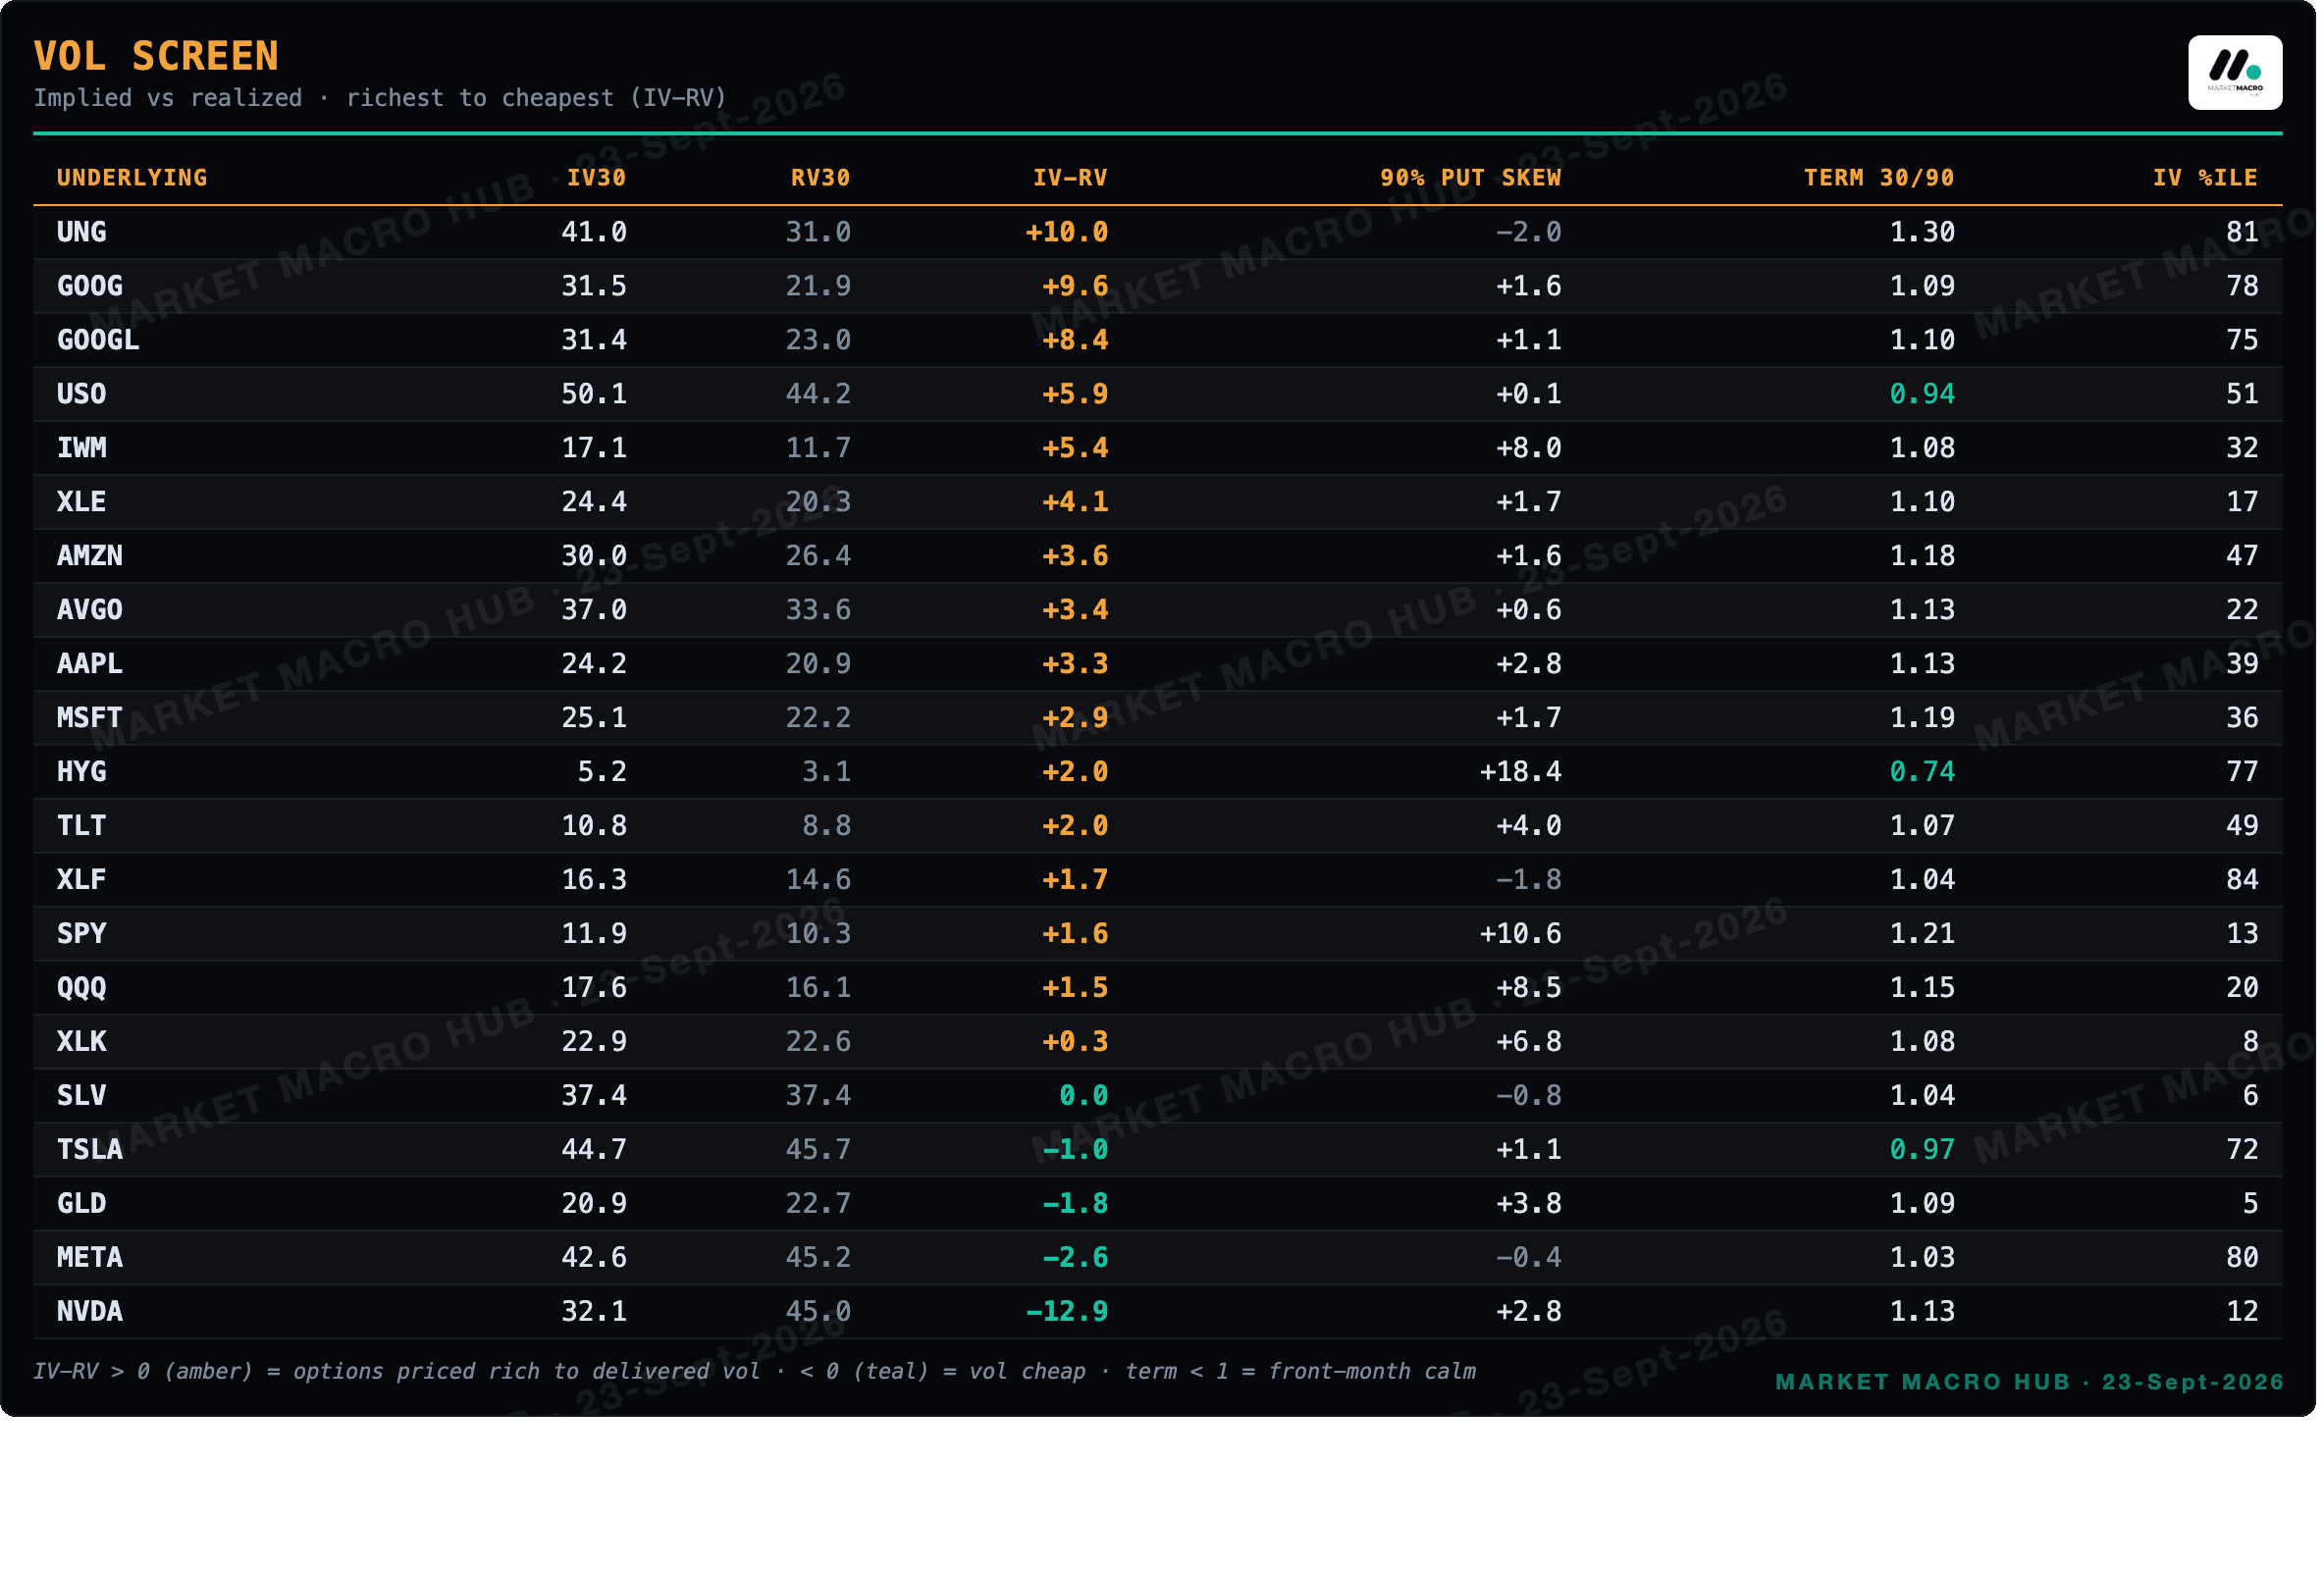
Positive IV-RV = options priced rich to what the tape is delivering (UNG and GOOG richest today); negative = vol going cheap (NVDA and META). Percentiles are each name's own archive history.
Disclaimer
The information in this publication is provided for informational and educational purposes only and is believed to be reliable, but its accuracy and completeness are not guaranteed. Nothing herein constitutes investment advice, an offer, or a solicitation to buy or sell any security, derivative, digital asset, or other financial instrument, nor a recommendation suited to any specific reader. All figures are drawn from the day's computed data set at the time of generation and may be delayed, revised, or superseded. Markets involve risk, including the possible loss of principal; past performance and historical relationships do not guarantee future results. Readers should conduct their own research and consult a qualified financial adviser before making any investment decision. The author may hold positions in instruments discussed. This publication is licensed for the personal use of the subscriber only: redistribution, reproduction, or resale in any form is prohibited. © 2026 MARKET MACRO HUB. All rights reserved.