


Today's Tear Sheets
The full daily pack is attached below · six PDFs generated from the same computed data set as this note:
Macro Regime · curve regimes, growth x inflation quadrant, breadth, credit, vol term structure, liquidity, stock-bond correlation, crypto cross-asset, housing
Fixed Income · UST complex, global curves, Fed/ECB/BoE/BoJ implied policy paths, global 2Y and 10Y panels
Equities · index pages, relatives, vol suite, global relatives, Mag7+ quant sheet, options surfaces
FX · majors dashboards, correlations, COT positioning, crosses
Commodities · energy, metals, agriculture, COT crowding, term structure
Crypto · BTC ladders, ETH, macro correlations, ETF flow proxy

TL;DR
I'm long the near-certain hike story but I can't see the full SEP path getting realised.
2s10s at 33bp is my tell; more flattening confirms doubt on the path beyond October.
Copper longs at the 100th percentile keep me off the long side.
IG carry at 80bp is my anchor, invalidation 90bp.
Gold's -0.59 link to the dollar argues for smaller hedges today.
Where We Stand
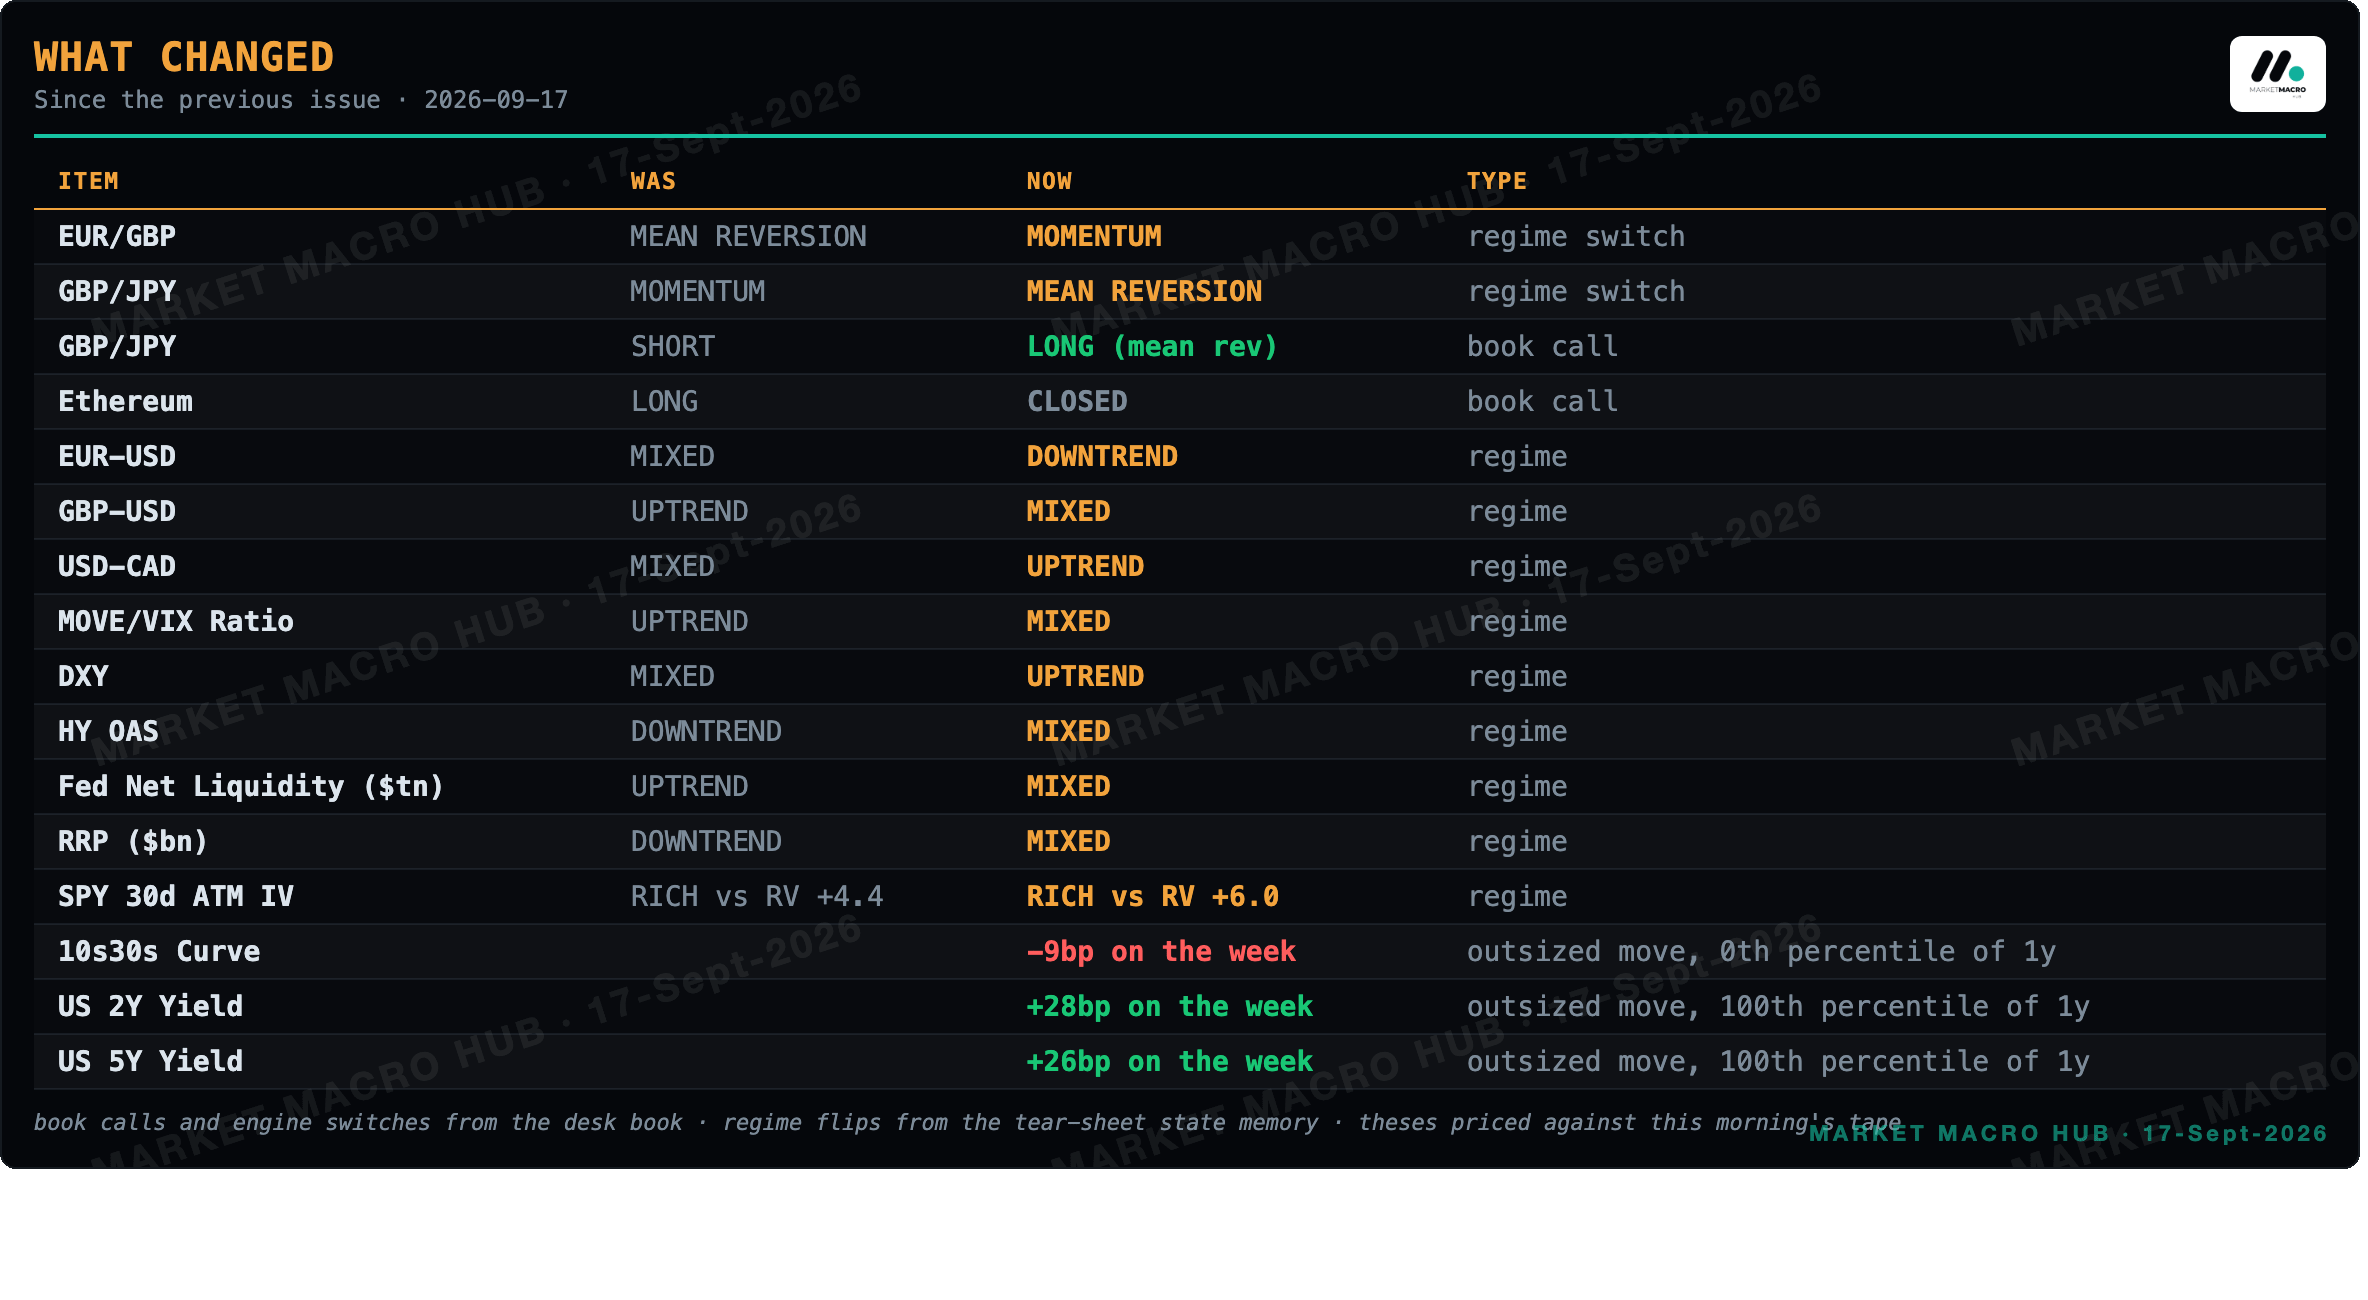
Yesterday I said I'm not fading the near-certain hike and that the risk sits in the path beyond it, with the 2s10s at 32bp as my tell. This morning's tape confirms it. The Fed delivered the 25bp move and the dots pencilled in another by year-end, yet the terminal repriced +40.5bp on the day and +65bp on the week, so the market is now doing the work of pricing the whole SEP path. My oldest live view, copper crowding opened three days ago, stays exactly where it was. The copper crowding flag is still live, longs sit at the 100th percentile, and I stay off the long side. My IG anchor holds too, OAS at 80bp with invalidation at 90bp, and credit is giving me nothing to worry about.
What Changed
Asset Market Pricing
Sector Attribution
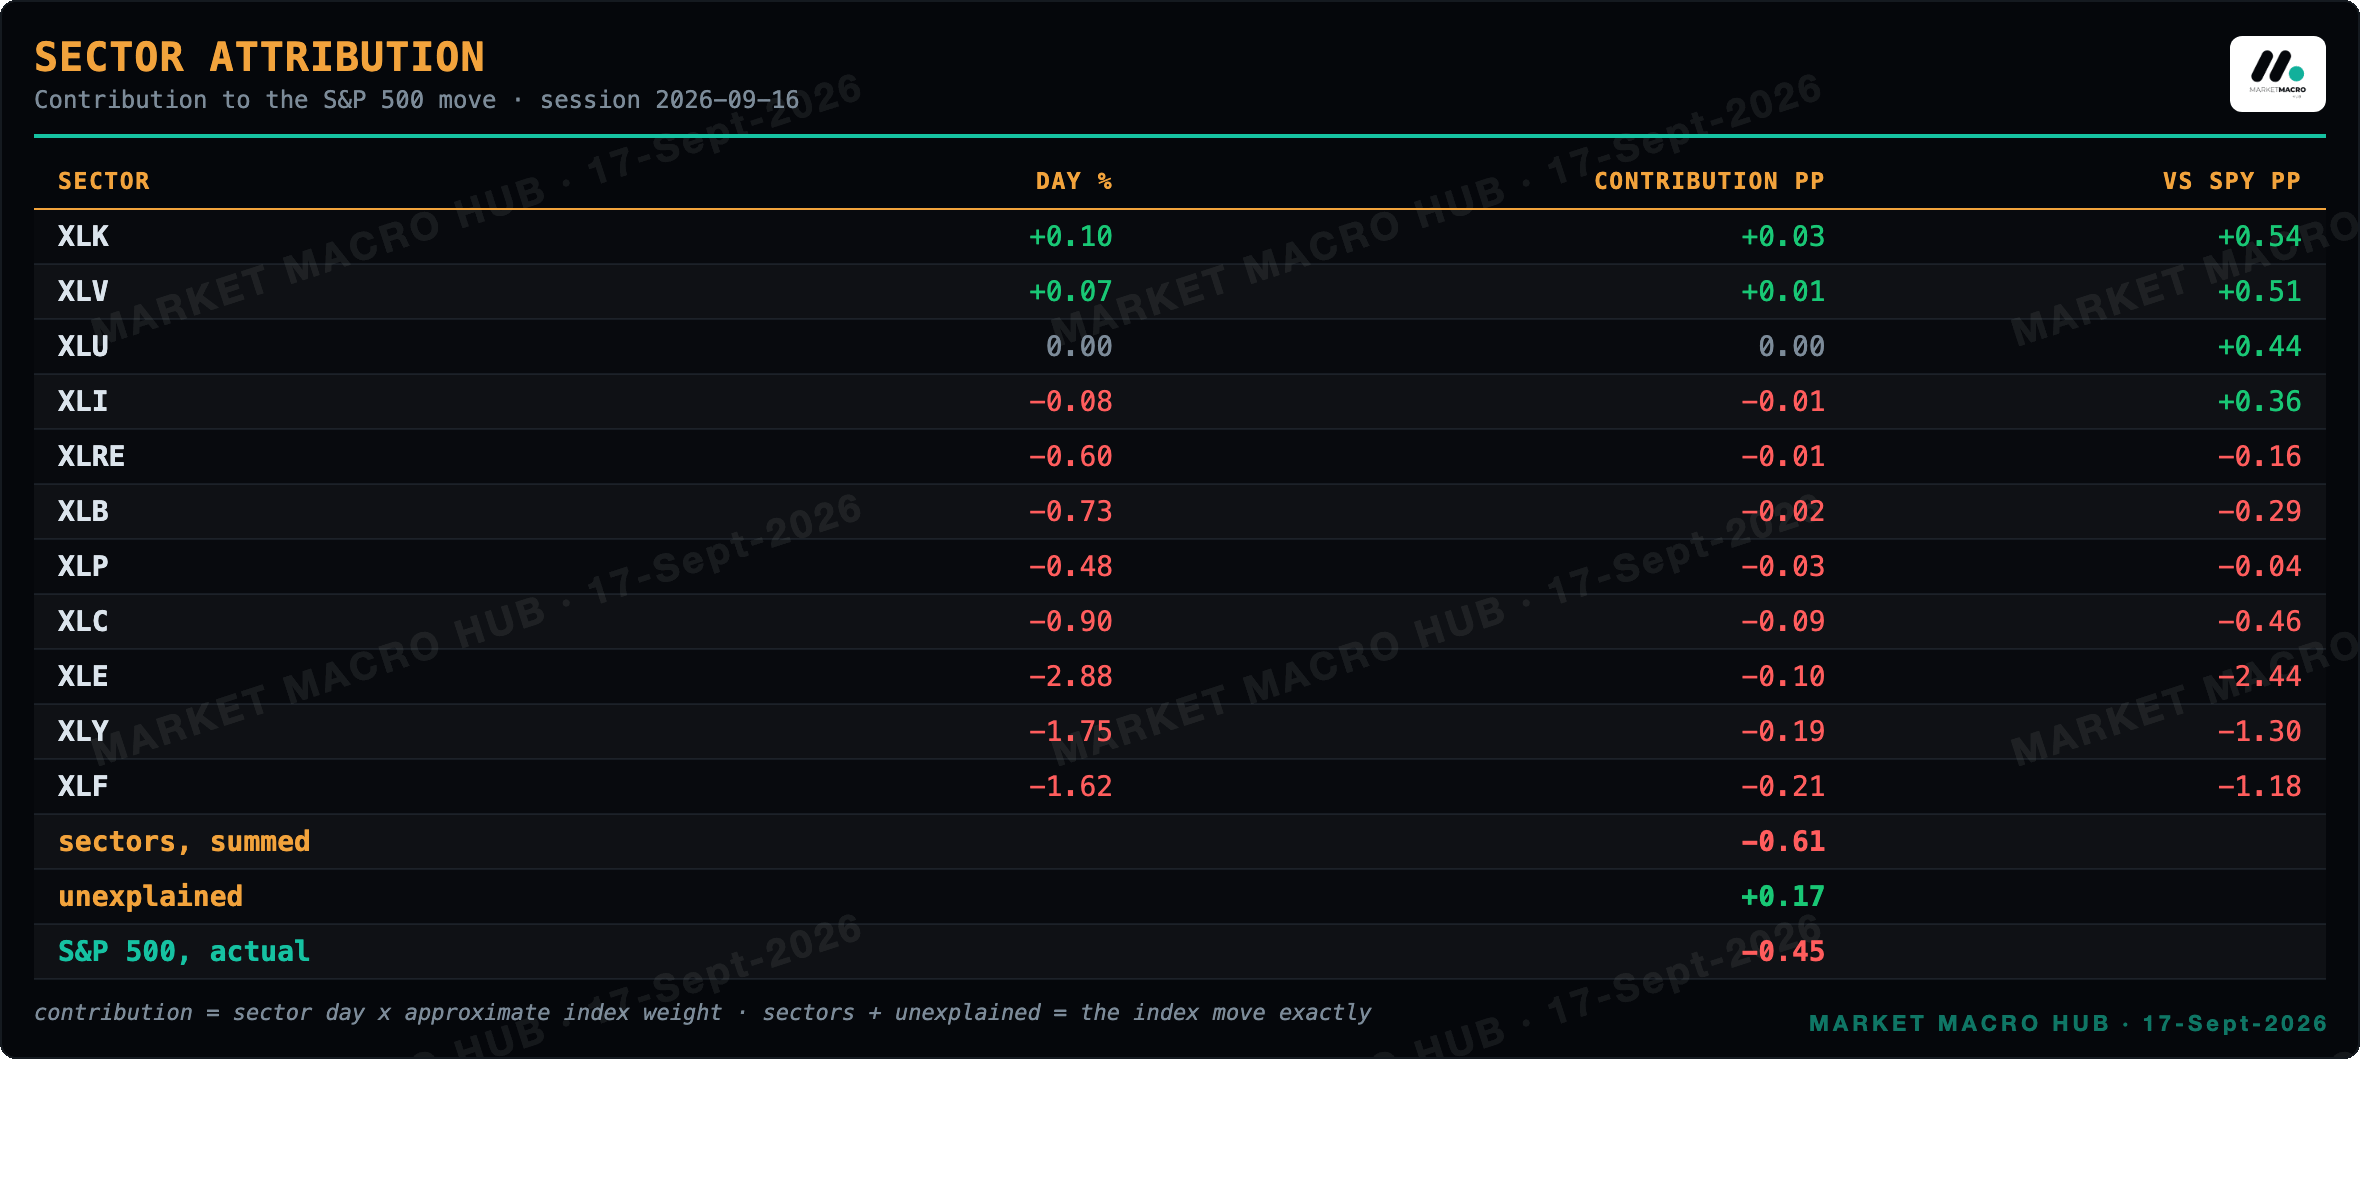
Session 2026-09-16. Sectors plus the unexplained remainder sum to the index move, and the sector split accounts for 63% of it.
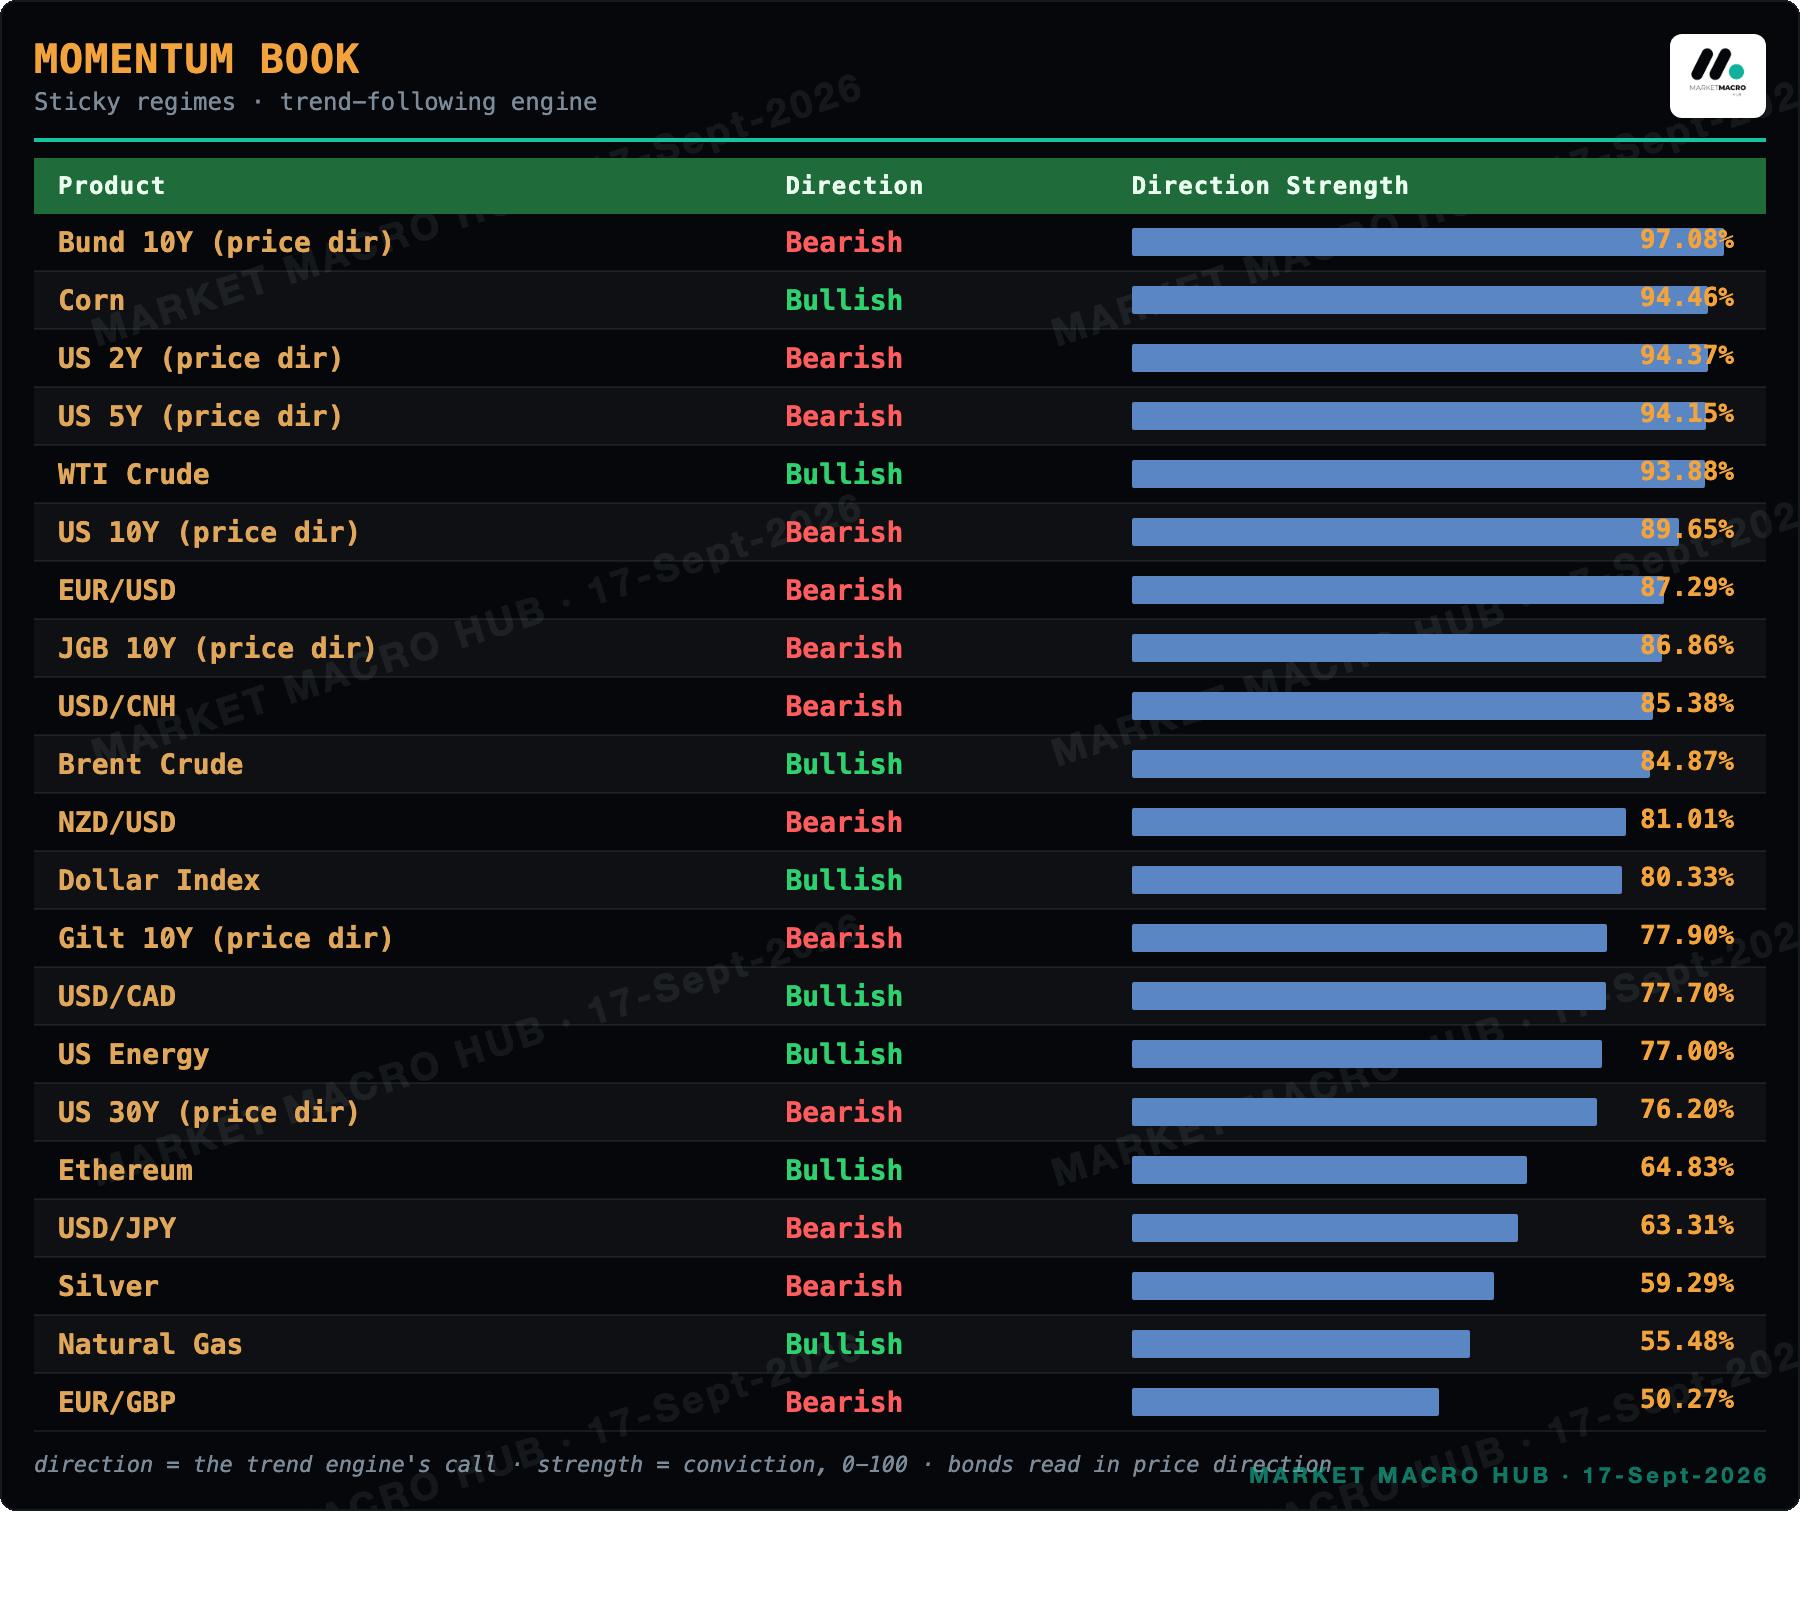
Momentum Book · Sticky Regimes
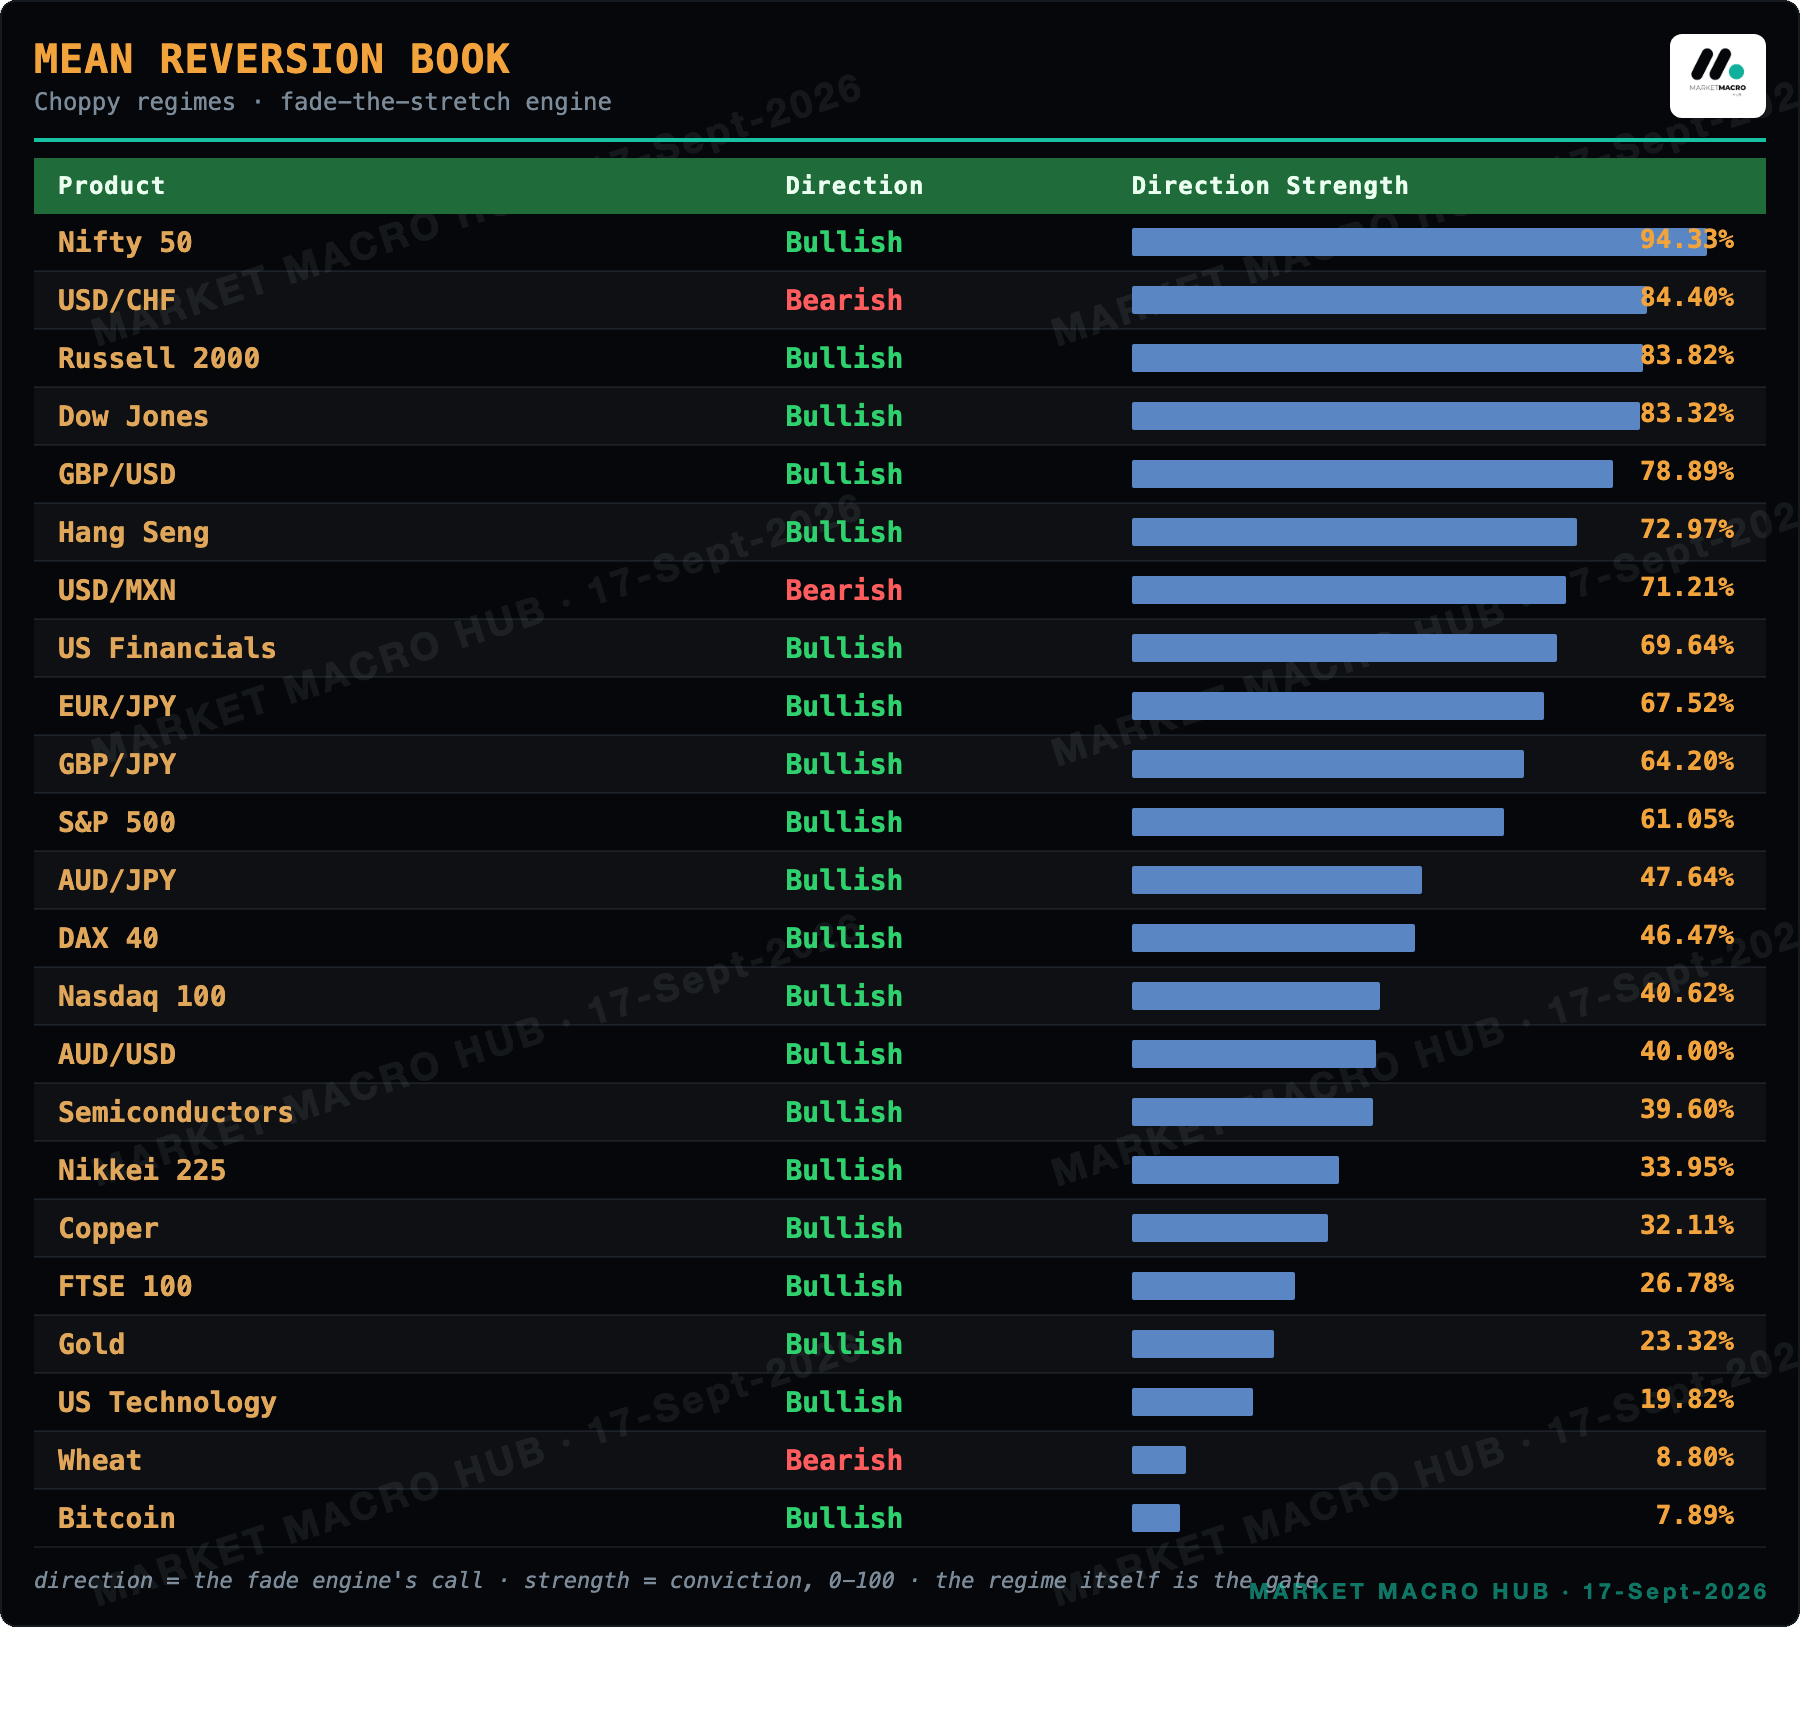
Mean Reversion Book · Choppy Regimes
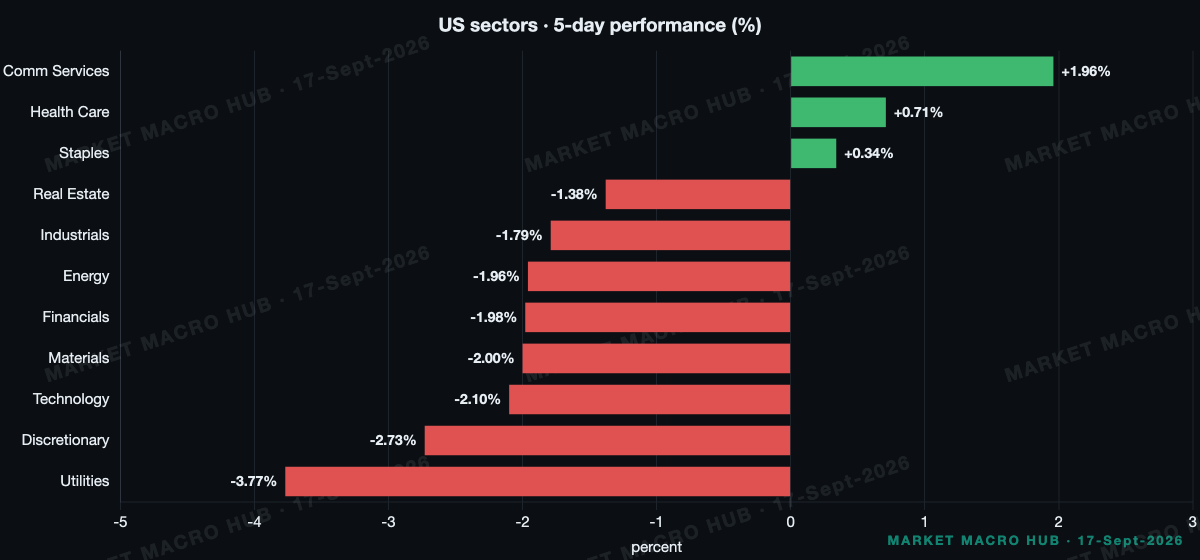
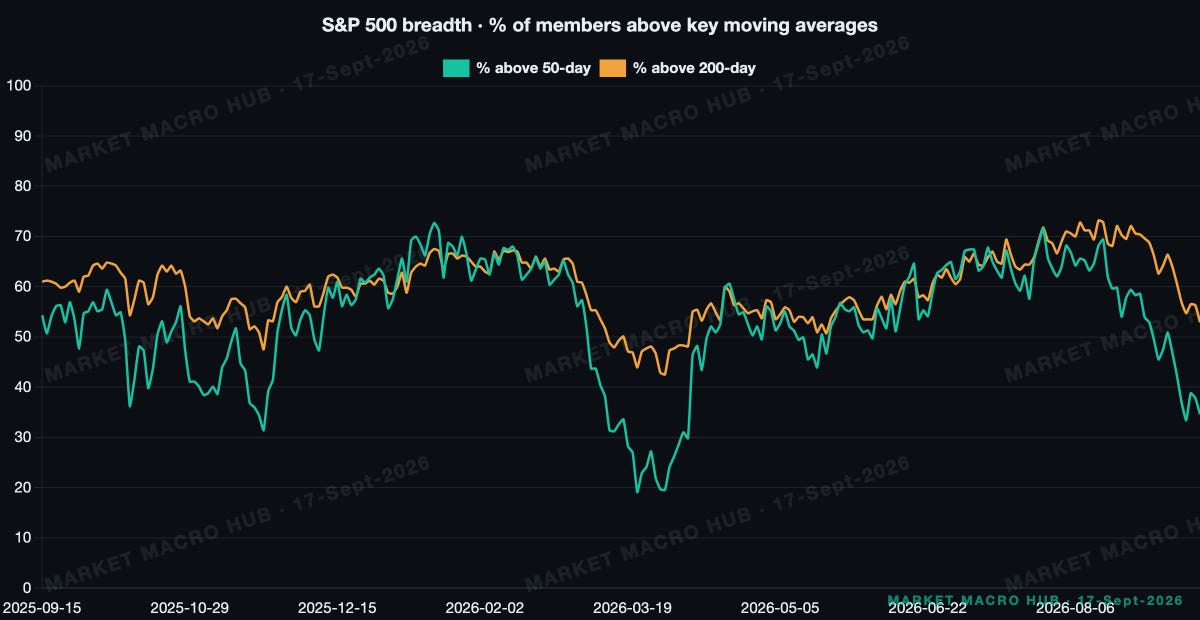
Sector Snapshot & Breadth
Main Developments in Macro
FED HIKED 25BP TO 3.75-4%, UNANIMOUS, DOTS PENCIL ONE MORE HIKE THIS YEAR THEN HOLD THROUGH 2027
WARSH SAYS HARD-PRESSED TO CALL FINANCIAL CONDITIONS RESTRICTIVE, PRICE STABILITY THE PREDOMINANT FOCUS
TRUMP DEMANDS RATES AT "1% OR LESS", SAYS HE STILL TOLD WARSH TO BE INDEPENDENT
BOE POLICY ANNOUNCEMENT DUE, RATES EXPECTED HELD IN A 6-3 SPLIT; CNB ALSO DECIDES
BOJ KICKS OFF TWO-DAY MEETING, WIDELY ANTICIPATED HIKE TOMORROW
HKMA RAISED RATES FIRST TIME SINCE 2023 IN LOCK-STEP WITH THE FED, HANG SENG PRESSURED
TRUMP FLAGS POSSIBLE HEAVY TARIFFS ON EUROPE; US-MEXICO TALKS PUSHED BACK A WEEK
The growth read is hot. Retail Sales rose 1.2% against 0.8% consensus, with the control group at 1.4% versus 0.4%. That is why the front end is repricing so hard. The one soft print, Empire State at 7.6 against 14.75 expected, from 20.6 prior, is not enough to slow a Fed that keeps telling me inflation is the problem.
Cross-Asset Read
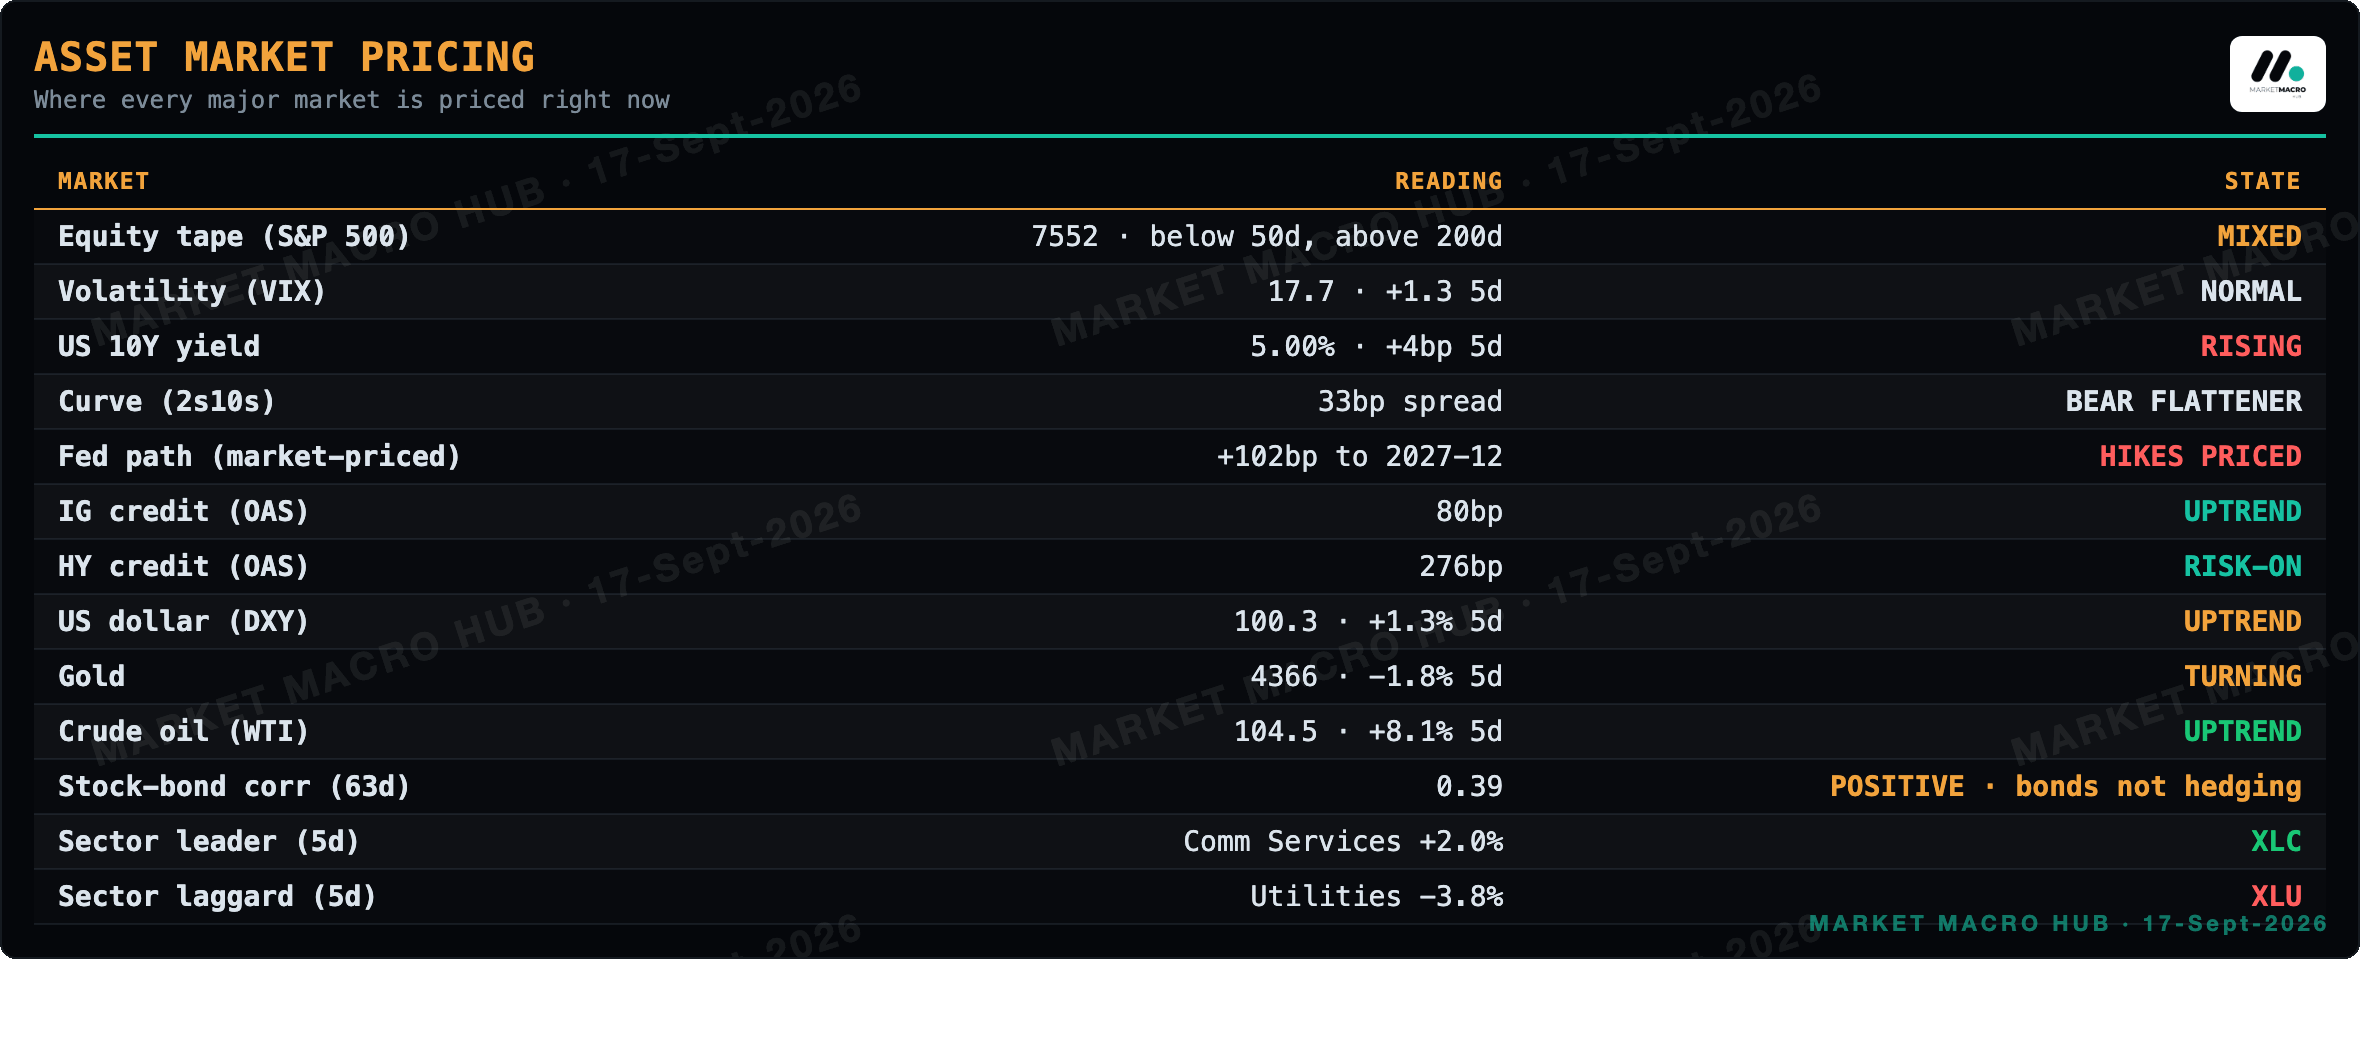
The tape was orderly. The S&P edged down 0.45% while the Nasdaq 100 held flat. Financials and discretionary did the damage, together roughly -0.4pp of the move, with energy the worst single sector. The residual is real, so I read this as a rate-repricing session rather than a growth scare.
The correlation I care about most this morning is gold against the dollar, now -0.59 versus -0.41 a month ago. That deeper inverse link is why I keep gold hedges smaller here. Credit backs the calm read. IG OAS sits at 80bp, the tight end of its own range and well inside the 90bp mean, and HY at the low end tells me risk appetite is intact.
Rates & Fed Pricing
No month on the strip has a cut half-priced, so this is entirely a tightening story. September is the first month with a hike at least half-priced, near 100% odds. The strip peaks in November 2027 at 4.68%, some +105bp cumulative over EFFR, with the trough already +26.5bp.
The why is the SEP and Warsh. He would not call conditions restrictive and the median now sees one more hike before a long hold. The two-year jumped +28bp on the week doing that work. What changes my mind is the long end: more 2s10s flattening from 33bp tells me the market doubts the back of the path, and I lean into that doubt. If the belly instead keeps selling with equities steady, I have to respect a real terminal move.
The Week Ahead
Thursday: Initial Jobless Claims (cons 208), the clean read on whether the labour market cracks; a big miss is what shifts my growth call.
Thursday: Housing Starts and Building Permits, secondary after a soft NAHB, unlikely to move my read.
Thursday: Philadelphia Fed (cons 30.5 from 47.4), watching for confirmation of the Empire State softness.
Thursday: Pending Home Sales, rate-sensitive but not a read-changer.
Thursday: BoE and CNB decisions plus ECB's Lane, relevant for the dollar leg.
Friday: Industrial Production and Fed's Bowman, her tone on the path is what I want after this SEP.
Tradeable Levels
Pivots off the last completed session (2026-09-16). Levels marked * sit within 0.6 x ATR14 of the close.
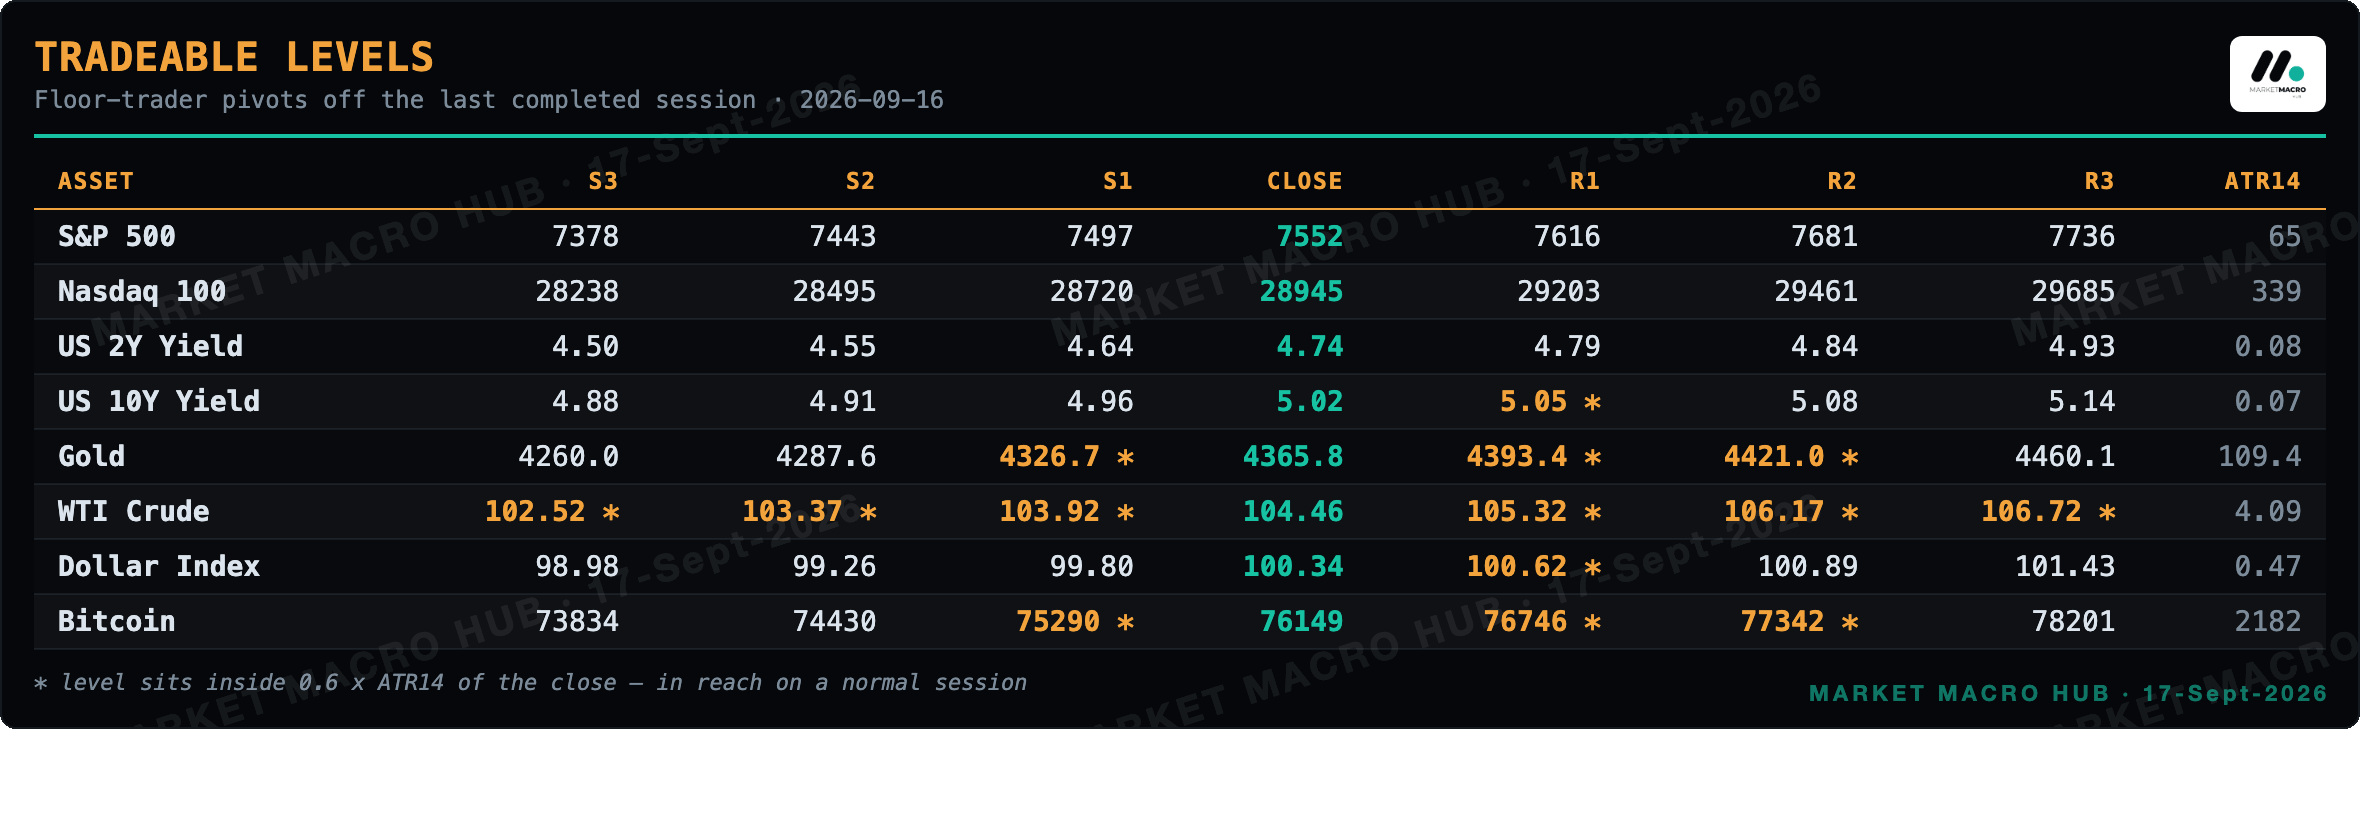
WTI Crude priced off a session whose range was under a third of normal travel, so that board is compressed and nearly every level sits in reach. Weekend crypto and half-day holiday sessions do this; treat the levels as loose rather than precise.
Vol Screen · Rich and Cheap Implied Vol
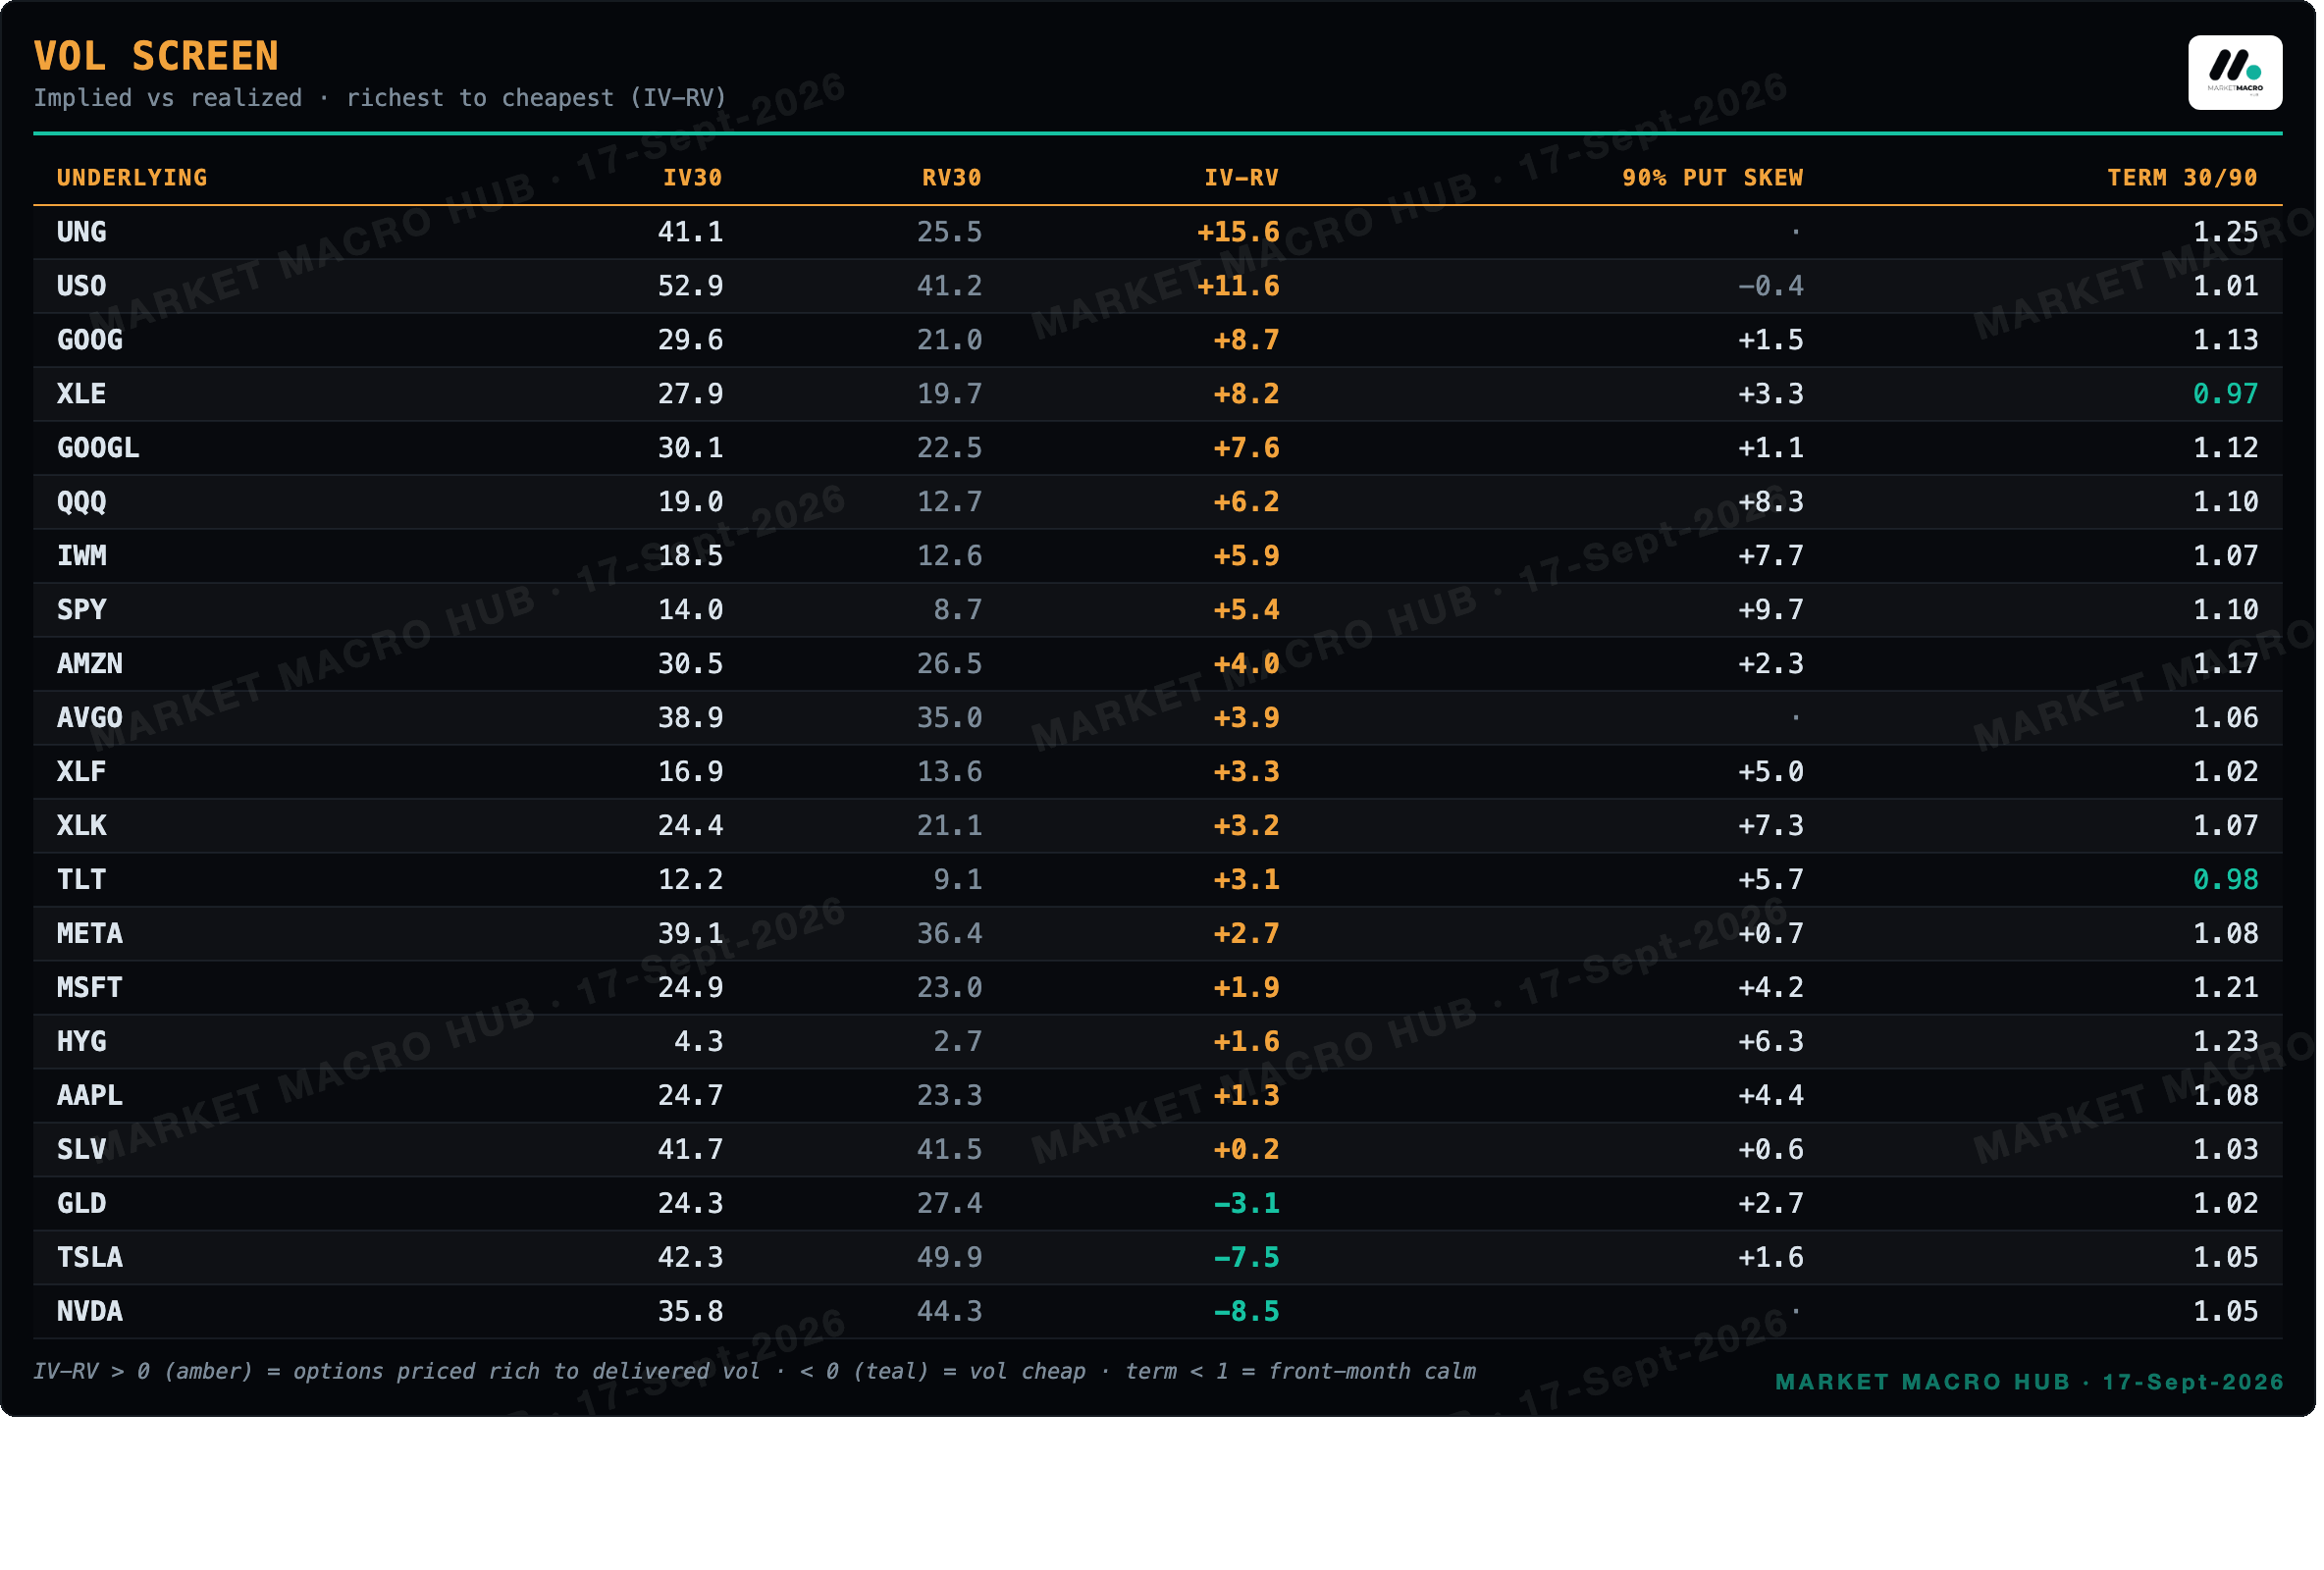
Positive IV-RV = options priced rich to what the tape is delivering (UNG and USO richest today); negative = vol going cheap (NVDA and TSLA).
Disclaimer
The information in this publication is provided for informational and educational purposes only and is believed to be reliable, but its accuracy and completeness are not guaranteed. Nothing herein constitutes investment advice, an offer, or a solicitation to buy or sell any security, derivative, digital asset, or other financial instrument, nor a recommendation suited to any specific reader. All figures are drawn from the day's computed data set at the time of generation and may be delayed, revised, or superseded. Markets involve risk, including the possible loss of principal; past performance and historical relationships do not guarantee future results. Readers should conduct their own research and consult a qualified financial adviser before making any investment decision. The author may hold positions in instruments discussed. This publication is licensed for the personal use of the subscriber only: redistribution, reproduction, or resale in any form is prohibited. © 2026 MARKET MACRO HUB. All rights reserved.