

The first place I want to start is in credit spreads. We have seen credit spreads move higher, towards the March 2026 highs and mid April 2025 levels. The key thing to note is that even as this has happened, ES actually set a low and is not being dragged by these movements in credit.
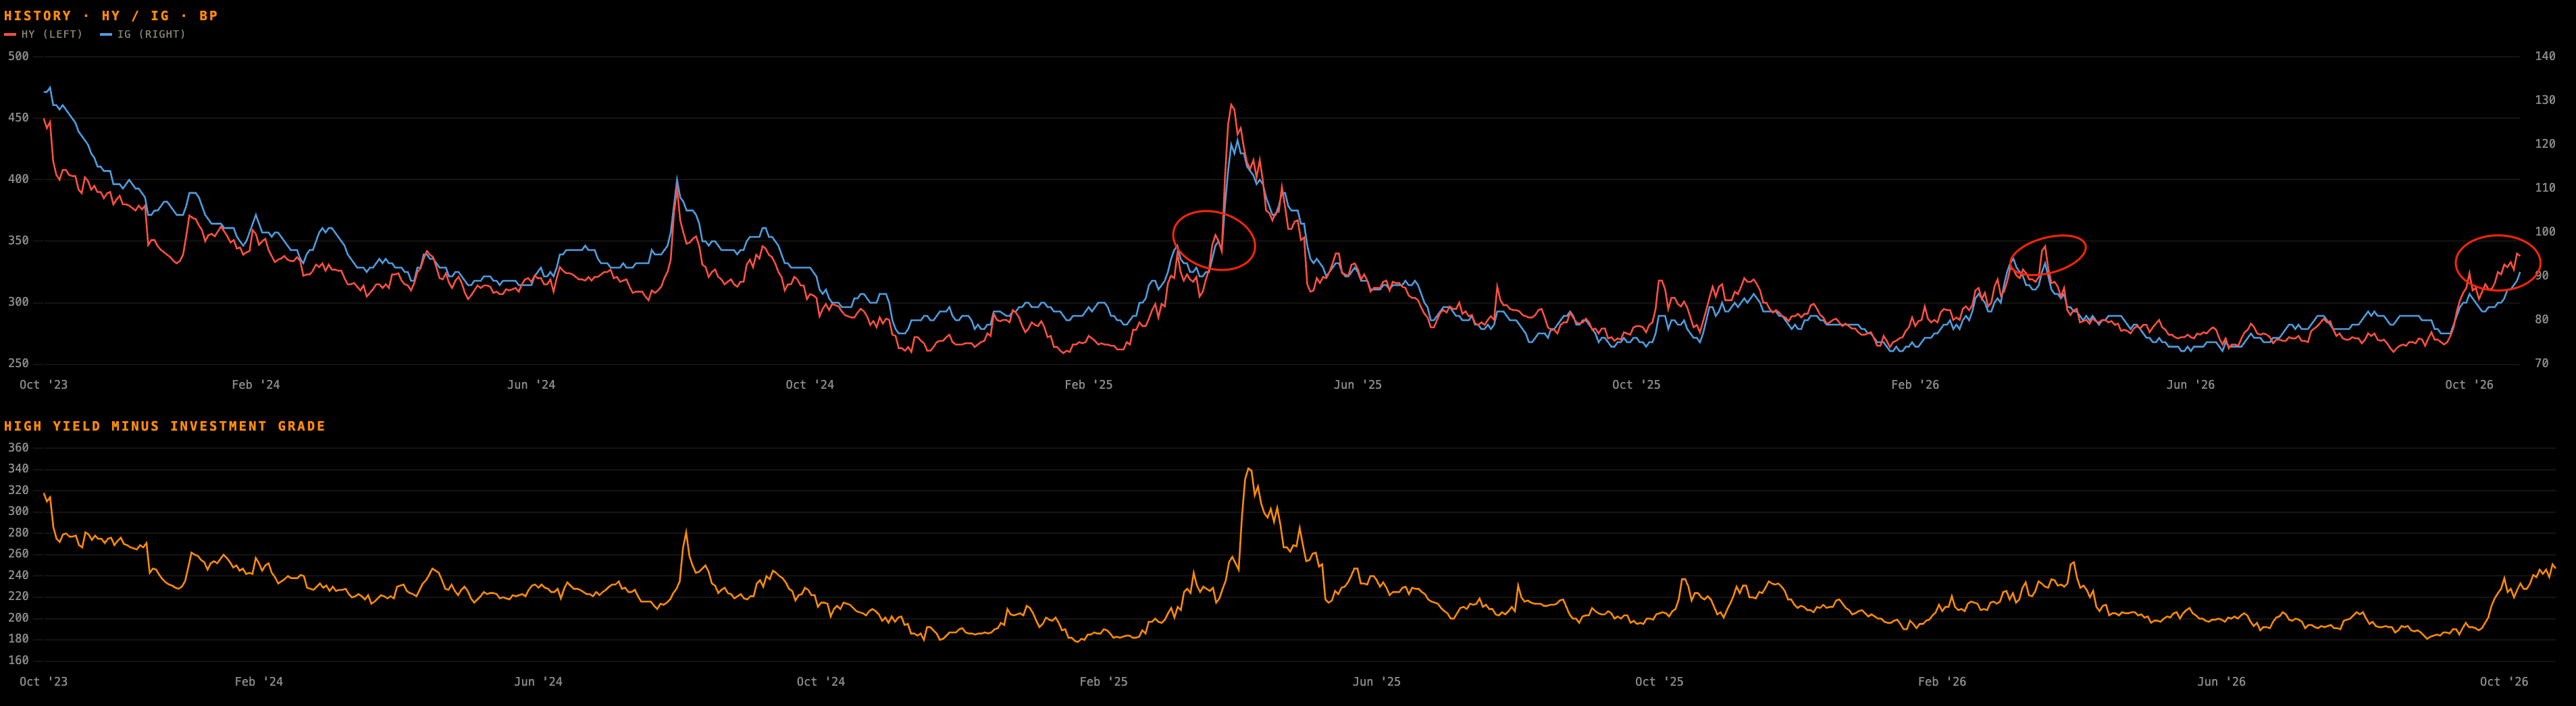
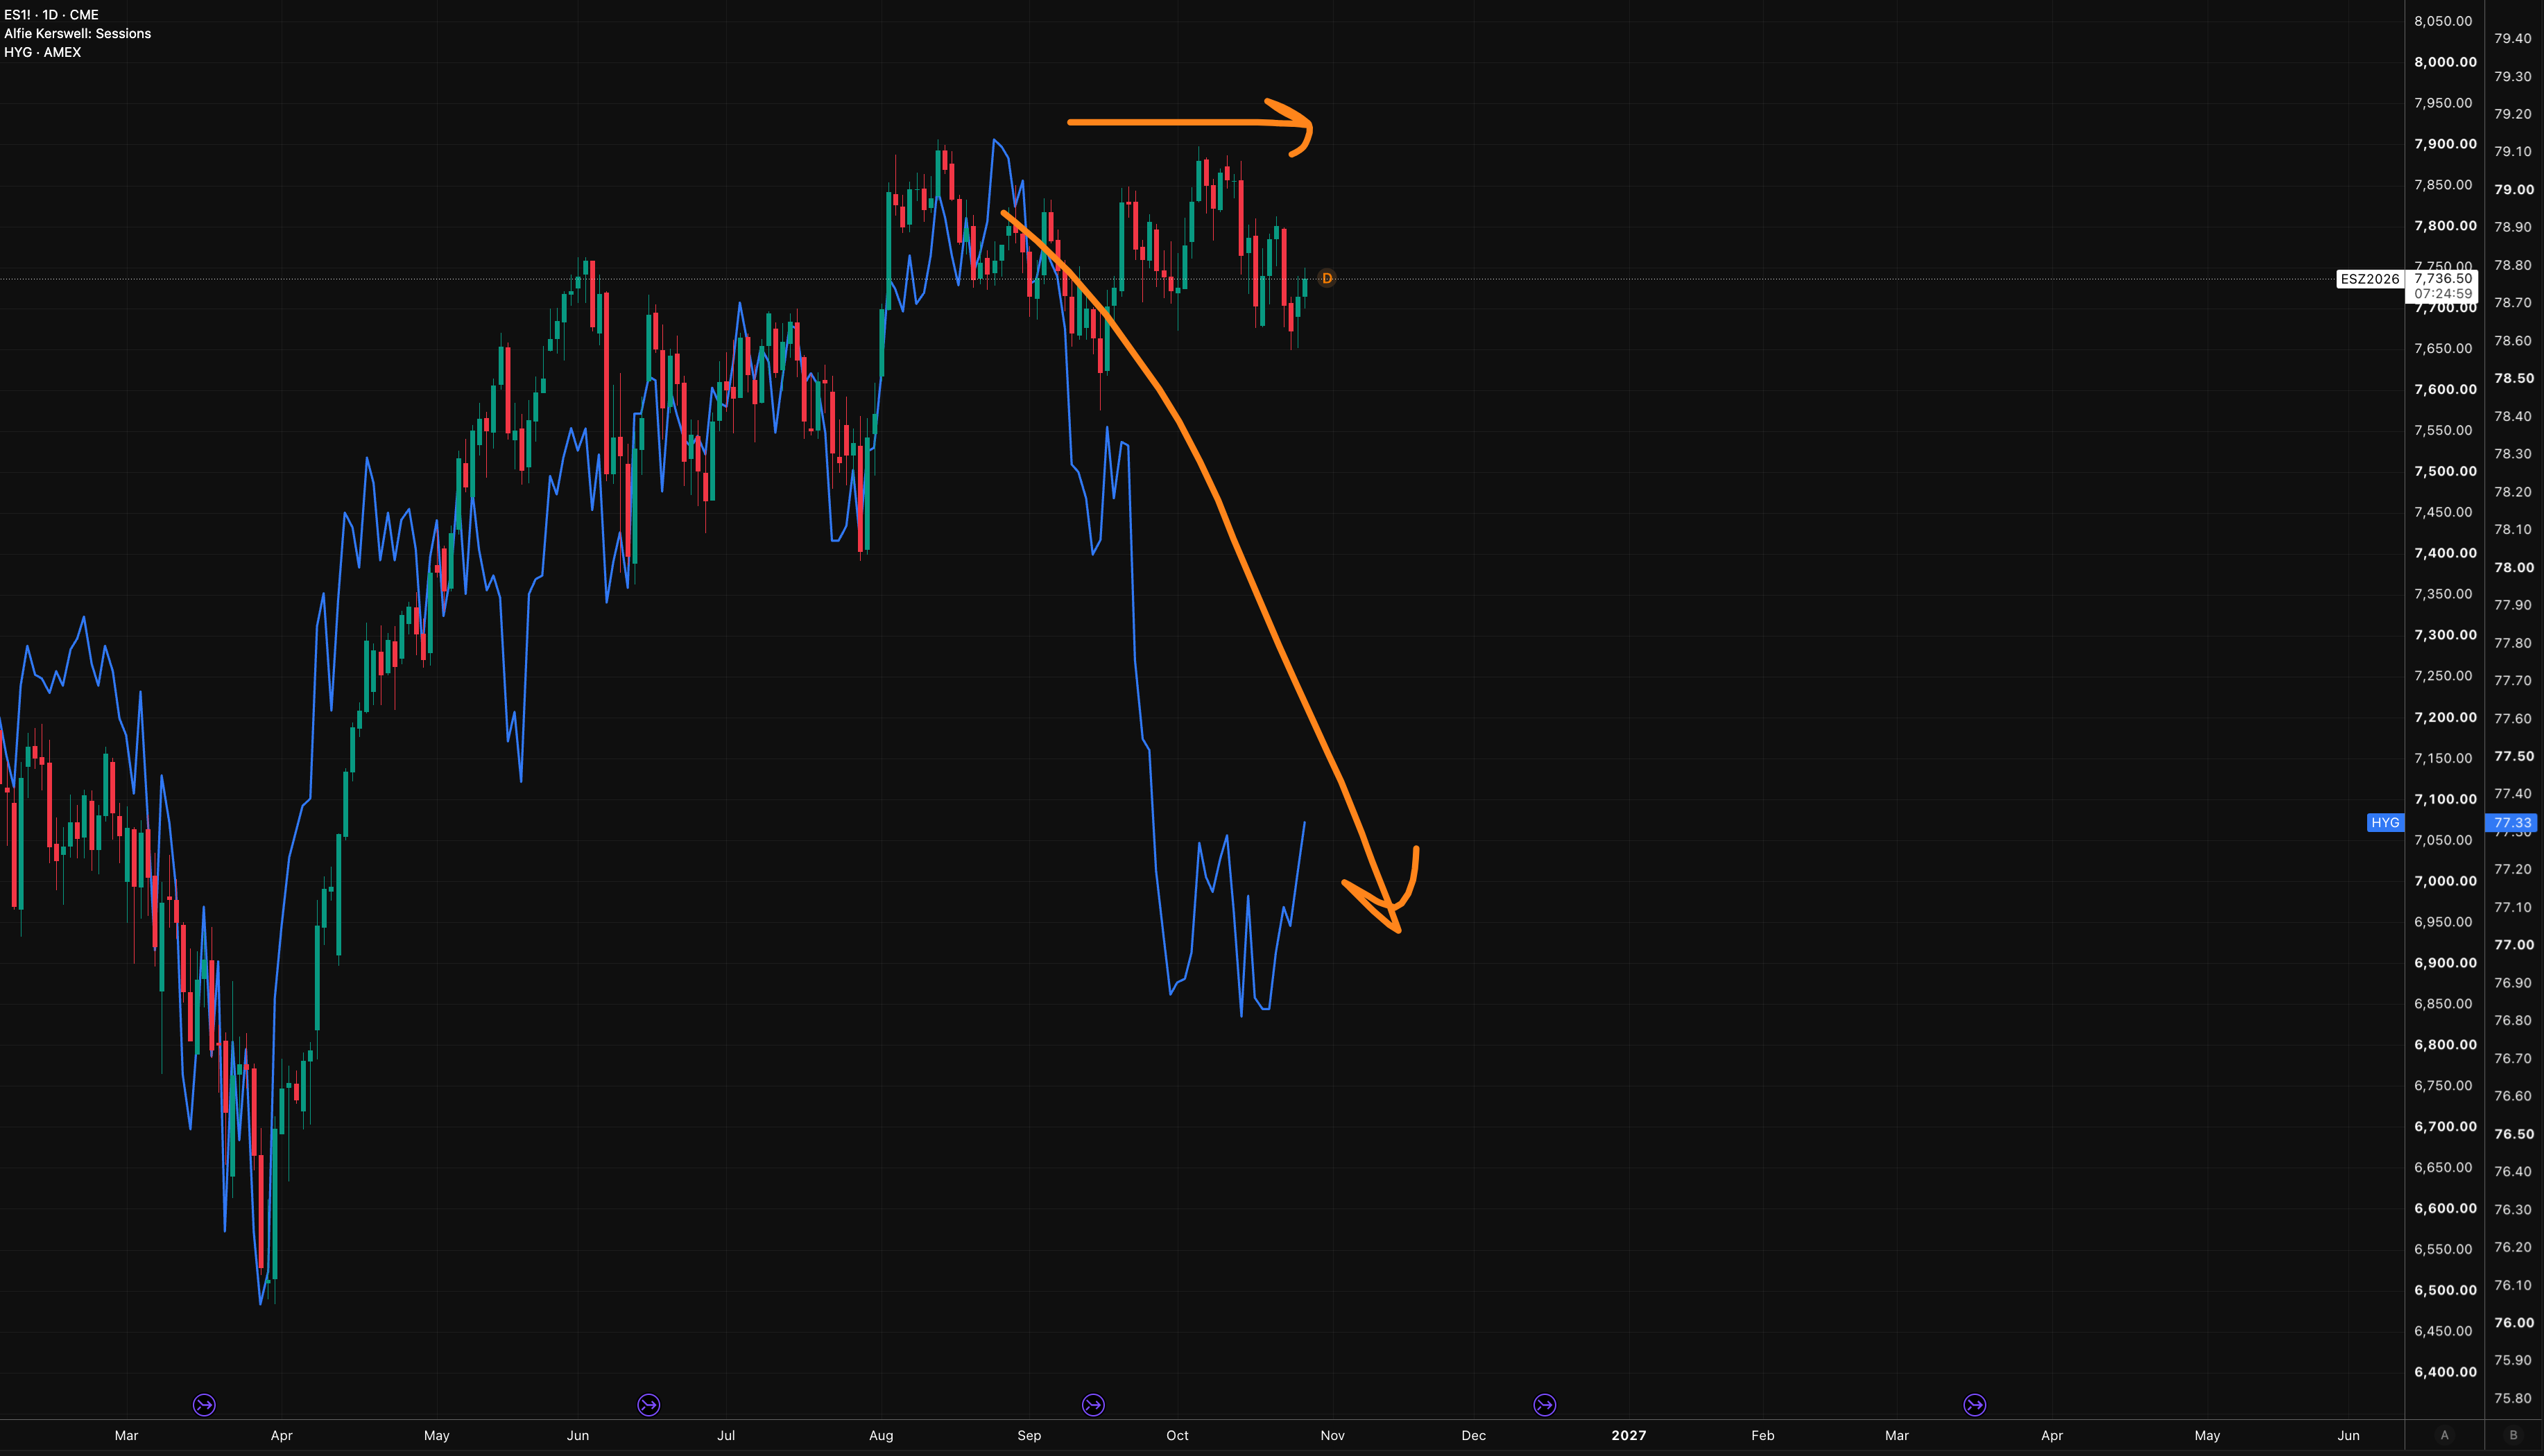
Credit spreads are being dragged wider by fears surrounding oil (which is why we were seeing oil up, bonds up). But I want to emphasise that there is clearly minimal risks to growth in the near-term and if there were to be some type of massive shock to growth, it would have to be exogenous.
However, I’m not discounting the marginal revisions to growth due to higher rates, but the level that both equities and bonds are trading at tells us CLEARLY that growth is not a large enough risk right now to cause any major or sustained drawdown. The risks to equities now sit in inflation in the near-term. Low-beta leadership is showing us that the markets are pricing a margin and demand hit but growth.
The move higher in credit spreads then hit the weakest most levered credit, AI capex and CCCs first which is why we see massive rotations (NOT RISK-OFF) in tech. Sectors inside the S&P have held a low correlation because defensives and energy have been moving in opposite directions (which is why the index has been in a range, because these sectors have neutralised eachother). Falling yields cushioned valuations a little which also provided some support to the index during this rotation.