

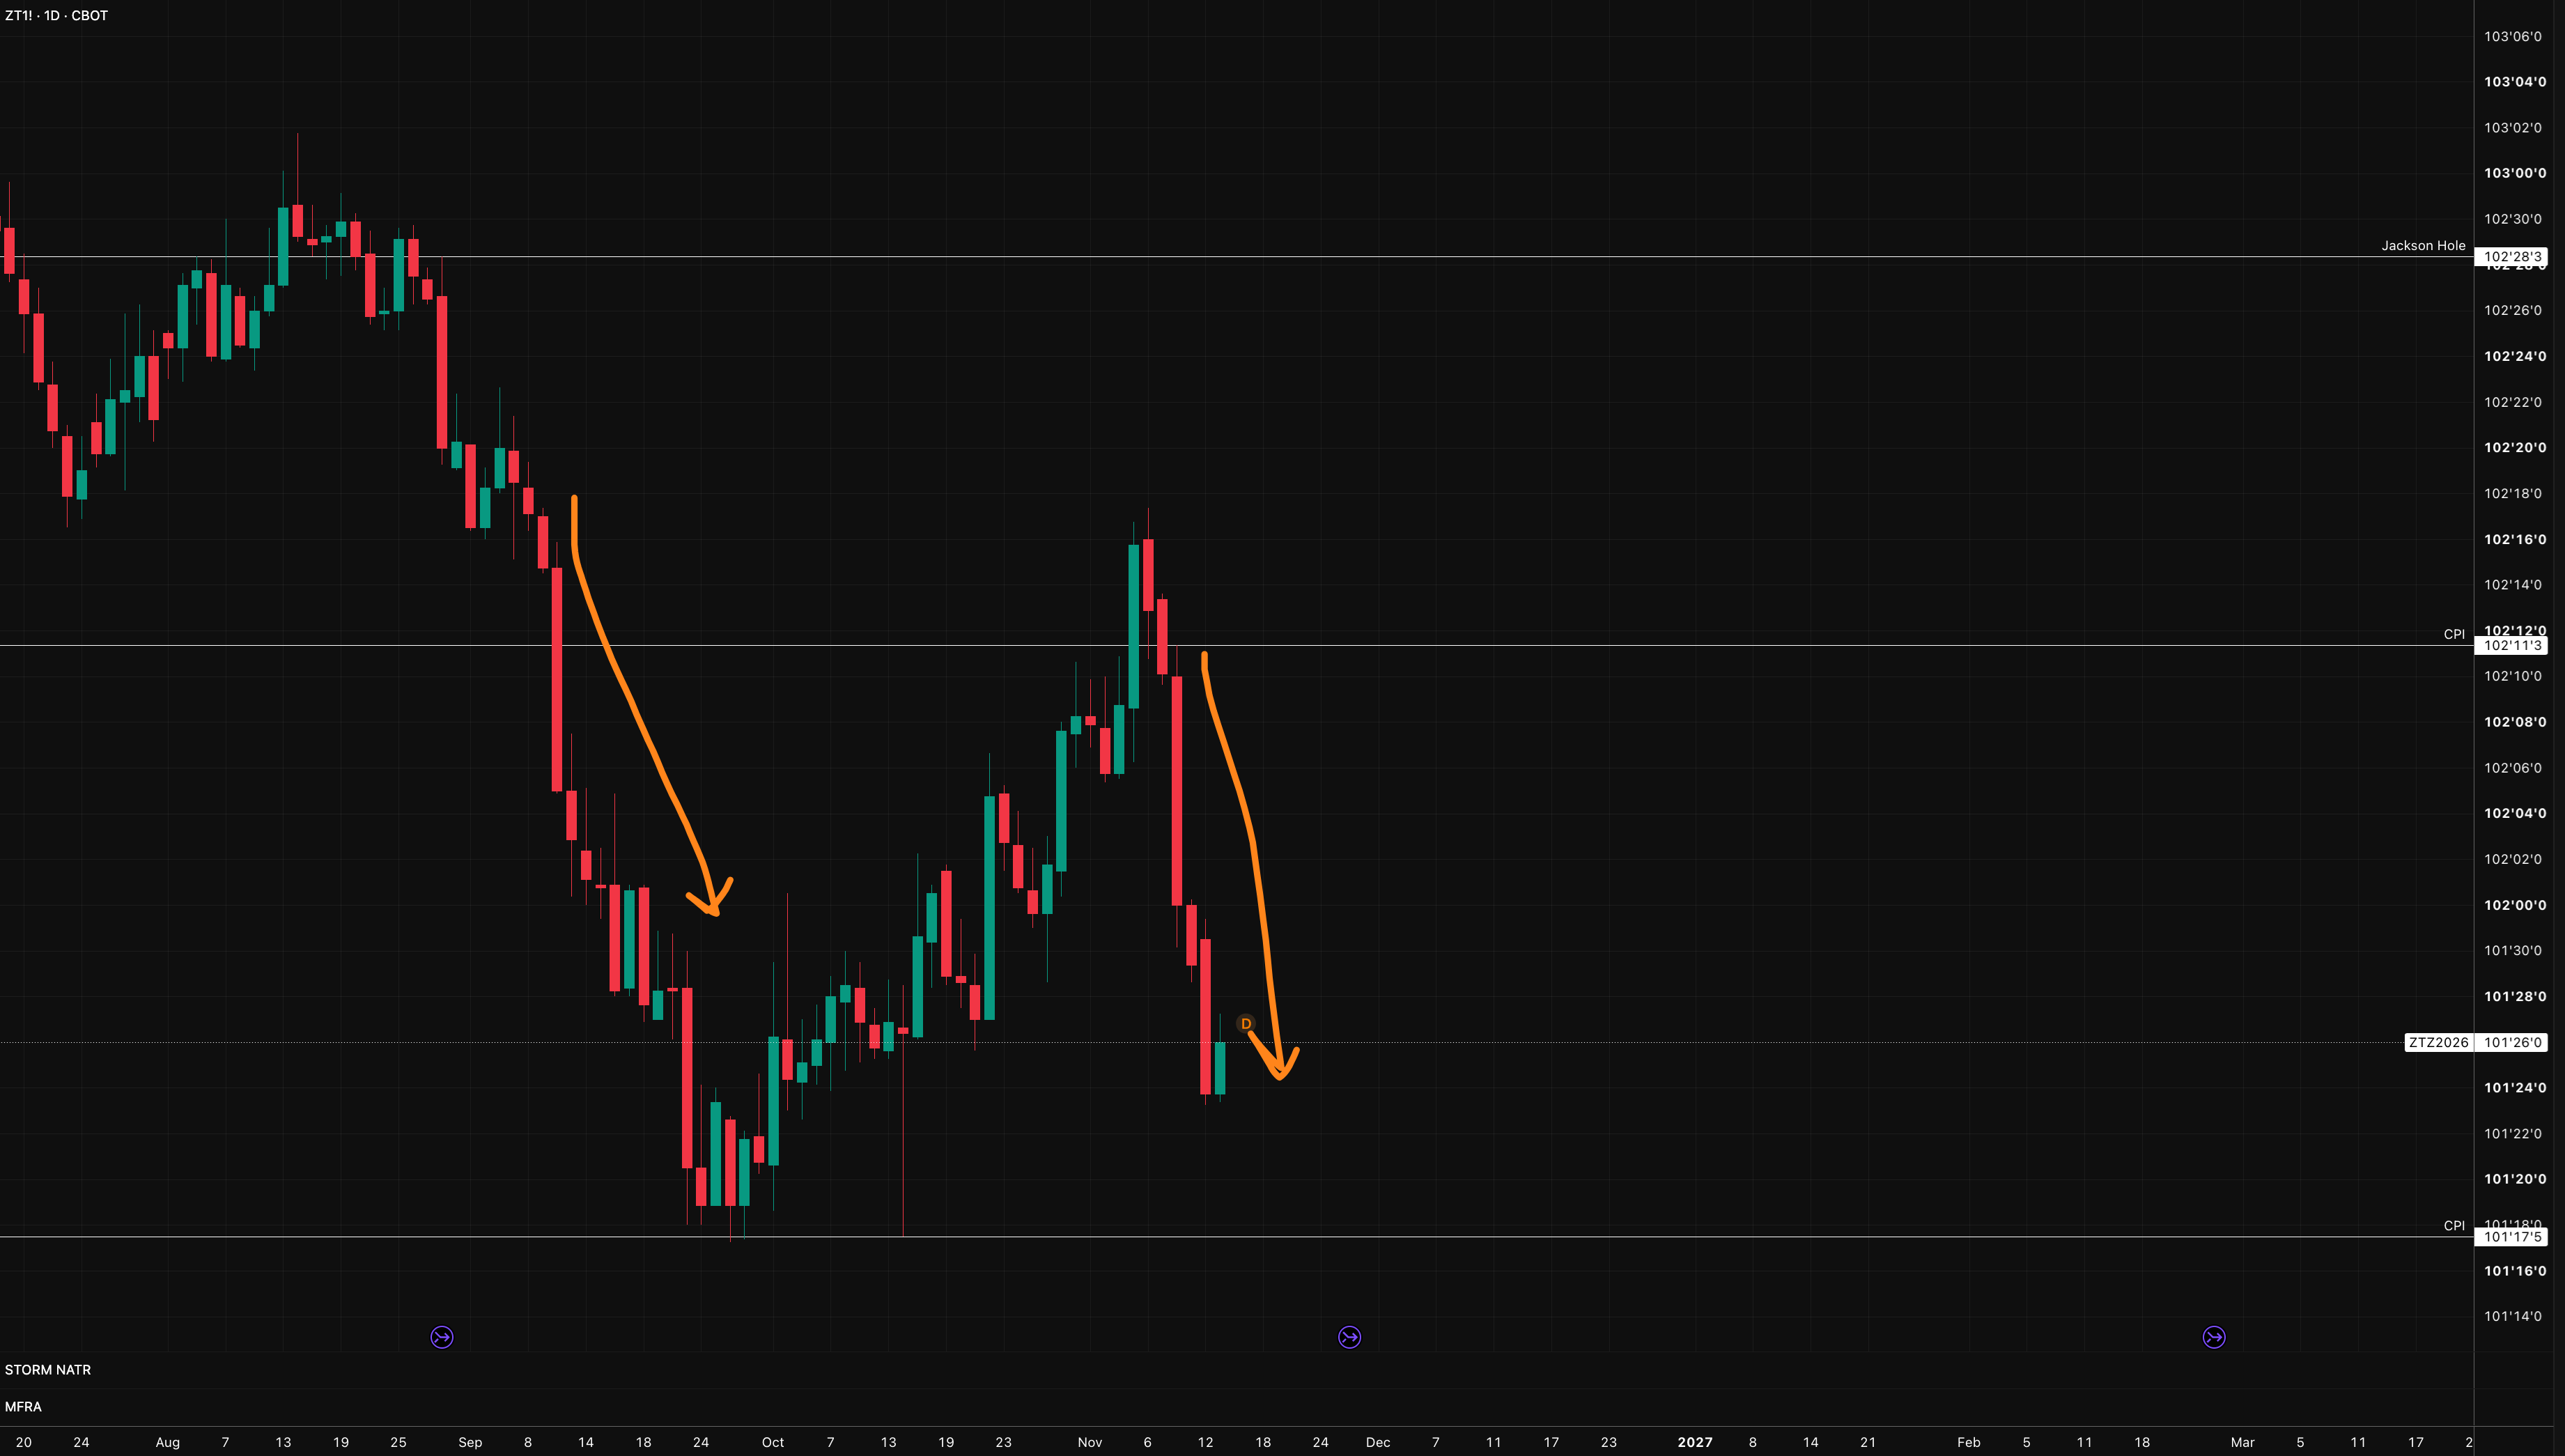
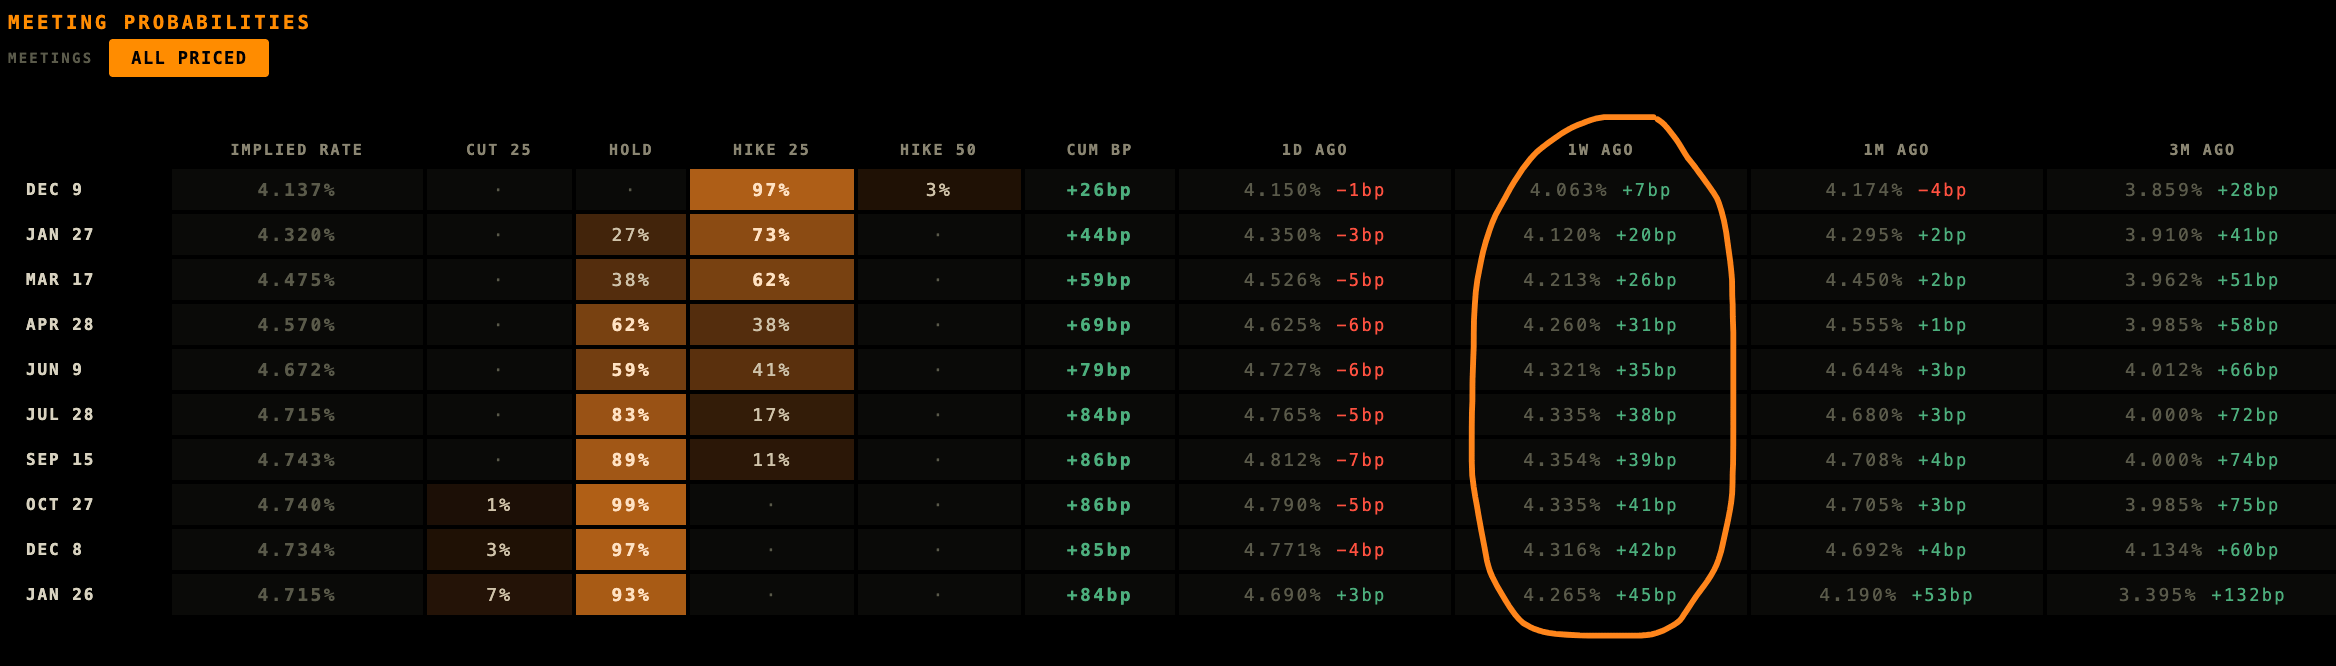
As we moved through CPI this week, the forward curve repriced pretty significantly as more hikes were added to 2027. The mispricing in rates before the print was pretty clear as inflation is coming from multiple sources. The curve bear flattened pretty significantly which is how a market tells you that it believes the Fed will start to put the foot on the gas a little and catch up rather than continue falling behind. ZT sold off pretty significantly as we progressed through the week.
What I’m starting to notice, which clarifies the fact the Fed are behind, is how aggressively the front-end reprices hikes in vs how it prices them out. In the chart above you’ll see that everytime we price hikes in, it happens with momentum, but every time hikes are priced out, it’s very gradual and that’s simply because both the growth and inflation backdrop simply doesn’t warrant these hikes being priced out, and I don’t think that’s going to change anytime soon.
A policy mistake is always going to show up in either the long-end bear steepening or the currency falling. Neither are giving clarity on a mistake and I don’t think we’ve come to an inflection point yet where the market truly prices a policy mistake, we’re more in the phase of the front-end just playing catch up.
Waller even went into the print saying that hiking only 25bp would the Fed’s credibility at risk (true). The model I’m running in Fed speak flipped aggressively through this week too.
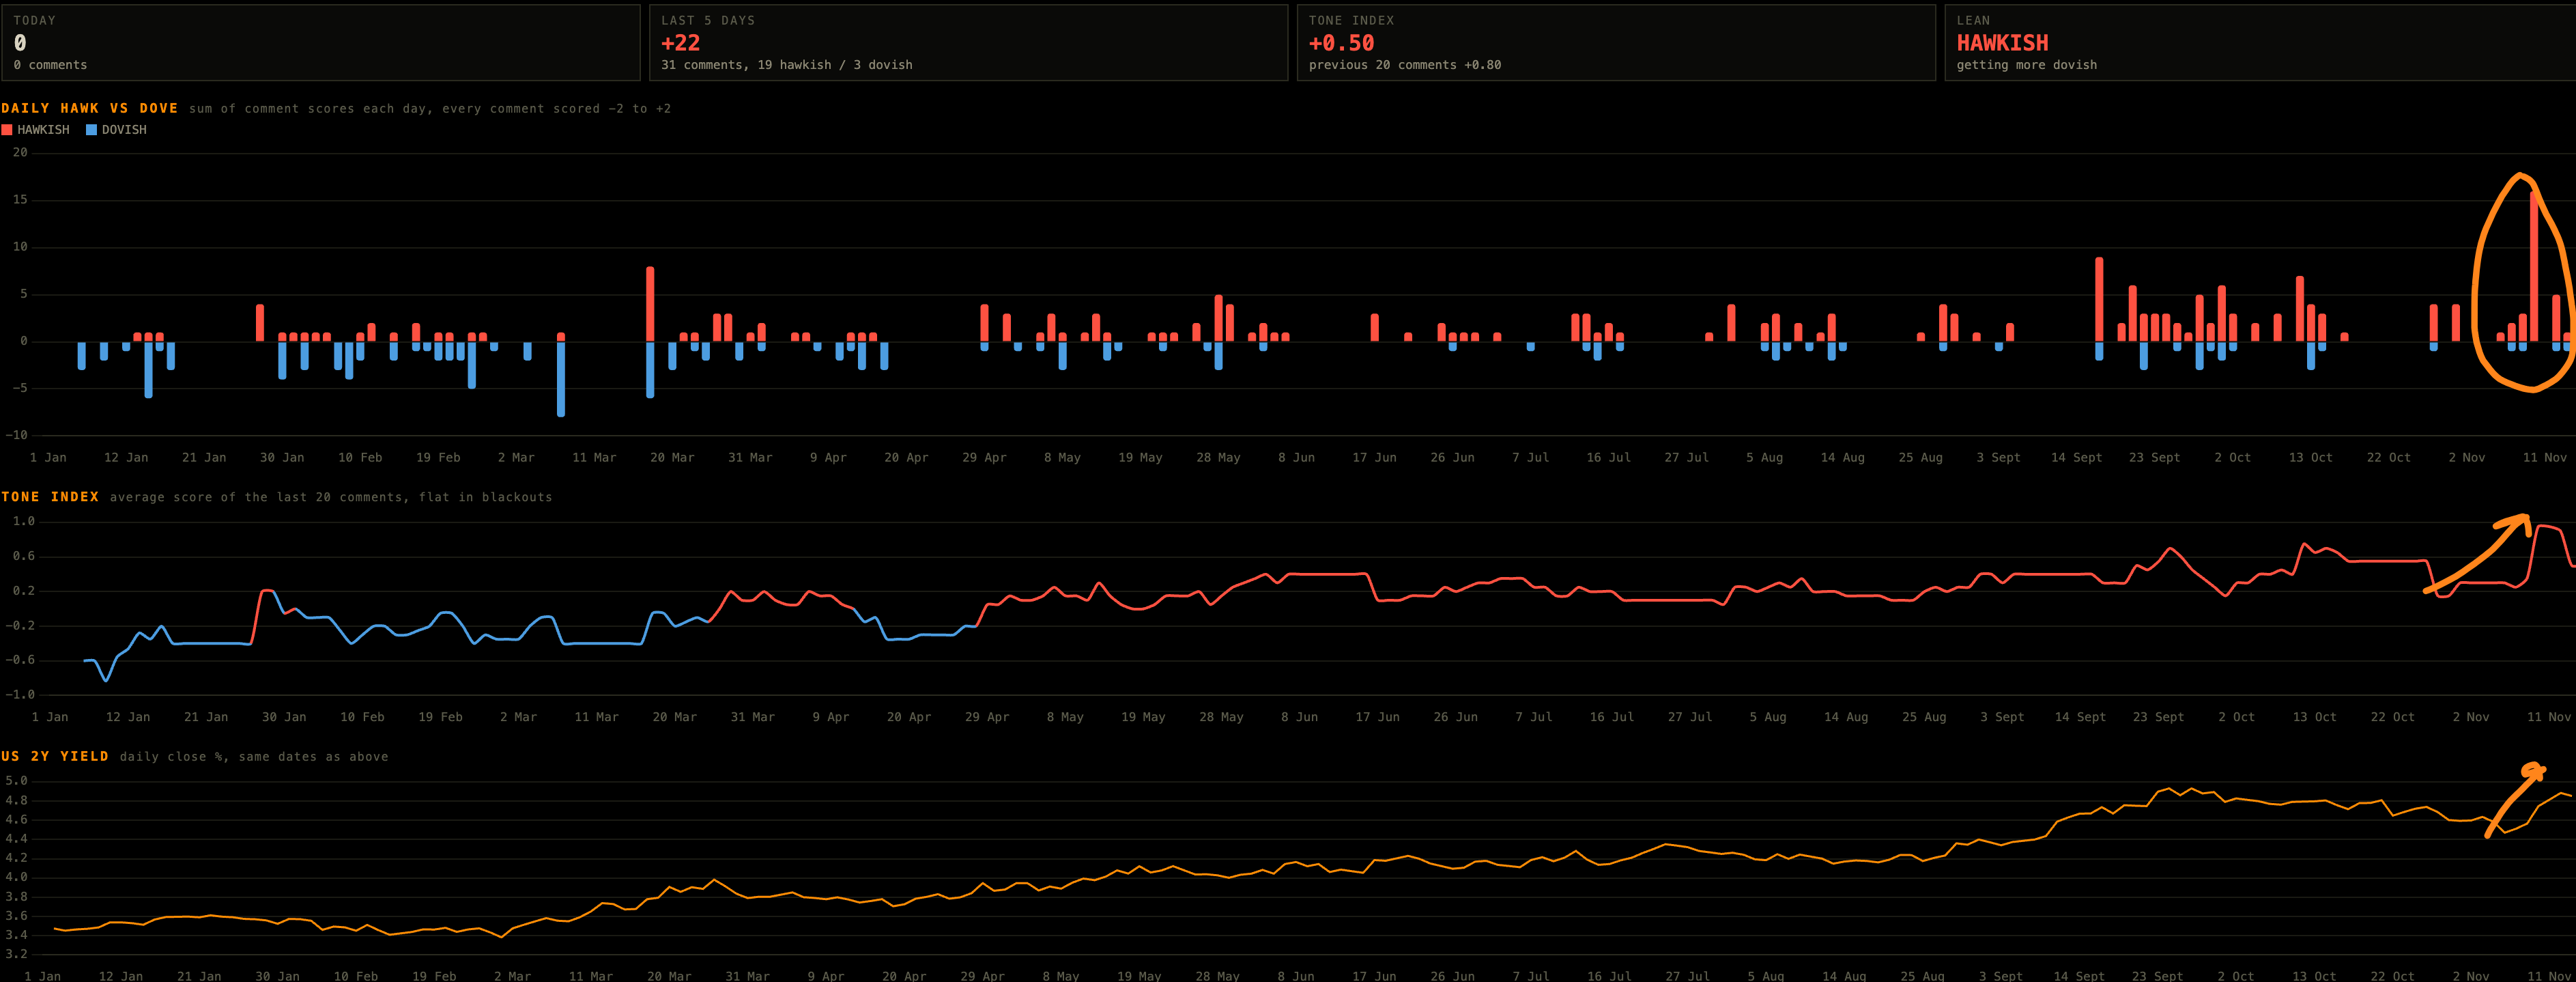
There is also another model I’m running below (which will be available in the systematic reports) which shows how much downside pressures exist for bonds and how much upside pressure exists for hikes. This is exactly why I closed my long ZT position that I sent to paid subs, there is simply just not a catalyst that exists in growth or inflation right now that warrants being long bonds.